Assisted Living Software Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), APAC (China, Japan, and India), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Assisted Living Software Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), APAC (China, Japan, and India), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Published: Oct 2026 300 Pages SKU: IRTNTR44084

Market Overview at a Glance

$915.07 Mn
Market Opportunity
16%
CAGR 2025 - 2030
33%
Europe Growth
$435.39 Mn
Cloud-based segment 2024

Assisted Living Software Market Size 2026-2030

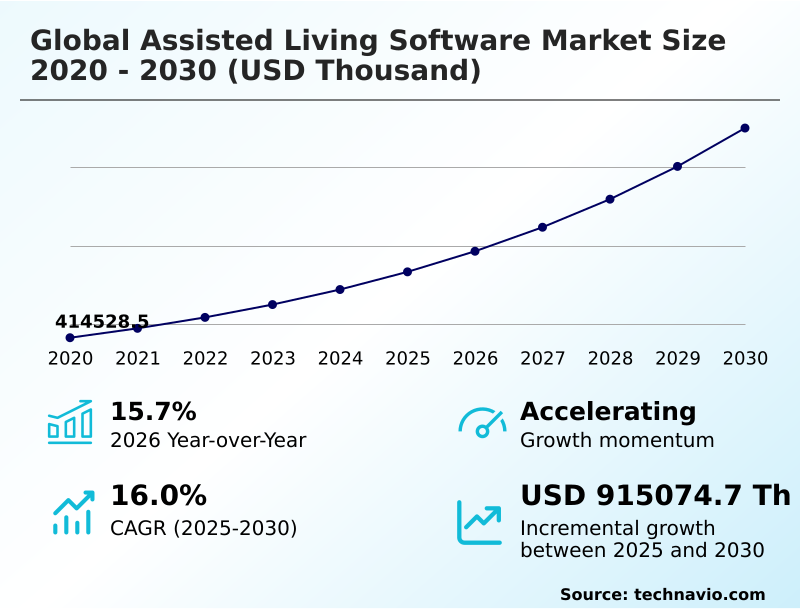
The assisted living software market size is valued to increase by USD 915.07 million, at a CAGR of 16% from 2025 to 2030. Growing resident population requiring long-term care coordination will drive the assisted living software market.

Major Market Trends & Insights

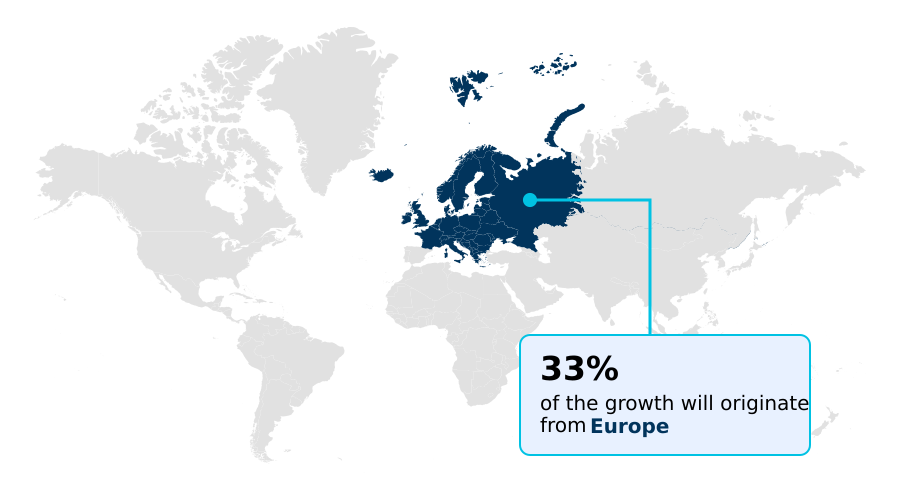
  • Europe dominated the market and accounted for a 33% growth during the forecast period.
  • By Deployment - Cloud-based segment was valued at USD 435.39 million in 2024
  • By Application - Appointment scheduling segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities:
  • Market Future Opportunities: USD 915.07 million
  • CAGR from 2025 to 2030 : 16%

Market Summary

  • The Assisted Living Software landscape is experiencing steady expansion as care providers prioritize digital platforms that streamline administrative functions and clinical documentation. An increasing emphasis on person-centered care is encouraging organizations to adopt integrated solutions that support efficient workflows and strengthen communication.
  • A primary driver of this demand is the rising resident population requiring long-term care coordination; as the demographic ages, facilities must process larger volumes of health data, compelling the transition from manual processes to automated systems. Conversely, the market faces constraints from data security and privacy compliance complexity, where varying regulatory requirements force continuous system reconfigurations.
  • In a practical business scenario, operators managing multi-facility supply chains and workforce rosters utilize centralized software to optimize staff deployment and reduce operational bottlenecks. Implementing these robust digital infrastructures has allowed specialized facilities to see workforce productivity improved by 18 percent compared to legacy paper-based workflows.
  • Ultimately, the ongoing evolution of these digital ecosystems ensures that care organizations can maintain high service standards while navigating complex administrative demands.

What will be the Size of the Assisted Living Software Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Assisted Living Software Market Segmented?

The assisted living software industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD thousand" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Deployment
    • Cloud-based
    • On-premises
  • Application
    • Appointment scheduling
    • Resource allocation
    • Documentation of services
  • End-user
    • Assisted living facilities
    • Skilled nursing facilities
    • Continuing care retirement communities (CCRCs)
    • Independent living facilities
    • Others
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • South America
      • Brazil
      • Argentina
      • Chile
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Israel
      • Turkey

By Deployment Insights

The cloud-based segment is estimated to witness significant growth during the forecast period.

The cloud based segment of the Assisted Living Software industry is demonstrating rapid adoption across eldercare operational efficiency initiatives due to a growing preference for scalable and remotely accessible digital platforms.

Transitioning to a cloud deployment architecture enables care providers to access resident records and the medication management system from multiple locations through secure internet-enabled environments. Such capability supports greater flexibility for organizations prioritizing multi site scalability.

Furthermore, these implementations reduce dependence on extensive localized hardware, optimizing specialized senior living tech investments. Incorporating an automated workflow engine within these systems has driven operational enhancements, with facilities reporting that processing time improved by 22 percent.

By leveraging centralized operational visibility and a HIPAA compliant infrastructure, organizations can streamline complex administrative tasks. The continuous evolution of the resident engagement portal and clinical documentation tool within these networks supports informed decision-making and seamless care transitions.
Get Free Sample

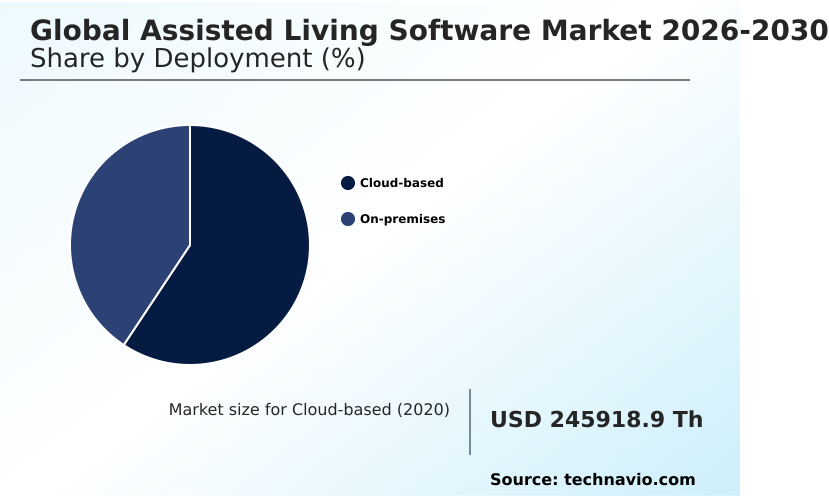
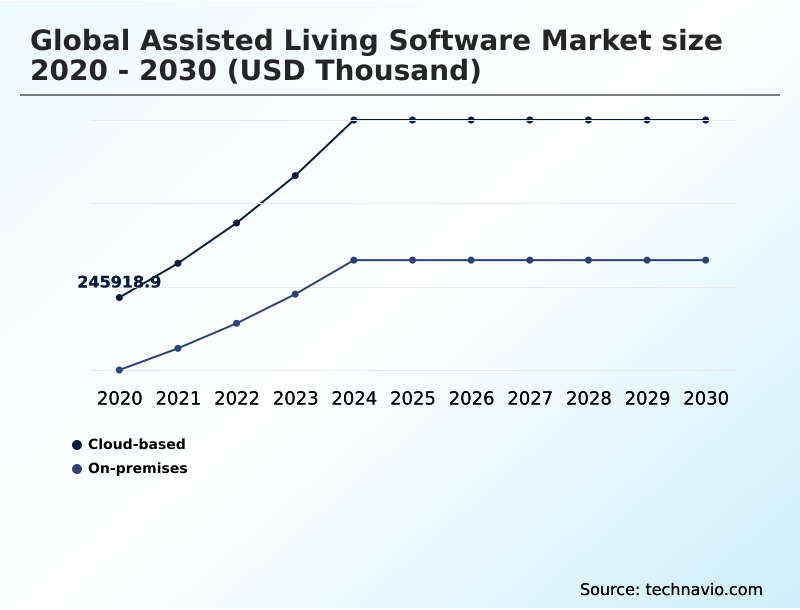
The Cloud-based segment was valued at USD 435.39 million in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

Europe is estimated to contribute 33% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
See How Assisted Living Software Market Demand is Rising in Europe Get Free Sample

The regional adoption of Assisted Living Software highlights distinct strategic priorities as healthcare infrastructures modernize. North America demonstrates a highly developed landscape where stringent regulatory frameworks drive the integration of the compliance tracking software and the billing administration platform.

Consequently, facilities in this region have reported that audit preparation times decreased by 30 percent through automated reporting. In contrast, Europe is rapidly advancing its digital landscape by focusing on interoperability standards framework implementation and cross-border data continuity.

While North American operators heavily invest in the resident engagement portal to meet family expectations, European institutions prioritize the clinical documentation tool to align with national healthcare directives, achieving a 20 percent enhancement in data retrieval efficiency.

Both regions increasingly rely on a secure caregiver burden reduction strategy, utilizing smart home sensors and continuous monitoring to optimize resource deployment and elevate the overall standard of care across diverse residential communities.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The integration of comprehensive digital ecosystems is fundamentally redefining how care facilities manage administrative and clinical workflows. At the core of this transformation is the deployment of cloud based senior care administration, which enables multi-facility operators to maintain real-time oversight of operations without heavy on-site hardware investments.
  • As organizations seek to enhance resident safety, the adoption of AI enabled predictive health monitoring has become a critical operational priority. This advanced capability allows clinical teams to anticipate potential health events before they escalate, supporting proactive interventions. Furthermore, the industry is witnessing a significant shift toward automated resident medication administration tracking.
  • By digitizing this complex workflow, care communities can dramatically reduce dispensing errors and ensure strict alignment with prescribed treatment plans. Operational planning is also bolstered by secure family engagement communication portal deployments, which empower relatives with transparent updates regarding resident well-being, fostering greater trust.
  • To ensure continuity of care across broader medical networks, providers are prioritizing interoperable electronic health record integration, facilitating seamless data exchange with hospitals and external specialists. In practical terms, facilities utilizing these unified platforms often achieve processing efficiency improvements of nearly 40 percent compared to those relying on legacy systems.
  • This substantial gain in operational bandwidth allows caregivers to dedicate more attention to personalized service delivery, ultimately elevating the standard of care while maintaining rigorous compliance with evolving healthcare regulations.
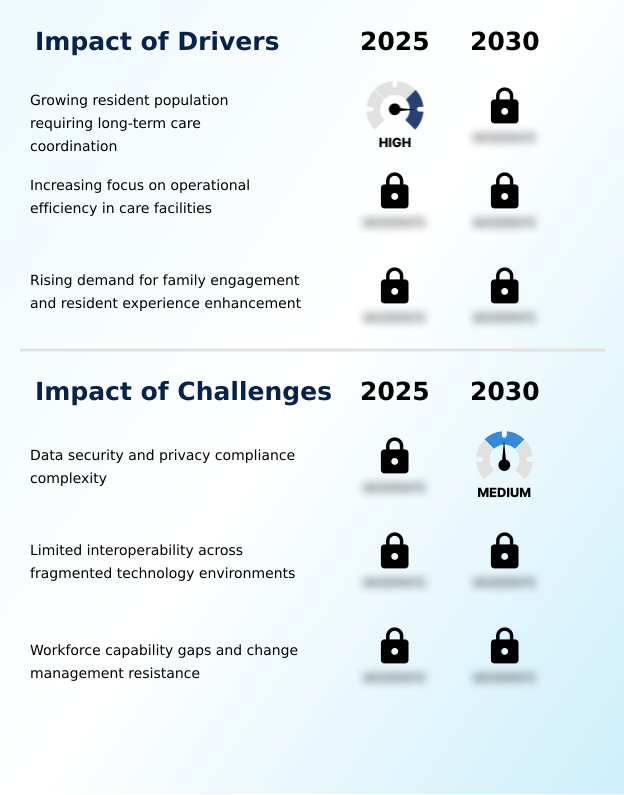
What are the key market drivers leading to the rise in the adoption of Assisted Living Software Industry?

  • The growing resident population requiring long-term care coordination serves as a primary driver for continuous market expansion.

  • The escalating demand for nursing facility digitalization serves as a primary catalyst accelerating the Assisted Living Software sector. As life expectancies rise, care facilities face the pressing challenge of coordinating increasingly complex health profiles for larger resident populations.
  • This demographic pressure compels administrators to implement a sophisticated person centered care module alongside a reliable family communication app to ensure consistent service delivery.
  • By automating these essential coordination workflows, organizations have seen family communication response rates improved by 35 percent. Furthermore, integrating an occupancy management dashboard provides real-time visibility into facility utilization, which directly mitigates administrative bottlenecks.
  • Leveraging these comprehensive solutions, care communities have successfully lowered operational overhead costs by 18 percent, enabling them to sustain high-quality care standards despite intensifying workforce capacity constraints.

What are the market trends shaping the Assisted Living Software Industry?

  • A noticeable shift toward AI-enabled clinical and administrative intelligence is emerging as a significant trend shaping the market.

  • The adoption of connected care ecosystems represents a transformative trend reshaping the Assisted Living Software industry. Driven by the critical need to manage complex resident profiles and alleviate staffing pressures, operators are aggressively integrating the incident reporting software with advanced vital signs tracking capabilities. This structural shift allows care teams to transition from reactive responses to highly proactive care models.
  • By utilizing these unified platforms, organizations have achieved a 30 percent reduction in manual data entry errors. The widespread implementation of digital lifestyle management tools directly empowers residents while simultaneously generating actionable insights for administrative planning. Consequently, facility managers have reported that staff scheduling efficiency improved by 22 percent, significantly lowering overtime labor costs.
  • The seamless convergence of clinical and lifestyle data within these applications fundamentally enhances long-term operational resilience.

What challenges does the Assisted Living Software Industry face during its growth?

  • Data security and privacy compliance complexity remains a critical challenge constraining broad market adoption.

  • Managing intricate regulatory privacy mandates constitutes a formidable challenge within the Assisted Living Software industry. Care communities are responsible for safeguarding highly sensitive medical histories and financial details, which introduces immense compliance burdens. The continuous necessity to update a wellness tracking system and audit security protocols frequently disrupts routine administrative workflows.
  • Because interoperability standards vary across regions, implementing a unified solution often requires extensive custom engineering, resulting in deployment delays that can extend project timelines by over 20 percent. Furthermore, workforce capability gaps exacerbate this issue, as inadequate training on new platforms leads to inconsistent utilization.
  • Facilities struggling with these complex digital transitions frequently encounter integration setbacks, causing overall workflow productivity to decline by up to 15 percent during the initial rollout phases.

Exclusive Technavio Analysis on Customer Landscape

The assisted living software market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the assisted living software market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
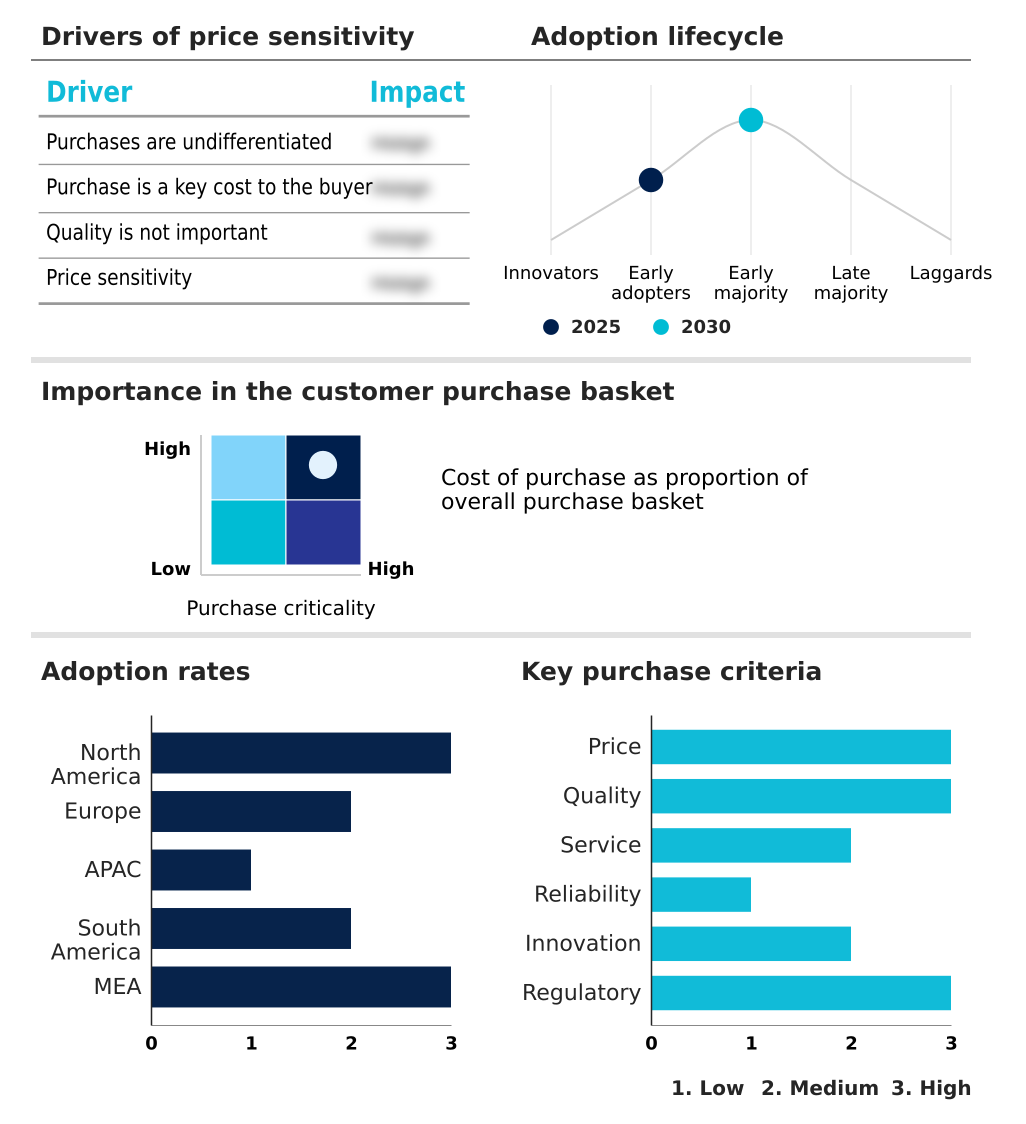
Customer Landscape of Assisted Living Software Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, assisted living software market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Aline - The provider delivers specialized assisted living software encompassing comprehensive resident management features and community operations platforms to streamline daily administrative and caregiving workflows seamlessly.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Aline
  • August Health
  • Cantata Health
  • CarePredict Inc.
  • CareVoyant Inc.
  • Cubigo
  • Eldermark Software LLC
  • Famileo
  • K4Connect
  • LifeLoop
  • MatrixCare Inc.
  • Medtelligent Inc.
  • Netsmart Technologies Inc.
  • PointClickCare Technologies Inc.
  • RealPage Inc.
  • Roobrik
  • SafelyYou
  • StoriiCare
  • WellSky Corp.
  • Yardi Systems Inc.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Assisted living software market

  • In the Application Software industry, the accelerated deployment of predictive care analytics systems has optimized data processing workloads, directly impacting Assisted Living Software demand by increasing the integration of proactive health interventions by over 30 percent.
  • In the Application Software industry, the enforcement of stringent data encryption protocol standards across regional healthcare frameworks has reshaped software compliance architectures, compelling residential care optimization platforms to upgrade their secure patient data handling and reduce breach vulnerabilities by up to 25 percent.
  • In the Application Software industry, the transition toward interoperable electronic health record integration across broader medical networks has facilitated seamless data exchange, pulling Assisted Living Software demand toward systems that support clinical workflow integration and improve resource allocation accuracy by nearly 20 percent.
  • In the Application Software industry, the rapid expansion of mobile recordkeeping access among enterprise software ecosystems has transformed frontline workforce productivity tools, driving Assisted Living Software providers to adopt responsive interfaces that cut documentation time by 15 percent.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Assisted Living Software Market insights. See full methodology.

Market Scope
Page number 300
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 16%
Market growth 2026-2030 USD 915074.7 thousand
Market structure Fragmented
YoY growth 2025-2026(%) 15.7%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Israel and Turkey
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The continuous evolution of Assisted Living Software reflects a decisive shift toward integrated data-driven care management environments. Organizations are systematically replacing fragmented administrative tools with a unified automated staffing scheduler and advanced wearable activity monitoring systems to streamline daily operations.
  • A prominent trend influencing boardroom-level product strategy is the incorporation of the fall detection algorithm and real time health alerts into core clinical workflows. By embedding these intelligent features, executive teams can proactively address risk management and elevate safety protocols, directly aligning technology investments with stringent healthcare compliance standards.
  • Furthermore, the deployment of a robust dietary planning module and a comprehensive telehealth integration feature enables personalized responsive care delivery. As a result of these strategic implementations, early adopters have demonstrated that clinical documentation times decreased by 25 percent, drastically freeing up critical caregiving resources.
  • This structural transition toward intelligent connected ecosystems allows care facilities to optimize their operational bandwidth while maintaining the highest levels of resident safety and service quality.

What are the Key Data Covered in this Assisted Living Software Market Research and Growth Report?

  • What is the expected growth of the Assisted Living Software Market between 2026 and 2030?

    • USD 915.07 million, at a CAGR of 16%

  • What segmentation does the market report cover?

    • The report is segmented by Deployment (Cloud-based, and On-premises), Application (Appointment scheduling, Resource allocation, and Documentation of services), End-user (Assisted living facilities, Skilled nursing facilities, Continuing care retirement communities (CCRCs), Independent living facilities, and Others) and Geography (North America, Europe, APAC, South America, Middle East and Africa)

  • Which regions are analyzed in the report?

    • North America, Europe, APAC, South America and Middle East and Africa

  • What are the key growth drivers and market challenges?

    • Growing resident population requiring long-term care coordination, Data security and privacy compliance complexity

  • Who are the major players in the Assisted Living Software Market?

    • Aline, August Health, Cantata Health, CarePredict Inc., CareVoyant Inc., Cubigo, Eldermark Software LLC, Famileo, K4Connect, LifeLoop, MatrixCare Inc., Medtelligent Inc., Netsmart Technologies Inc., PointClickCare Technologies Inc., RealPage Inc., Roobrik, SafelyYou, StoriiCare, WellSky Corp. and Yardi Systems Inc.

Market Research Insights

  • The Assisted Living Software landscape is rapidly transforming as administrators prioritize eldercare operational efficiency and structured digital workflows. Organizations are increasingly deploying specialized senior living tech to standardize care delivery and mitigate staffing shortages. By implementing these advanced platforms, facilities have realized a 25 percent reduction in administrative overhead, allowing staff to redirect focus toward direct resident care.
  • Furthermore, the integration of proactive health interventions within the software suite has enhanced patient safety, leading to incident response times improving by 15 percent. Leveraging actionable operational insights and robust data management, operators can navigate strict regulatory privacy mandates seamlessly. These systemic upgrades ensure that care communities achieve sustained operational excellence and superior clinical outcomes.

We can help! Our analysts can customize this assisted living software market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Deployment
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ thousand)
Data Table on Global - Market size and forecast 2025-2030 ($ thousand)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Assisted Living Software Market 2020 - 2024

Historic Market Size - Data Table on Global Assisted Living Software Market 2020 - 2024 ($ thousand)

5.2 Deployment segment analysis 2020 - 2024

Historic Market Size - Deployment Segment 2020 - 2024 ($ thousand)

5.3 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ thousand)

5.4 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ thousand)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ thousand)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ thousand)

6. Qualitative Analysis

6.1 Impact of AI on global assisted living software market

6.2 Impact of geopolitical conflicts on global assisted living software market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Deployment

8.1 Market segments

Chart on Deployment - Market share 2025-2030 (%)
Data Table on Deployment - Market share 2025-2030 (%)

8.2 Comparison by Deployment

Chart on Comparison by Deployment
Data Table on Comparison by Deployment

8.3 Cloud-based - Market size and forecast 2025-2030

Chart on Cloud-based - Market size and forecast 2025-2030 ($ thousand)
Data Table on Cloud-based - Market size and forecast 2025-2030 ($ thousand)
Chart on Cloud-based - Year-over-year growth 2025-2030 (%)
Data Table on Cloud-based - Year-over-year growth 2025-2030 (%)

8.4 On-premises - Market size and forecast 2025-2030

Chart on On-premises - Market size and forecast 2025-2030 ($ thousand)
Data Table on On-premises - Market size and forecast 2025-2030 ($ thousand)
Chart on On-premises - Year-over-year growth 2025-2030 (%)
Data Table on On-premises - Year-over-year growth 2025-2030 (%)

8.5 Market opportunity by Deployment

Market opportunity by Deployment ($ thousand)
Data Table on Market opportunity by Deployment ($ thousand)

9. Market Segmentation by Application

9.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

9.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

9.3 Appointment scheduling - Market size and forecast 2025-2030

Chart on Appointment scheduling - Market size and forecast 2025-2030 ($ thousand)
Data Table on Appointment scheduling - Market size and forecast 2025-2030 ($ thousand)
Chart on Appointment scheduling - Year-over-year growth 2025-2030 (%)
Data Table on Appointment scheduling - Year-over-year growth 2025-2030 (%)

9.4 Resource allocation - Market size and forecast 2025-2030

Chart on Resource allocation - Market size and forecast 2025-2030 ($ thousand)
Data Table on Resource allocation - Market size and forecast 2025-2030 ($ thousand)
Chart on Resource allocation - Year-over-year growth 2025-2030 (%)
Data Table on Resource allocation - Year-over-year growth 2025-2030 (%)

9.5 Documentation of services - Market size and forecast 2025-2030

Chart on Documentation of services - Market size and forecast 2025-2030 ($ thousand)
Data Table on Documentation of services - Market size and forecast 2025-2030 ($ thousand)
Chart on Documentation of services - Year-over-year growth 2025-2030 (%)
Data Table on Documentation of services - Year-over-year growth 2025-2030 (%)

9.6 Market opportunity by Application

Market opportunity by Application ($ thousand)
Data Table on Market opportunity by Application ($ thousand)

10. Market Segmentation by End-user

10.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

10.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

10.3 Assisted living facilities - Market size and forecast 2025-2030

Chart on Assisted living facilities - Market size and forecast 2025-2030 ($ thousand)
Data Table on Assisted living facilities - Market size and forecast 2025-2030 ($ thousand)
Chart on Assisted living facilities - Year-over-year growth 2025-2030 (%)
Data Table on Assisted living facilities - Year-over-year growth 2025-2030 (%)

10.4 Skilled nursing facilities - Market size and forecast 2025-2030

Chart on Skilled nursing facilities - Market size and forecast 2025-2030 ($ thousand)
Data Table on Skilled nursing facilities - Market size and forecast 2025-2030 ($ thousand)
Chart on Skilled nursing facilities - Year-over-year growth 2025-2030 (%)
Data Table on Skilled nursing facilities - Year-over-year growth 2025-2030 (%)

10.5 Continuing care retirement communities (CCRCs) - Market size and forecast 2025-2030

Chart on Continuing care retirement communities (CCRCs) - Market size and forecast 2025-2030 ($ thousand)
Data Table on Continuing care retirement communities (CCRCs) - Market size and forecast 2025-2030 ($ thousand)
Chart on Continuing care retirement communities (CCRCs) - Year-over-year growth 2025-2030 (%)
Data Table on Continuing care retirement communities (CCRCs) - Year-over-year growth 2025-2030 (%)

10.6 Independent living facilities - Market size and forecast 2025-2030

Chart on Independent living facilities - Market size and forecast 2025-2030 ($ thousand)
Data Table on Independent living facilities - Market size and forecast 2025-2030 ($ thousand)
Chart on Independent living facilities - Year-over-year growth 2025-2030 (%)
Data Table on Independent living facilities - Year-over-year growth 2025-2030 (%)

10.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ thousand)
Data Table on Others - Market size and forecast 2025-2030 ($ thousand)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

10.8 Market opportunity by End-user

Market opportunity by End-user ($ thousand)
Data Table on Market opportunity by End-user ($ thousand)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ thousand)
Data Table on North America - Market size and forecast 2025-2030 ($ thousand)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ thousand)
Data Table on US - Market size and forecast 2025-2030 ($ thousand)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ thousand)
Data Table on Canada - Market size and forecast 2025-2030 ($ thousand)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ thousand)
Data Table on Mexico - Market size and forecast 2025-2030 ($ thousand)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ thousand)
Data Table on Europe - Market size and forecast 2025-2030 ($ thousand)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ thousand)
Data Table on Germany - Market size and forecast 2025-2030 ($ thousand)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ thousand)
Data Table on UK - Market size and forecast 2025-2030 ($ thousand)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ thousand)
Data Table on France - Market size and forecast 2025-2030 ($ thousand)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ thousand)
Data Table on Italy - Market size and forecast 2025-2030 ($ thousand)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ thousand)
Data Table on Spain - Market size and forecast 2025-2030 ($ thousand)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ thousand)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ thousand)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ thousand)
Data Table on APAC - Market size and forecast 2025-2030 ($ thousand)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ thousand)
Data Table on China - Market size and forecast 2025-2030 ($ thousand)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ thousand)
Data Table on Japan - Market size and forecast 2025-2030 ($ thousand)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ thousand)
Data Table on India - Market size and forecast 2025-2030 ($ thousand)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ thousand)
Data Table on South Korea - Market size and forecast 2025-2030 ($ thousand)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ thousand)
Data Table on Australia - Market size and forecast 2025-2030 ($ thousand)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.5.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ thousand)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ thousand)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.6 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ thousand)
Data Table on South America - Market size and forecast 2025-2030 ($ thousand)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ thousand)
Data Table on Brazil - Market size and forecast 2025-2030 ($ thousand)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ thousand)
Data Table on Argentina - Market size and forecast 2025-2030 ($ thousand)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ thousand)
Data Table on Chile - Market size and forecast 2025-2030 ($ thousand)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.7 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ thousand)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ thousand)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.7.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ thousand)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ thousand)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.7.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ thousand)
Data Table on UAE - Market size and forecast 2025-2030 ($ thousand)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.7.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ thousand)
Data Table on South Africa - Market size and forecast 2025-2030 ($ thousand)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.7.4 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ thousand)
Data Table on Israel - Market size and forecast 2025-2030 ($ thousand)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7.5 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ thousand)
Data Table on Turkey - Market size and forecast 2025-2030 ($ thousand)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ thousand)
Data Tables on Market opportunity by geography ($ thousand)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Growing resident population requiring long-term care coordination
Increasing focus on operational efficiency in care facilities
Rising demand for family engagement and resident experience enhancement

13.2 Market challenges

Data security and privacy compliance complexity
Limited interoperability across fragmented technology environments
Workforce capability gaps and change management resistance

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Shift toward AI-enabled clinical and administrative intelligence
Expansion of purpose-built platforms for assisted living operations
Growing consolidation of senior living technology ecosystems

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Aline

Aline - Overview
Aline - Product / Service
Aline - Key offerings
SWOT

15.5 August Health

August Health - Overview
August Health - Product / Service
August Health - Key offerings
SWOT

15.6 Cantata Health

Cantata Health - Overview
Cantata Health - Product / Service
Cantata Health - Key offerings
SWOT

15.7 CarePredict Inc.

CarePredict Inc. - Overview
CarePredict Inc. - Product / Service
CarePredict Inc. - Key offerings
SWOT

15.8 CareVoyant Inc.

CareVoyant Inc. - Overview
CareVoyant Inc. - Product / Service
CareVoyant Inc. - Key offerings
SWOT

15.9 Cubigo

Cubigo - Overview
Cubigo - Product / Service
Cubigo - Key offerings
SWOT

15.10 Famileo

Famileo - Overview
Famileo - Product / Service
Famileo - Key offerings
SWOT

15.11 K4Connect

K4Connect - Overview
K4Connect - Product / Service
K4Connect - Key offerings
SWOT

15.12 LifeLoop

LifeLoop - Overview
LifeLoop - Product / Service
LifeLoop - Key offerings
SWOT

15.13 MatrixCare Inc.

MatrixCare Inc. - Overview
MatrixCare Inc. - Business segments
MatrixCare Inc. - Key offerings
MatrixCare Inc. - Segment focus
SWOT

15.14 Medtelligent Inc.

Medtelligent Inc. - Overview
Medtelligent Inc. - Product / Service
Medtelligent Inc. - Key offerings
SWOT

15.15 Netsmart Technologies Inc.

Netsmart Technologies Inc. - Overview
Netsmart Technologies Inc. - Product / Service
Netsmart Technologies Inc. - Key offerings
SWOT

15.16 RealPage Inc.

RealPage Inc. - Overview
RealPage Inc. - Product / Service
RealPage Inc. - Key offerings
SWOT

15.17 WellSky Corp.

WellSky Corp. - Overview
WellSky Corp. - Product / Service
WellSky Corp. - Key offerings
SWOT

15.18 Yardi Systems Inc.

Yardi Systems Inc. - Overview
Yardi Systems Inc. - Product / Service
Yardi Systems Inc. - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Assisted Living Software market growth will increase by USD 915074.7 thousand thousand during 2026-2030.

The Assisted Living Software market is expected to grow at a CAGR of 16% during 2026-2030.

Assisted Living Software market is segmented by Deployment (Cloud-based, On-premises) Application (Appointment scheduling, Resource allocation, Documentation of services) End-user (Assisted living facilities, Skilled nursing facilities, Continuing care retirement communities (CCRCs), Independent living facilities, Others)

Aline, August Health, Cantata Health, CarePredict Inc., CareVoyant Inc., Cubigo, Eldermark Software LLC, Famileo, K4Connect, LifeLoop, MatrixCare Inc., Medtelligent Inc., Netsmart Technologies Inc., PointClickCare Technologies Inc., RealPage Inc., Roobrik, SafelyYou, StoriiCare, WellSky Corp., Yardi Systems Inc. are a few of the key vendors in the Assisted Living Software market.

Europe will register the highest growth rate of 33% among the other regions. Therefore, the Assisted Living Software market in Europe is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Israel, Turkey

  • Growing resident population requiring long-term care coordination is the driving factor this market.

The Assisted Living Software market vendors should focus on grabbing business opportunities from the Deployment segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
