Building Automation Software Market Analysis, Size, and Forecast 2026-2030: APAC (China, Japan, and India), Europe (Germany, UK, and France), North America (US, Canada, and Mexico), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Building Automation Software Market Analysis, Size, and Forecast 2026-2030:
APAC (China, Japan, and India), Europe (Germany, UK, and France), North America (US, Canada, and Mexico), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Published: Oct 2026 299 Pages SKU: IRTNTR44182

Market Overview at a Glance

$45.84 B
Market Opportunity
16.2%
CAGR 2025 - 2030
41.8%
APAC Growth
$25.61 B
BMS software segment 2024

Building Automation Software Market Size 2026-2030

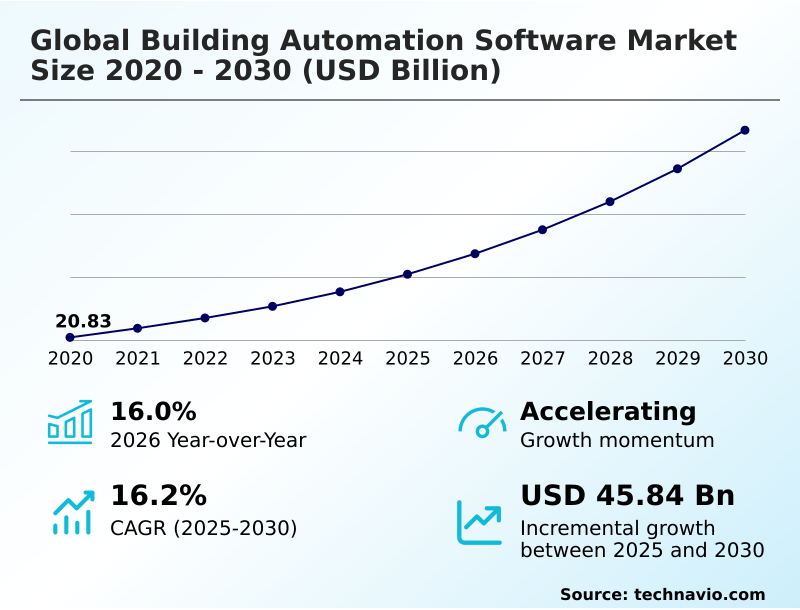
The building automation software market size is valued to increase by USD 45.84 billion, at a CAGR of 16.2% from 2025 to 2030. Escalating demand for energy efficiency and sustainability will drive the building automation software market.

Major Market Trends & Insights

  • APAC dominated the market and accounted for a 41.8% growth during the forecast period.
  • By Product - BMS software segment was valued at USD 25.61 billion in 2024
  • By End-user - Commercial segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 65.93 billion
  • Market Future Opportunities: USD 45.84 billion
  • CAGR from 2025 to 2030 : 16.2%

Market Summary

  • Building Automation Software functions as a critical enabler of sustainable infrastructure, providing centralized digital platforms to monitor and optimize complex facility operations. Organizations increasingly rely on these advanced systems to synchronize heating, ventilation, lighting, and overarching security networks through standard communication protocols.
  • In a practical supply chain optimization scenario, a massive logistics warehouse can deploy intelligent sensors to dynamically adjust climate controls based on immediate inventory storage requirements and workforce occupancy, thereby eliminating energy waste in unoccupied zones. Facilities leveraging such integrated platforms report a 22% reduction in utility expenditures compared to those utilizing isolated, manual control systems.
  • The escalating demand for operational energy efficiency acts as a primary market driver, compelling property developers to adopt automated monitoring tools to meet stringent corporate sustainability mandates and secure prestigious green building certifications. Conversely, the complexity of integrating legacy infrastructure poses a significant operational challenge, as older, proprietary hardware often lacks standardized communication capabilities.
  • Resolving these deep-rooted interoperability barriers requires highly specialized middleware, which inevitably extends implementation timelines and complicates the comprehensive digital modernization of aging commercial real estate portfolios.

What will be the Size of the Building Automation Software Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Building Automation Software Market Segmented?

The building automation software industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Product
    • BMS software
    • Standalone automation software
  • End-user
    • Commercial
    • Industrial
    • Others
  • Deployment
    • On-premises
    • Cloud-based
    • Hybrid
  • Geography
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • North America
      • US
      • Canada
      • Mexico
    • South America
      • Brazil
      • Argentina
      • Chile
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Turkey
      • Israel

By Product Insights

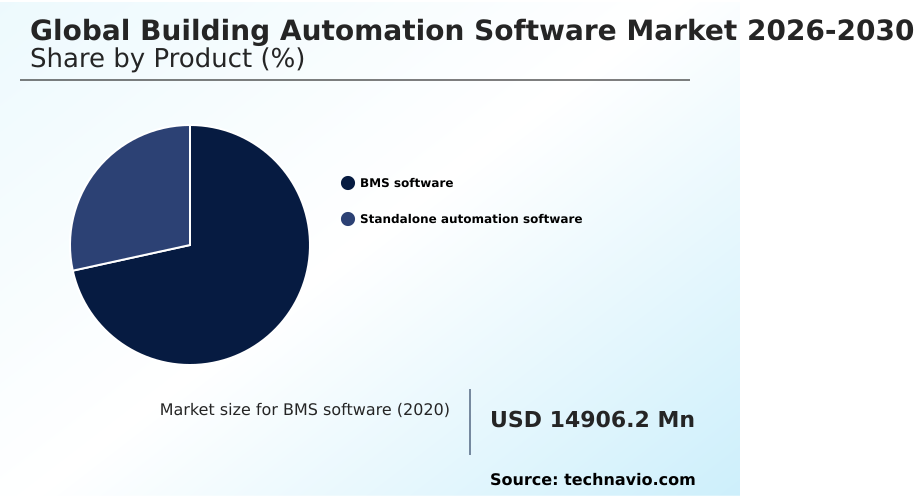
The bms software segment is estimated to witness significant growth during the forecast period.

The BMS software segment serves as the foundational architecture for modern facilities, centralizing disparate domains into a unified interface. Organizations deploy platforms to aggregate data from occupancy tracking systems and sub-metering analytics, establishing oversight of utility consumption.

This integration eliminates isolated silos across mechanical networks and life safety protocols. Facility operators leverage predictive maintenance algorithms and automated fault detection to pinpoint degradation early, reducing system downtime by 22% in optimized infrastructures.

Incorporating predictive HVAC control and dynamic boiler control ensures conditions adapt automatically to utilization patterns. Facilities utilizing dynamic space allocation achieve a 15% improvement in energy efficiency compared to traditional manual configurations.

This visibility drives long-term energy operational self-sufficiency while maintaining strict regulatory compliance.
Get Free Sample

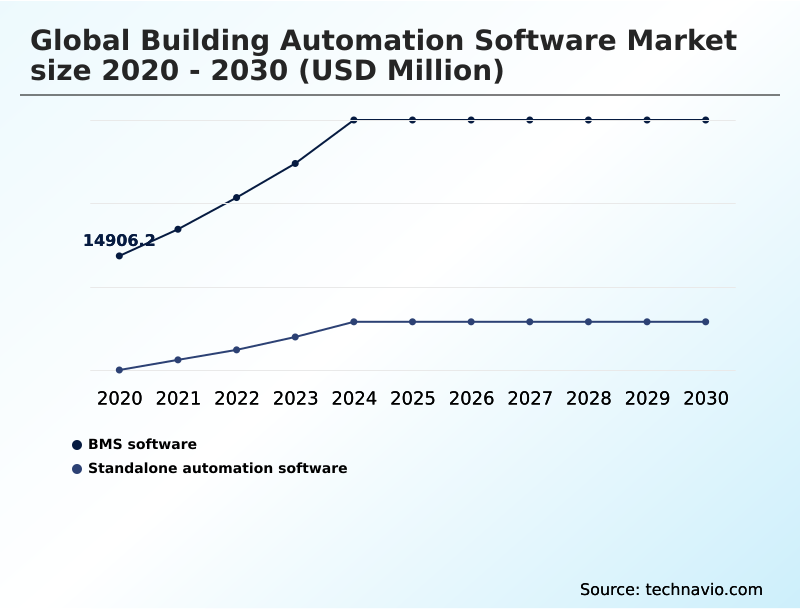
The BMS software segment was valued at USD 25.61 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

APAC is estimated to contribute 41.8% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
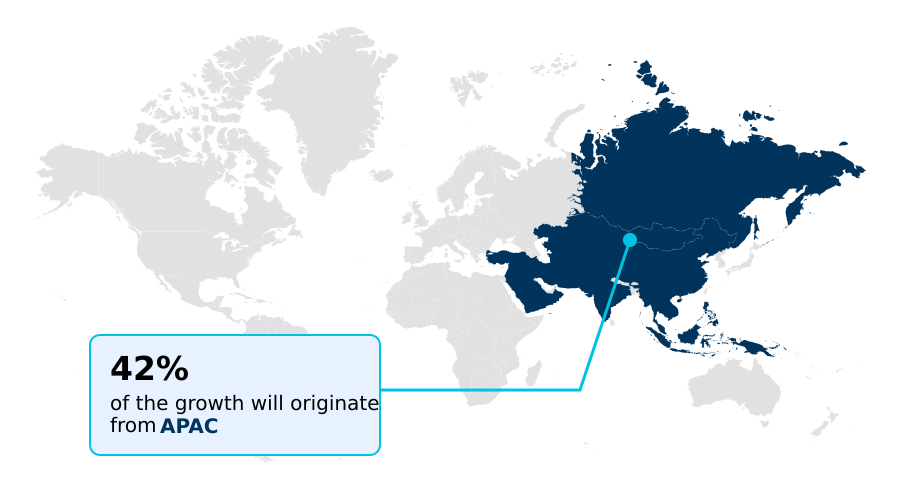
See How Building Automation Software Market Demand is Rising in APAC Get Free Sample

The geographic distribution of Building Automation Software highlights distinct regional priorities and technological maturities in addressing commercial facility management. The market dynamics vary significantly, as property developers adapt strategies to meet localized regulatory pressures.

In North America, the proactive integration of spatial utilization planning and HVAC optimization yields a 20% higher operational efficiency rate compared to legacy systems prevalent in emerging economies.

The region emphasis on indoor comfort levels and energy procurement optimization drives extensive software adoption across massive commercial portfolios.

Conversely, APAC demonstrates a rapid 30% acceleration in deploying unified smart community networks, spurred by aggressive urbanization and the need for disaster management resilience.

Furthermore, the European market focuses intensely on decentralized integration, where the utilization of distributed energy resources and solar tracking control enhances carbon compliance by 25%.

These distinct adoptions emphasize how thermal load balancing and automated oversight are critical for navigating differing regulatory environments.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • Modern commercial real estate relies heavily on advanced digital infrastructure to streamline operations and ensure rigorous environmental compliance. Facility managers increasingly deploy predictive maintenance for HVAC systems, which allows them to identify mechanical anomalies before catastrophic failures occur. This proactive approach significantly extends asset longevity and optimizes equipment performance across sprawling corporate campuses.
  • Transitioning away from localized hardware, organizations are heavily investing in cloud-based building energy management to gain remote oversight and aggregate data from diverse geographical locations. This shift enhances portfolio-wide strategic planning and enables seamless regulatory reporting.
  • The integration of automated fault detection and diagnostics ensures that minute inefficiencies within complex mechanical networks are instantly flagged, empowering maintenance teams to resolve issues rapidly. By utilizing digital twin technology for buildings, architectural engineers can create sophisticated virtual models to simulate stress scenarios, leading to structural optimizations that are 20% more accurate than traditional forecasting methods.
  • This capability drastically reduces the risks associated with capital-intensive retrofitting projects. Furthermore, the incorporation of IoT enabled indoor air quality tracking ensures that workplace environments remain healthy and compliant with stringent corporate well-being standards.
  • Facilities utilizing these comprehensive digital ecosystems often experience a 15% improvement in overall supply chain and maintenance efficiency compared to those relying on fragmented, legacy control mechanisms, highlighting the transformative impact of centralized automation.
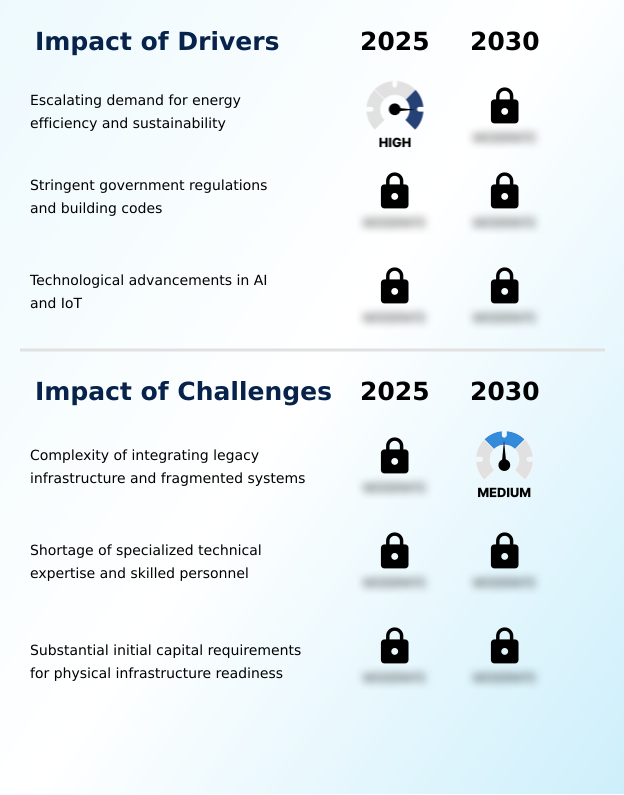
What are the key market drivers leading to the rise in the adoption of Building Automation Software Industry?

  • The escalating demand for energy efficiency and sustainable infrastructure acts as a primary catalyst accelerating market expansion.

  • The urgent imperative to achieve precise greenhouse gas reduction and secure premium green building certifications is heavily accelerating software adoption across commercial real estate.
  • Global regulatory bodies are enforcing strict environmental compliance, compelling property developers to deploy platforms that monitor carbon emission reporting and optimize building energy management. This regulatory pressure forces facilities to transition toward automated environmental control, eliminating manual inefficiencies.
  • Consequently, the deployment of intelligent workplace environments has lowered overarching energy use by 22% compared to traditional mechanical operations.
  • By leveraging real-time data visibility and comprehensive indoor air quality monitoring, maintenance teams execute precise energy waste identification, significantly improving resource allocation.
  • This data-driven approach has enhanced systemic forecast accuracy by 18%, as precise energy performance metrics prove that sophisticated digital oversight is indispensable.

What are the market trends shaping the Building Automation Software Industry?

  • The transition toward cloud-based and software-as-a-service deployment models represents a prominent market trend. This shift enables organizations to achieve unprecedented operational scalability without substantial local hardware investments.

  • The rapid migration toward cloud-native building management and open-protocol software platforms is fundamentally transforming infrastructure oversight. Organizations are aggressively adopting subscription-based software models to bypass the prohibitive upfront costs associated with legacy hardware installations. This structural shift is driven by the necessity for remote operational visibility, enabling facility managers to execute multi-site portfolio management from a centralized interface.
  • By utilizing digital twin simulation, engineers rigorously test optimization strategies in a virtual environment, which has improved predictive forecast accuracy by 18%. Furthermore, integrating edge computing capabilities alongside seamless API integration allows for instantaneous localized data processing. To protect these expansive digital networks, companies embed zero-trust architectures and robust cybersecurity frameworks, thereby reducing critical data vulnerabilities by 35%.
  • This centralized performance dashboards integration ensures continuous operational agility.

What challenges does the Building Automation Software Industry face during its growth?

  • The complexity associated with integrating legacy infrastructure and fragmented operational systems presents a formidable barrier to seamless digital modernization.

  • The inherent complexity of legacy infrastructure retrofitting presents a formidable structural limitation for widespread digital modernization. Aging commercial facilities typically operate on proprietary, isolated networks that actively resist seamless mechanical subsystem synchronization. Because integrating modern IoT sensor networks with outdated hardware requires highly specialized middleware, the deployment of comprehensive hybrid automation architectures is often delayed.
  • This deep-rooted fragmentation forces integrators to undertake extensive custom coding to bridge communication gaps between new platforms and legacy physical security mechanisms. Consequently, facilities struggling with interoperability issues experience a 25% longer implementation timeline compared to new construction projects.
  • Overcoming these technical barriers requires substantial engineering resources for smart building integration, restricting the immediate realization of mobile-enabled facility management and remote facility monitoring capabilities.

Exclusive Technavio Analysis on Customer Landscape

The building automation software market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the building automation software market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
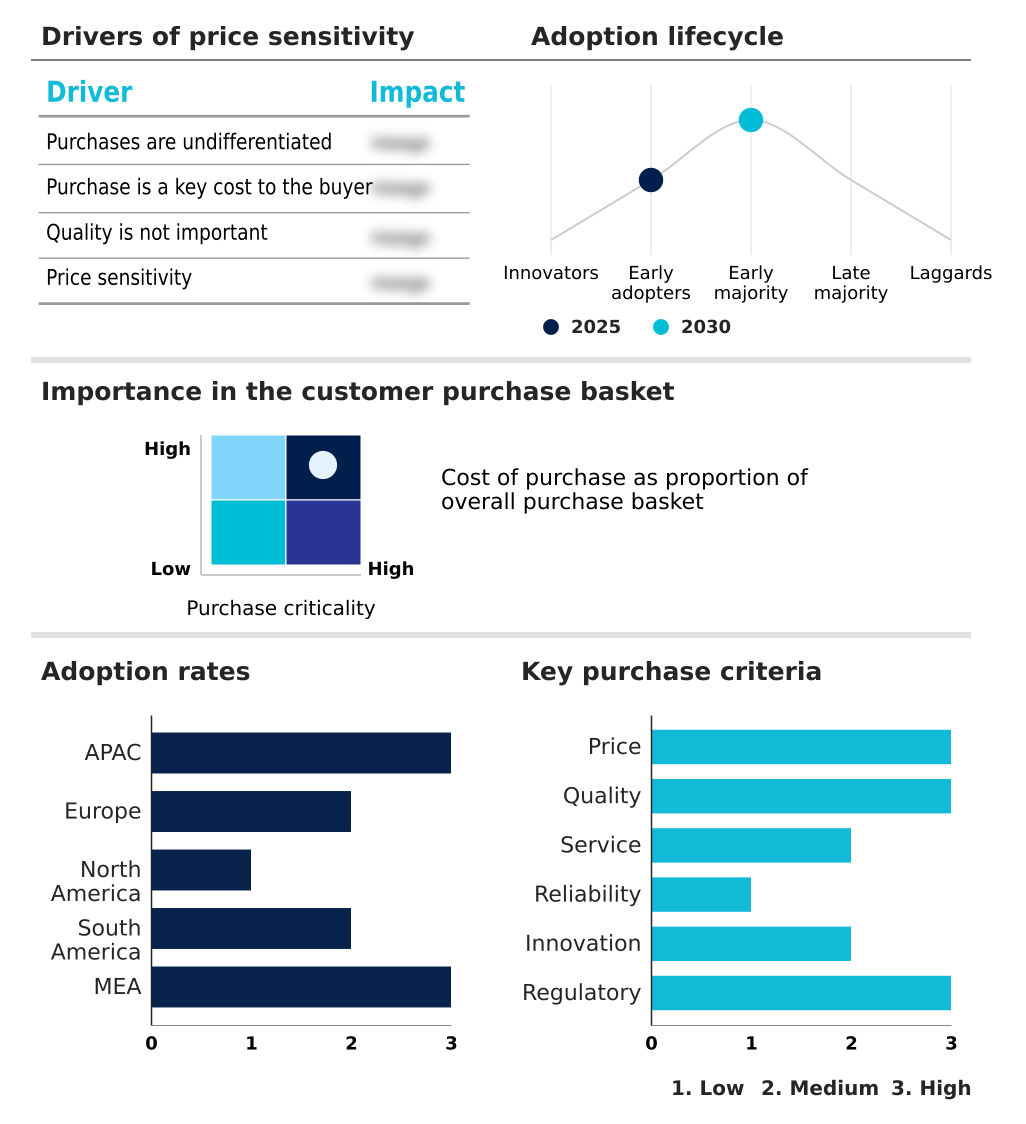
Customer Landscape of Building Automation Software Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, building automation software market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

75F - Advanced software platforms deliver unified facility oversight, enabling autonomous environmental control, continuous performance monitoring, and proactive maintenance scheduling to optimize energy efficiency across diverse commercial infrastructures.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • 75F
  • ABB Ltd.
  • Azbil Corp.
  • Beckhoff Automation GmbH
  • BrainBox AI
  • Carrier Global Corp.
  • Computrols Inc.
  • CopperTree Analytics Inc.
  • Delta Controls Inc.
  • Distech Controls Inc.
  • Facilio Inc.
  • GridPoint Inc.
  • Honeywell International Inc.
  • ICONICS Inc.
  • Johnson Controls International
  • KMC Controls Inc.
  • KODE Labs Inc.
  • Reliable Controls Corp.
  • Schneider Electric SE
  • Siemens AG
  • Spacewell International NV
  • Tridium Inc.
  • WAGO GmbH and Co. KG

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Building automation software market

  • In the Application Software industry, the transition toward scalable cloud-based delivery models has lowered initial IT infrastructure costs by up to 30%, directly accelerating the deployment of centralized Building Automation Software across multi-site commercial portfolios.
  • Stringent data privacy regulations like the General Data Protection Regulation mandate robust encryption standards for enterprise automation platforms, compelling facility managers to adopt Building Automation Software equipped with zero-trust architectures to secure sensitive occupant behavior data.
  • The rapid integration of AI infrastructure and workflow interoperability standards has improved cross-platform data synchronization by 25%, significantly enhancing the predictive diagnostic capabilities of modern Building Automation Software.
  • Rising environmental compliance mandates across global regulatory bodies require comprehensive carbon accounting tools within corporate applications, driving a 40% increase in demand for Building Automation Software featuring verifiable energy performance tracking metrics.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Building Automation Software Market insights. See full methodology.

Market Scope
Page number 299
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 16.2%
Market growth 2026-2030 USD 45836.4 million
Market structure Fragmented
YoY growth 2025-2026(%) 16.0%
Key countries China, Japan, India, South Korea, Australia, Indonesia, Germany, UK, France, Italy, Spain, The Netherlands, US, Canada, Mexico, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Turkey and Israel
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Building Automation Software landscape is rapidly evolving to address the complex operational demands of modern commercial infrastructure. Driven by stringent environmental mandates, facility managers are prioritizing advanced technological integration to ensure continuous regulatory compliance and structural efficiency.
  • The shift toward cloud-native software and centralized data aggregation allows executive boards to refine their operational budgeting and product strategy with unprecedented precision. By leveraging predictive maintenance algorithms, organizations can accurately forecast equipment lifecycles and significantly reduce unplanned capital expenditures.
  • Companies deploying automated fault detection alongside robust sub-metering analytics have achieved a 30% reduction in unexpected mechanical downtime compared to those operating with isolated legacy systems. Furthermore, the implementation of occupancy tracking systems directly informs dynamic resource allocation, minimizing energy consumption in underutilized zones.
  • This strategic adoption of life safety protocols and intelligent oversight mechanisms ensures that sprawling real estate portfolios maintain peak operational resilience. Consequently, the reliance on sophisticated digital platforms remains a fundamental priority for organizations aiming to maximize asset valuation while consistently meeting aggressive sustainability targets.

What are the Key Data Covered in this Building Automation Software Market Research and Growth Report?

  • What is the expected growth of the Building Automation Software Market between 2026 and 2030?

    • USD 45.84 billion, at a CAGR of 16.2%

  • What segmentation does the market report cover?

    • The report is segmented by Product (BMS software, and Standalone automation software), End-user (Commercial, Industrial, and Others), Deployment (On-premises, Cloud-based, and Hybrid) and Geography (APAC, Europe, North America, South America, Middle East and Africa)

  • Which regions are analyzed in the report?

    • APAC, Europe, North America, South America and Middle East and Africa

  • What are the key growth drivers and market challenges?

    • Escalating demand for energy efficiency and sustainability, Complexity of integrating legacy infrastructure and fragmented systems

  • Who are the major players in the Building Automation Software Market?

    • 75F, ABB Ltd., Azbil Corp., Beckhoff Automation GmbH, BrainBox AI, Carrier Global Corp., Computrols Inc., CopperTree Analytics Inc., Delta Controls Inc., Distech Controls Inc., Facilio Inc., GridPoint Inc., Honeywell International Inc., ICONICS Inc., Johnson Controls International, KMC Controls Inc., KODE Labs Inc., Reliable Controls Corp., Schneider Electric SE, Siemens AG, Spacewell International NV, Tridium Inc. and WAGO GmbH and Co. KG

Market Research Insights

  • Building Automation Software acts as the operational core of modern infrastructure, transforming fragmented subsystems into intelligent environments. Prioritizing real-time data visibility allows facility managers to continuously monitor performance and streamline energy procurement. Organizations adopting subscription-based software models benefit from seamless scalability, avoiding heavy capital expenditures.
  • This modernization drives operational enhancements, with intelligent workplace environments reporting a 25% decrease in unexpected equipment failures compared to traditional setups. Furthermore, integrating robust cybersecurity frameworks reduces data breach vulnerabilities by 40%, safeguarding critical networks. Consequently, comprehensive energy waste identification enables commercial portfolios to achieve a 15% reduction in overarching utility costs, ensuring strict alignment with evolving environmental compliance targets.

We can help! Our analysts can customize this building automation software market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Product
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Deployment
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Building Automation Software Market 2020 - 2024

Historic Market Size - Data Table on Global Building Automation Software Market 2020 - 2024 ($ million)

5.2 Product segment analysis 2020 - 2024

Historic Market Size - Product Segment 2020 - 2024 ($ million)

5.3 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.4 Deployment segment analysis 2020 - 2024

Historic Market Size - Deployment Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global building automation software market

6.2 Impact of geopolitical conflicts on global building automation software market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Product

8.1 Market segments

Chart on Product - Market share 2025-2030 (%)
Data Table on Product - Market share 2025-2030 (%)

8.2 Comparison by Product

Chart on Comparison by Product
Data Table on Comparison by Product

8.3 BMS software - Market size and forecast 2025-2030

Chart on BMS software - Market size and forecast 2025-2030 ($ million)
Data Table on BMS software - Market size and forecast 2025-2030 ($ million)
Chart on BMS software - Year-over-year growth 2025-2030 (%)
Data Table on BMS software - Year-over-year growth 2025-2030 (%)

8.4 Standalone automation software - Market size and forecast 2025-2030

Chart on Standalone automation software - Market size and forecast 2025-2030 ($ million)
Data Table on Standalone automation software - Market size and forecast 2025-2030 ($ million)
Chart on Standalone automation software - Year-over-year growth 2025-2030 (%)
Data Table on Standalone automation software - Year-over-year growth 2025-2030 (%)

8.5 Market opportunity by Product

Market opportunity by Product ($ million)
Data Table on Market opportunity by Product ($ million)

9. Market Segmentation by End-user

9.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

9.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

9.3 Commercial - Market size and forecast 2025-2030

Chart on Commercial - Market size and forecast 2025-2030 ($ million)
Data Table on Commercial - Market size and forecast 2025-2030 ($ million)
Chart on Commercial - Year-over-year growth 2025-2030 (%)
Data Table on Commercial - Year-over-year growth 2025-2030 (%)

9.4 Industrial - Market size and forecast 2025-2030

Chart on Industrial - Market size and forecast 2025-2030 ($ million)
Data Table on Industrial - Market size and forecast 2025-2030 ($ million)
Chart on Industrial - Year-over-year growth 2025-2030 (%)
Data Table on Industrial - Year-over-year growth 2025-2030 (%)

9.5 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

9.6 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

10. Market Segmentation by Deployment

10.1 Market segments

Chart on Deployment - Market share 2025-2030 (%)
Data Table on Deployment - Market share 2025-2030 (%)

10.2 Comparison by Deployment

Chart on Comparison by Deployment
Data Table on Comparison by Deployment

10.3 On-premises - Market size and forecast 2025-2030

Chart on On-premises - Market size and forecast 2025-2030 ($ million)
Data Table on On-premises - Market size and forecast 2025-2030 ($ million)
Chart on On-premises - Year-over-year growth 2025-2030 (%)
Data Table on On-premises - Year-over-year growth 2025-2030 (%)

10.4 Cloud-based - Market size and forecast 2025-2030

Chart on Cloud-based - Market size and forecast 2025-2030 ($ million)
Data Table on Cloud-based - Market size and forecast 2025-2030 ($ million)
Chart on Cloud-based - Year-over-year growth 2025-2030 (%)
Data Table on Cloud-based - Year-over-year growth 2025-2030 (%)

10.5 Hybrid - Market size and forecast 2025-2030

Chart on Hybrid - Market size and forecast 2025-2030 ($ million)
Data Table on Hybrid - Market size and forecast 2025-2030 ($ million)
Chart on Hybrid - Year-over-year growth 2025-2030 (%)
Data Table on Hybrid - Year-over-year growth 2025-2030 (%)

10.6 Market opportunity by Deployment

Market opportunity by Deployment ($ million)
Data Table on Market opportunity by Deployment ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.3.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.3.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.3.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.3.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.3.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.3.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.5.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.5.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.5.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.6 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.7 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.7.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.7.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.7.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.7.4 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.7.5 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Escalating demand for energy efficiency and sustainability
Stringent government regulations and building codes
Technological advancements in AI and IoT

13.2 Market challenges

Complexity of integrating legacy infrastructure and fragmented systems
Shortage of specialized technical expertise and skilled personnel
Substantial initial capital requirements for physical infrastructure readiness

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Shift toward cloud-based and software-as-a-service deployment models
Rising emphasis on cybersecurity and data privacy protocols
Integration of digital twin technology for predictive simulation

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 75F

75F - Overview
75F - Product / Service
75F - Key offerings
SWOT

15.5 ABB Ltd.

ABB Ltd. - Overview
ABB Ltd. - Business segments
ABB Ltd. - Key news
ABB Ltd. - Key offerings
ABB Ltd. - Segment focus
SWOT

15.6 Azbil Corp.

Azbil Corp. - Overview
Azbil Corp. - Business segments
Azbil Corp. - Key offerings
Azbil Corp. - Segment focus
SWOT

15.7 Beckhoff Automation GmbH

Beckhoff Automation GmbH - Overview
Beckhoff Automation GmbH - Product / Service
Beckhoff Automation GmbH - Key offerings
SWOT

15.8 BrainBox AI

BrainBox AI - Overview
BrainBox AI - Product / Service
BrainBox AI - Key offerings
SWOT

15.9 Carrier Global Corp.

Carrier Global Corp. - Overview
Carrier Global Corp. - Business segments
Carrier Global Corp. - Key news
Carrier Global Corp. - Key offerings
Carrier Global Corp. - Segment focus
SWOT

15.10 GridPoint Inc.

GridPoint Inc. - Overview
GridPoint Inc. - Product / Service
GridPoint Inc. - Key offerings
SWOT

15.11 Honeywell International Inc.

Honeywell International Inc. - Overview
Honeywell International Inc. - Business segments
Honeywell International Inc. - Key news
Honeywell International Inc. - Key offerings
Honeywell International Inc. - Segment focus
SWOT

15.12 ICONICS Inc.

ICONICS Inc. - Overview
ICONICS Inc. - Product / Service
ICONICS Inc. - Key offerings
SWOT

15.13 Johnson Controls International

Johnson Controls International - Overview
Johnson Controls International - Business segments
Johnson Controls International - Key news
Johnson Controls International - Key offerings
Johnson Controls International - Segment focus
SWOT

15.14 KODE Labs Inc.

KODE Labs Inc. - Overview
KODE Labs Inc. - Product / Service
KODE Labs Inc. - Key offerings
SWOT

15.15 Schneider Electric SE

Schneider Electric SE - Overview
Schneider Electric SE - Business segments
Schneider Electric SE - Key news
Schneider Electric SE - Key offerings
Schneider Electric SE - Segment focus
SWOT

15.16 Siemens AG

Siemens AG - Overview
Siemens AG - Business segments
Siemens AG - Key news
Siemens AG - Key offerings
Siemens AG - Segment focus
SWOT

15.17 Spacewell International NV

Spacewell International NV - Overview
Spacewell International NV - Product / Service
Spacewell International NV - Key offerings
SWOT

15.18 WAGO GmbH and Co. KG

WAGO GmbH and Co. KG - Overview
WAGO GmbH and Co. KG - Product / Service
WAGO GmbH and Co. KG - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Building Automation Software market growth will increase by USD 45836.4 million during 2026-2030.

The Building Automation Software market is expected to grow at a CAGR of 16.2% during 2026-2030.

Building Automation Software market is segmented by Product (BMS software, Standalone automation software) End-user (Commercial, Industrial, Others) Deployment (On-premises, Cloud-based, Hybrid)

75F, ABB Ltd., Azbil Corp., Beckhoff Automation GmbH, BrainBox AI, Carrier Global Corp., Computrols Inc., CopperTree Analytics Inc., Delta Controls Inc., Distech Controls Inc., Facilio Inc., GridPoint Inc., Honeywell International Inc., ICONICS Inc., Johnson Controls International, KMC Controls Inc., KODE Labs Inc., Reliable Controls Corp., Schneider Electric SE, Siemens AG, Spacewell International NV, Tridium Inc., WAGO GmbH and Co. KG are a few of the key vendors in the Building Automation Software market.

APAC will register the highest growth rate of 41.8% among the other regions. Therefore, the Building Automation Software market in APAC is expected to garner significant business opportunities for the vendors during the forecast period.

China, Japan, India, South Korea, Australia, Indonesia, Germany, UK, France, Italy, Spain, The Netherlands, US, Canada, Mexico, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Turkey, Israel

  • Escalating demand for energy efficiency and sustainability is the driving factor this market.

The Building Automation Software market vendors should focus on grabbing business opportunities from the Product segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
