Cancer Registry Software Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, India, and Japan), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and Turkey), Rest of World (ROW)

Cancer Registry Software Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, India, and Japan), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and Turkey), Rest of World (ROW)

Published: Oct 2026 300 Pages SKU: IRTNTR40838

Market Overview at a Glance

$122.08 Mn
Market Opportunity
12.8%
CAGR 2025 - 2030
49.7%
North America Growth
$35.15 Mn
Government and third party segment 2024

Cancer Registry Software Market Size 2026-2030

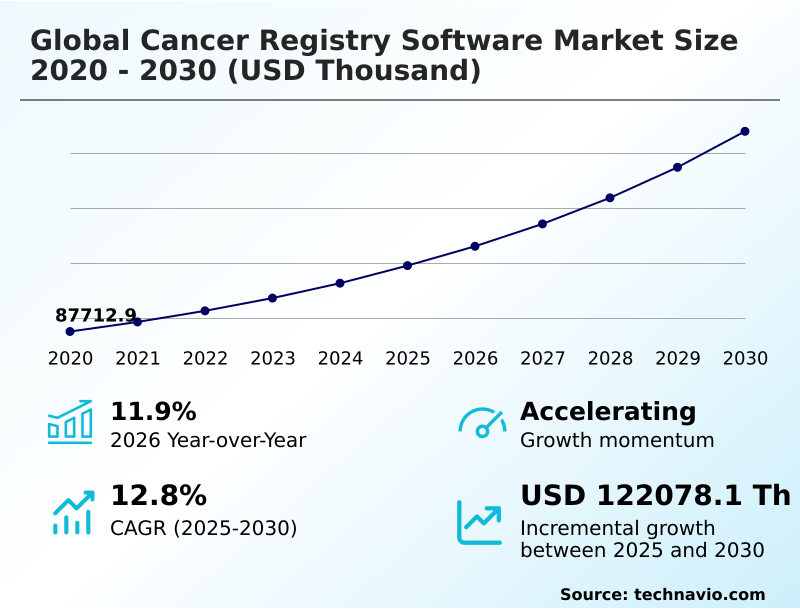
The cancer registry software market size is valued to increase by USD 122.08 million, at a CAGR of 12.8% from 2025 to 2030. Rising cancer prevalence and requirement for evidence-based public health policy will drive the cancer registry software market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 49.7% growth during the forecast period.
  • By End-user - Government and third party segment was valued at USD 35.15 million in 2024
  • By Type - Stand-alone software segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities:
  • Market Future Opportunities: USD 122.08 million
  • CAGR from 2025 to 2030 : 12.8%

Market Summary

  • The Cancer Registry Software Market relies on sophisticated digital platforms to aggregate, validate, and analyze longitudinal oncology data across diverse healthcare ecosystems. Transitioning from manual transcription to automated extraction models allows certified tumor registrars to process unstructured pathology narratives with exceptional precision.
  • In clinical operations, deploying artificial intelligence for disease classification coding has reduced administrative backlogs by 40%, enabling faster reporting and optimizing total cost of care. The escalating incidence of complex malignancies acts as a primary catalyst, compelling health systems to adopt scalable software that seamlessly tracks biomarker status and longitudinal patient outcomes.
  • Conversely, disparate electronic health record formats present a structural challenge, as the lack of universal semantic interoperability standards forces clinical data abstractors to perform labor-intensive manual reconciliation. Overcoming these integration barriers is crucial for establishing real-time public health surveillance and accelerating precision medicine trials. Ultimately, modern software architectures remain fundamental for translating fragmented clinical histories into actionable, evidence-based treatment strategies.

What will be the Size of the Cancer Registry Software Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Cancer Registry Software Market Segmented?

The cancer registry software industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD thousand" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • End-user
    • Government and third party
    • PBM companies
    • Hospitals and medical practice
    • Private payers
    • Research institutes
  • Type
    • Stand-alone software
    • Integrated software
  • Deployment
    • On-premises
    • Cloud-based
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • Asia
      • China
      • India
      • Japan
      • South Korea
      • Indonesia
      • Singapore
    • Rest of World (ROW)

By End-user Insights

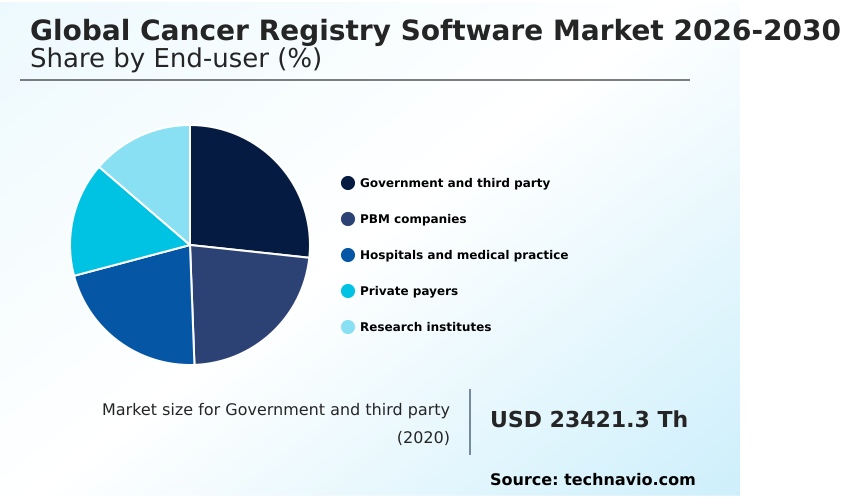
The government and third party segment is estimated to witness significant growth during the forecast period.

The government and third-party segment anchors national and regional epidemiological tracking, providing the digital infrastructure required to administer population based registries.

Public health ministries rely heavily on specialized platforms to ingest, sanitize, and aggregate massive volumes of disparate oncology data across distributed clinical networks.

By automating structured electronic laboratory reporting and digital pathology feeds, these systems eliminate surveillance backlogs while ensuring strict adherence to standardized reporting criteria.

Advanced software architectures allow public sector entities to monitor geographic disparities and optimize resource allocation for preventive healthcare interventions. Implementing automated validation protocols has improved data accuracy, resulting in a 25% increase in operational efficiency for data consolidation tasks.

This modernization equips policymakers with the granular, real-time insights necessary to manage comprehensive cancer surveillance networks and formulate evidence-based public health strategies.
Get Free Sample

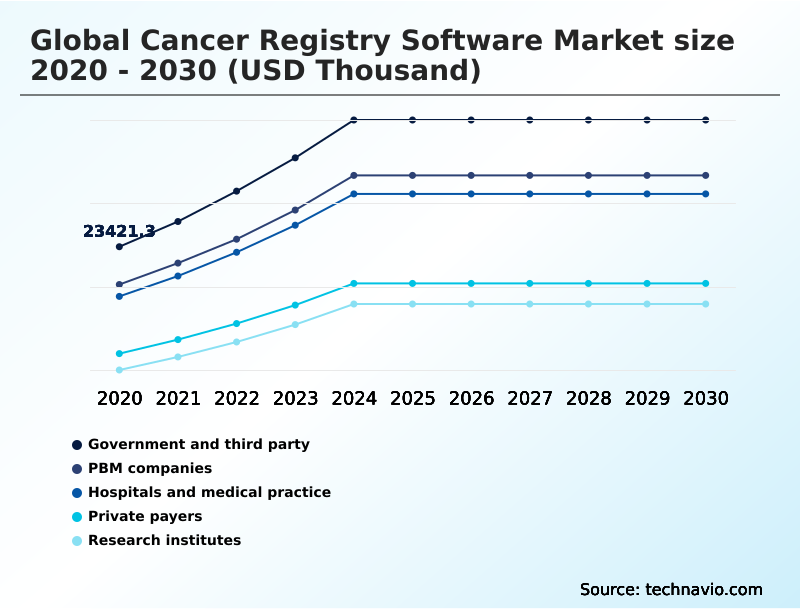
The Government and third party segment was valued at USD 35.15 million in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

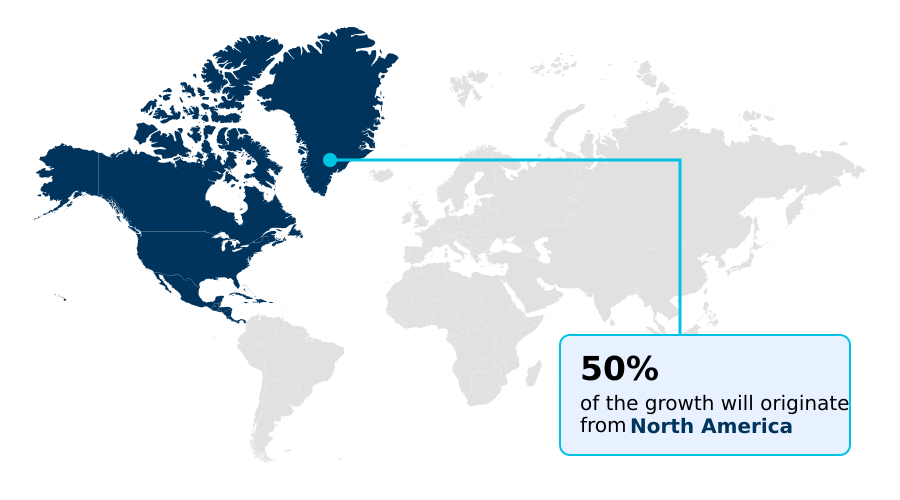
North America is estimated to contribute 49.7% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
See How Cancer Registry Software Market Demand is Rising in North America Get Free Sample

The geographic distribution of the Cancer Registry Software Market reveals stark contrasts in technological maturity and adoption frameworks.

North America maintains a sophisticated digital infrastructure where hospital based registries leverage fast healthcare interoperability resources to achieve a 35% higher automated data abstraction rate compared to European counterparts.

This advantage stems from stringent federal reporting mandates that incentivize deep integration between multi omic databases and core clinical systems.

In contrast, European oncology informatics prioritize sovereign data localization, heavily investing in data harmonization pipelines to navigate fragmented regional health jurisdictions and strict privacy regulations.

As a result of these strategic regional focuses, North American institutions experience a 20% reduction in manual surveillance backlogs, whereas European networks report a 15% improvement in cross-border clinical trial patient matching.

These divergent compliance and operational priorities shape how multinational software providers tailor cloud deployments to address regional variations in population health management.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The continuous evolution of specialized healthcare informatics demands robust technological frameworks to support comprehensive clinical surveillance and research. Modern oncology departments are increasingly transitioning away from localized legacy servers toward cloud based clinical oncology databases, a shift that improves multi-site data accessibility while strengthening enterprise disaster recovery protocols.
  • As precision medicine becomes the standard of care, the deployment of genomic data integration registry platforms allows multidisciplinary care teams to link specific molecular mutations directly to longitudinal treatment outcomes. This high-resolution data fusion enables more accurate patient matching for clinical trials and refines the development of targeted therapies.
  • Organizations utilizing automated tumor registry abstraction software frequently realize a 45% acceleration in case processing workflows compared to those relying on traditional manual data entry models. This operational advantage drastically reduces compliance reporting backlogs and reallocates certified tumor registrars to higher-value quality assurance tasks.
  • Furthermore, the integration of natural language processing oncology analytics empowers health systems to extract nuanced diagnostic variables from unstructured physician notes and pathology reports with unprecedented accuracy. By establishing a unified data ecosystem, public health agencies leverage population health management cancer tracking to identify regional disease clusters, evaluate screening efficacies, and distribute preventative resources more efficiently.
  • Ultimately, the modernization of these critical surveillance systems ensures that institutional stakeholders can maintain rigorous regulatory compliance while simultaneously driving forward the next generation of evidence-based oncological research.
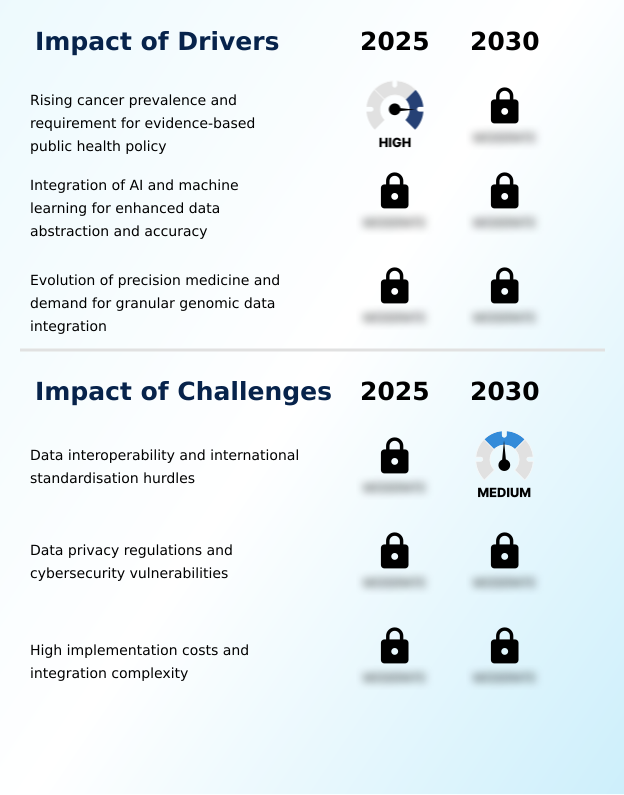
What are the key market drivers leading to the rise in the adoption of Cancer Registry Software Industry?

  • The escalating global prevalence of oncological diseases, coupled with an urgent requirement for evidence-based public health policy, serves as the primary catalyst propelling market expansion.

  • The escalating demand for granular real-world evidence is a primary driver compelling health systems to modernize their oncology data abstraction processes.
  • As precision medicine protocols become standard practice, the integration of clinical registries with advanced genomic profiling platforms is essential to accurately measure targeted therapy responses.
  • This necessity drives the adoption of sophisticated software capable of handling complex disease classification coding, resulting in a 30% improvement in clinical pathway adherence tracking.
  • Hospitals adopt these platforms to support value based oncology care frameworks, leveraging precise patient outcome data to secure a 15% higher reimbursement approval rate from commercial payers.
  • By linking molecular diagnostics with longitudinal treatment data, these systems empower robust cancer epidemiology tracking, enabling public health organizations to continuously optimize preventive screening strategies and clinical resource distribution.

What are the market trends shaping the Cancer Registry Software Industry?

  • The universal transition toward cloud-native architectures and software-as-a-service delivery models represents a defining shift in the industry. This evolution enables scalable data management and facilitates real-time collaboration across complex healthcare networks.

  • A fundamental trend reshaping the Cancer Registry Software Market is the aggressive transition from localized servers to scalable cloud native architectures. This architectural migration is driven by the explosive growth in diagnostic data and the urgent need to facilitate multi-center research collaborations.
  • By implementing federated data sharing frameworks, research consortiums have increased data processing speeds by 40% while maintaining strict localized patient privacy controls. This shift directly impacts business operations by equipping clinical data abstractors with automated casefinding algorithms, which reduces manual identification errors by over 20%. Consequently, healthcare enterprises can conduct highly precise longitudinal oncology analytics without expanding administrative headcounts.
  • The utilization of advanced propensity score matching algorithms further allows researchers to rapidly synthesize real-world evidence from massive datasets. These technological innovations transform passive cancer registries into dynamic intelligence platforms, accelerating both clinical trial recruitment and targeted therapeutic development.

What challenges does the Cancer Registry Software Industry face during its growth?

  • Persistent data interoperability limitations and the lack of international standardization protocols continue to impede seamless information exchange and restrain broader industry growth.

  • Severe fragmentation across clinical IT ecosystems creates profound structural challenges, primarily due to the inconsistent application of semantic interoperability standards. Because disparate electronic health record vendors utilize proprietary data models, establishing seamless health system interoperability remains an operational bottleneck for regional surveillance programs.
  • This fragmentation requires extensive manual reconciliation, increasing data curation costs by up to 25% for independent oncology practices. Additionally, stringent data privacy regulations mandate the implementation of complex pseudonymization architectures and rigorous data de identification protocols. Ensuring absolute compliance with health information portability guidelines necessitates continuous investments in sophisticated patient consent management systems.
  • These security burdens often extend software deployment timelines by 18%, significantly constraining the ability of smaller healthcare facilities to participate in large-scale, real-time epidemiological monitoring networks without substantial capital expenditure.

Exclusive Technavio Analysis on Customer Landscape

The cancer registry software market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the cancer registry software market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
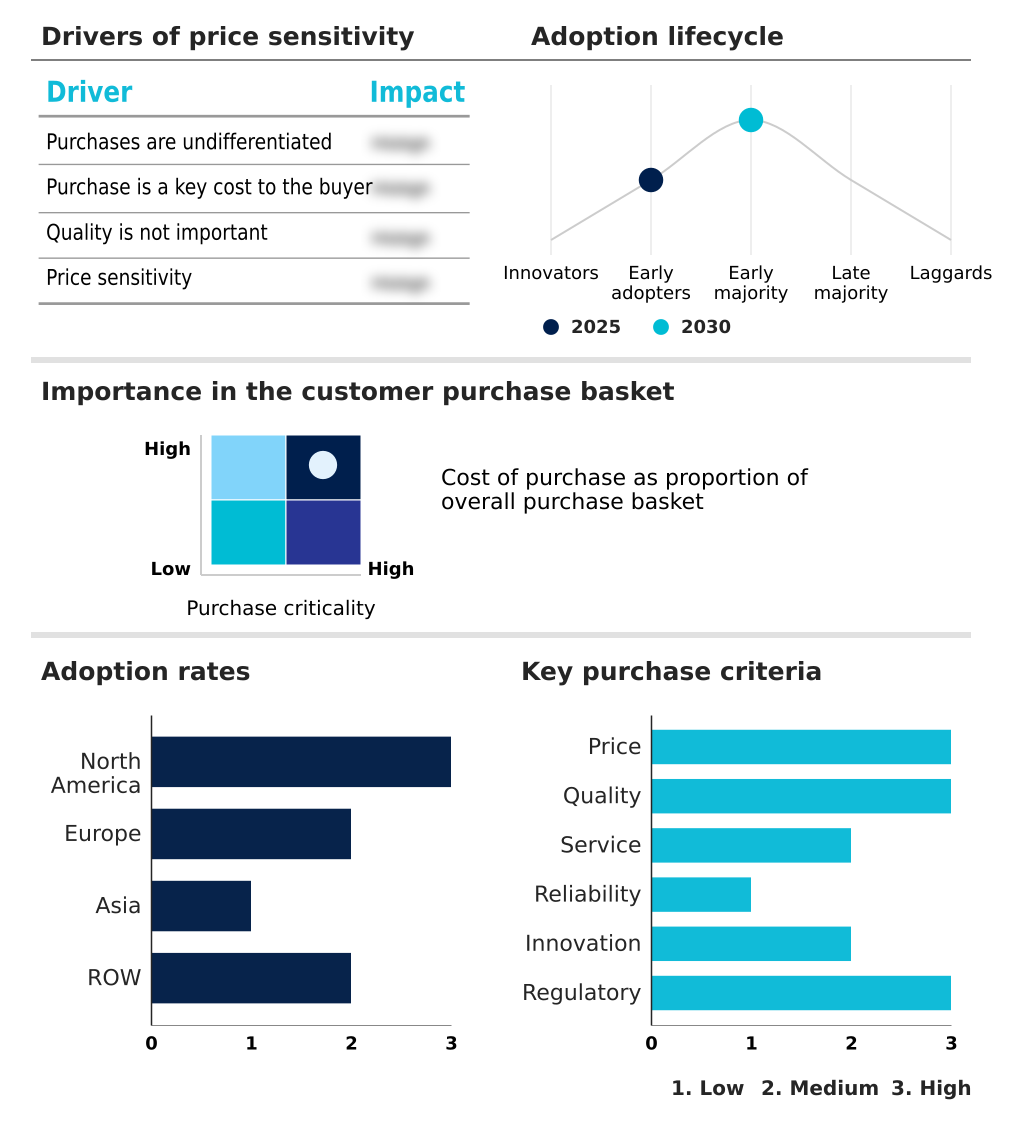
Customer Landscape of Cancer Registry Software Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, cancer registry software market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Azra AI Inc. - Advanced artificial intelligence algorithms scan pathology reports and electronic medical records to automate complex clinical staging and streamline precise cohort identification across enterprise healthcare systems.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Azra AI Inc.
  • Conduent Inc.
  • CureMD
  • Dacima Software Inc.
  • Elekta AB
  • Epic Systems Corp.
  • Flatiron Health
  • Health Catalyst Inc.
  • ImageTrend Inc.
  • Inspirata Inc.
  • IQVIA Holdings Inc.
  • McKesson Corp.
  • Merative L.P.
  • NeuralFrame Inc.
  • Oracle Corp.
  • Ordinal Data Inc.
  • RaySearch Laboratories
  • Siemens Healthineers AG
  • Skill Information S Co. Ltd.
  • Veradigm LLC

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Cancer registry software market

  • In the Health Care Technology industry, the universal transition toward cloud native architectures expanded elastic storage capacity by 40%, directly impacting Cancer Registry Software demand by enabling real-time multi-site oncology data abstraction.
  • The enforcement of the General Data Protection Regulation compelled healthcare institutions to upgrade patient consent management and pseudonymization architectures, increasing the requirement for compliant cancer surveillance networks with a 100% adherence threshold.
  • The integration of natural language processing into electronic health record workflows reduced clinical documentation processing times by 30%, pulling demand for automated casefinding algorithms within hospital based registries.
  • The shift toward value based oncology care incentivized health systems to track longitudinal medication dispensing histories, driving a 25% increase in the deployment of real world evidence generation platforms for precision medicine.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Cancer Registry Software Market insights. See full methodology.

Market Scope
Page number 300
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 12.8%
Market growth 2026-2030 USD 122078.1 thousand
Market structure Fragmented
YoY growth 2025-2026(%) 11.9%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, India, Japan, South Korea, Indonesia, Singapore, Brazil, Saudi Arabia, UAE, Turkey, Argentina, Colombia, South Africa and Israel
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The architecture of modern healthcare informatics relies extensively on robust digital frameworks to aggregate and analyze highly complex oncological data. A decisive operational shift involves the implementation of real-time clinical natural language processing, which allows boardroom executives to accelerate compliance reporting and optimize strategic resource allocation.
  • By automating complex tumor node metastasis staging directly from unstructured medical documentation, hospitals have achieved a 35% reduction in administrative processing time per patient case. Seamless electronic health record integration ensures that critical molecular pathology details are rapidly transmitted to centralized cancer surveillance networks without transcription delays.
  • These advanced platforms facilitate granular biomarker status tracking, equipping clinicians with the precise phenotypic data required to personalize therapeutic interventions. Furthermore, the embedded use of survival analysis calculators empowers administrators to evaluate clinical pathway efficacy and negotiate favorable value-based reimbursement contracts. This technological modernization transforms disparate clinical records into a cohesive, actionable intelligence asset.
  • Such structural enhancements fundamentally alter how healthcare enterprises manage longitudinal population health, solidifying data governance as a cornerstone of institutional strategy.

What are the Key Data Covered in this Cancer Registry Software Market Research and Growth Report?

  • What is the expected growth of the Cancer Registry Software Market between 2026 and 2030?

    • USD 122.08 million, at a CAGR of 12.8%

  • What segmentation does the market report cover?

    • The report is segmented by End-user (Government and third party, PBM companies, Hospitals and medical practice, Private payers, and Research institutes), Type (Stand-alone software, and Integrated software), Deployment (On-premises, and Cloud-based) and Geography (North America, Europe, Asia, Rest of World (ROW))

  • Which regions are analyzed in the report?

    • North America, Europe, Asia and Rest of World (ROW)

  • What are the key growth drivers and market challenges?

    • Rising cancer prevalence and requirement for evidence-based public health policy, Data interoperability and international standardisation hurdles

  • Who are the major players in the Cancer Registry Software Market?

    • Azra AI Inc., Conduent Inc., CureMD, Dacima Software Inc., Elekta AB, Epic Systems Corp., Flatiron Health, Health Catalyst Inc., ImageTrend Inc., Inspirata Inc., IQVIA Holdings Inc., McKesson Corp., Merative L.P., NeuralFrame Inc., Oracle Corp., Ordinal Data Inc., RaySearch Laboratories, Siemens Healthineers AG, Skill Information S Co. Ltd. and Veradigm LLC

Market Research Insights

  • The Cancer Registry Software Market operates at the intersection of regulatory compliance and advanced clinical informatics. The rapid adoption of saas delivery models allows healthcare networks to scale data infrastructure dynamically, reducing IT maintenance overhead by 25% while ensuring continuous system updates.
  • Leveraging machine learning extraction, modern platforms automatically parse unstructured pathology narratives, improving documentation accuracy by over 30% compared to traditional manual abstraction methods. These efficiency gains directly support precision oncology studies by providing researchers with high-fidelity longitudinal data.
  • Furthermore, investments in health system interoperability allow seamless integration with electronic health records, empowering predictive analytics models that have improved proactive patient cohort identification by 15%, ultimately optimizing value-based care initiatives.

We can help! Our analysts can customize this cancer registry software market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Market Segmentation by Deployment
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ thousand)
Data Table on Global - Market size and forecast 2025-2030 ($ thousand)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Cancer Registry Software Market 2020 - 2024

Historic Market Size - Data Table on Global Cancer Registry Software Market 2020 - 2024 ($ thousand)

5.2 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ thousand)

5.3 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ thousand)

5.4 Deployment segment analysis 2020 - 2024

Historic Market Size - Deployment Segment 2020 - 2024 ($ thousand)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ thousand)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ thousand)

6. Qualitative Analysis

6.1 Impact of AI on Global Cancer Registry Software Market

6.2 Impact of Geopolitical Conflicts on Global Cancer Registry Software Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by End-user

8.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

8.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

8.3 Government and third party - Market size and forecast 2025-2030

Chart on Government and third party - Market size and forecast 2025-2030 ($ thousand)
Data Table on Government and third party - Market size and forecast 2025-2030 ($ thousand)
Chart on Government and third party - Year-over-year growth 2025-2030 (%)
Data Table on Government and third party - Year-over-year growth 2025-2030 (%)

8.4 PBM companies - Market size and forecast 2025-2030

Chart on PBM companies - Market size and forecast 2025-2030 ($ thousand)
Data Table on PBM companies - Market size and forecast 2025-2030 ($ thousand)
Chart on PBM companies - Year-over-year growth 2025-2030 (%)
Data Table on PBM companies - Year-over-year growth 2025-2030 (%)

8.5 Hospitals and medical practice - Market size and forecast 2025-2030

Chart on Hospitals and medical practice - Market size and forecast 2025-2030 ($ thousand)
Data Table on Hospitals and medical practice - Market size and forecast 2025-2030 ($ thousand)
Chart on Hospitals and medical practice - Year-over-year growth 2025-2030 (%)
Data Table on Hospitals and medical practice - Year-over-year growth 2025-2030 (%)

8.6 Private payers - Market size and forecast 2025-2030

Chart on Private payers - Market size and forecast 2025-2030 ($ thousand)
Data Table on Private payers - Market size and forecast 2025-2030 ($ thousand)
Chart on Private payers - Year-over-year growth 2025-2030 (%)
Data Table on Private payers - Year-over-year growth 2025-2030 (%)

8.7 Research institutes - Market size and forecast 2025-2030

Chart on Research institutes - Market size and forecast 2025-2030 ($ thousand)
Data Table on Research institutes - Market size and forecast 2025-2030 ($ thousand)
Chart on Research institutes - Year-over-year growth 2025-2030 (%)
Data Table on Research institutes - Year-over-year growth 2025-2030 (%)

8.8 Market opportunity by End-user

Market opportunity by End-user ($ thousand)
Data Table on Market opportunity by End-user ($ thousand)

9. Market Segmentation by Type

9.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

9.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

9.3 Stand-alone software - Market size and forecast 2025-2030

Chart on Stand-alone software - Market size and forecast 2025-2030 ($ thousand)
Data Table on Stand-alone software - Market size and forecast 2025-2030 ($ thousand)
Chart on Stand-alone software - Year-over-year growth 2025-2030 (%)
Data Table on Stand-alone software - Year-over-year growth 2025-2030 (%)

9.4 Integrated software - Market size and forecast 2025-2030

Chart on Integrated software - Market size and forecast 2025-2030 ($ thousand)
Data Table on Integrated software - Market size and forecast 2025-2030 ($ thousand)
Chart on Integrated software - Year-over-year growth 2025-2030 (%)
Data Table on Integrated software - Year-over-year growth 2025-2030 (%)

9.5 Market opportunity by Type

Market opportunity by Type ($ thousand)
Data Table on Market opportunity by Type ($ thousand)

10. Market Segmentation by Deployment

10.1 Market segments

Chart on Deployment - Market share 2025-2030 (%)
Data Table on Deployment - Market share 2025-2030 (%)

10.2 Comparison by Deployment

Chart on Comparison by Deployment
Data Table on Comparison by Deployment

10.3 On-premises - Market size and forecast 2025-2030

Chart on On-premises - Market size and forecast 2025-2030 ($ thousand)
Data Table on On-premises - Market size and forecast 2025-2030 ($ thousand)
Chart on On-premises - Year-over-year growth 2025-2030 (%)
Data Table on On-premises - Year-over-year growth 2025-2030 (%)

10.4 Cloud-based - Market size and forecast 2025-2030

Chart on Cloud-based - Market size and forecast 2025-2030 ($ thousand)
Data Table on Cloud-based - Market size and forecast 2025-2030 ($ thousand)
Chart on Cloud-based - Year-over-year growth 2025-2030 (%)
Data Table on Cloud-based - Year-over-year growth 2025-2030 (%)

10.5 Market opportunity by Deployment

Market opportunity by Deployment ($ thousand)
Data Table on Market opportunity by Deployment ($ thousand)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ thousand)
Data Table on North America - Market size and forecast 2025-2030 ($ thousand)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ thousand)
Data Table on US - Market size and forecast 2025-2030 ($ thousand)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ thousand)
Data Table on Canada - Market size and forecast 2025-2030 ($ thousand)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ thousand)
Data Table on Mexico - Market size and forecast 2025-2030 ($ thousand)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ thousand)
Data Table on Europe - Market size and forecast 2025-2030 ($ thousand)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ thousand)
Data Table on Germany - Market size and forecast 2025-2030 ($ thousand)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ thousand)
Data Table on UK - Market size and forecast 2025-2030 ($ thousand)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ thousand)
Data Table on France - Market size and forecast 2025-2030 ($ thousand)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ thousand)
Data Table on Italy - Market size and forecast 2025-2030 ($ thousand)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ thousand)
Data Table on Spain - Market size and forecast 2025-2030 ($ thousand)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ thousand)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ thousand)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 Asia - Market size and forecast 2025-2030

Chart on Asia - Market size and forecast 2025-2030 ($ thousand)
Data Table on Asia - Market size and forecast 2025-2030 ($ thousand)
Chart on Asia - Year-over-year growth 2025-2030 (%)
Data Table on Asia - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Asia
Data Table on Regional Comparison - Asia

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ thousand)
Data Table on China - Market size and forecast 2025-2030 ($ thousand)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ thousand)
Data Table on India - Market size and forecast 2025-2030 ($ thousand)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.3 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ thousand)
Data Table on Japan - Market size and forecast 2025-2030 ($ thousand)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ thousand)
Data Table on South Korea - Market size and forecast 2025-2030 ($ thousand)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ thousand)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ thousand)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.5.6 Singapore - Market size and forecast 2025-2030

Chart on Singapore - Market size and forecast 2025-2030 ($ thousand)
Data Table on Singapore - Market size and forecast 2025-2030 ($ thousand)
Chart on Singapore - Year-over-year growth 2025-2030 (%)
Data Table on Singapore - Year-over-year growth 2025-2030 (%)

12.6 Rest of World (ROW) - Market size and forecast 2025-2030

Chart on Rest of World (ROW) - Market size and forecast 2025-2030 ($ thousand)
Data Table on Rest of World (ROW) - Market size and forecast 2025-2030 ($ thousand)
Chart on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Data Table on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Rest of World (ROW)
Data Table on Regional Comparison - Rest of World (ROW)

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ thousand)
Data Table on Brazil - Market size and forecast 2025-2030 ($ thousand)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ thousand)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ thousand)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.3 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ thousand)
Data Table on UAE - Market size and forecast 2025-2030 ($ thousand)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.4 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ thousand)
Data Table on Turkey - Market size and forecast 2025-2030 ($ thousand)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.6.5 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ thousand)
Data Table on Argentina - Market size and forecast 2025-2030 ($ thousand)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.6 Colombia - Market size and forecast 2025-2030

Chart on Colombia - Market size and forecast 2025-2030 ($ thousand)
Data Table on Colombia - Market size and forecast 2025-2030 ($ thousand)
Chart on Colombia - Year-over-year growth 2025-2030 (%)
Data Table on Colombia - Year-over-year growth 2025-2030 (%)

12.6.7 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ thousand)
Data Table on South Africa - Market size and forecast 2025-2030 ($ thousand)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.8 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ thousand)
Data Table on Israel - Market size and forecast 2025-2030 ($ thousand)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7 Market opportunity by geography

Market opportunity by geography ($ thousand)
Data Tables on Market opportunity by geography ($ thousand)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Rising cancer prevalence and requirement for evidence-based public health policy
Integration of AI and machine learning for enhanced data abstraction and accuracy
Evolution of precision medicine and demand for granular genomic data integration

13.2 Market challenges

Data interoperability and international standardisation hurdles
Data privacy regulations and cybersecurity vulnerabilities
High implementation costs and integration complexity

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Universal transition toward cloud-native architectures and SaaS delivery models
Proliferation of real-world evidence and multi-source data fusion for comprehensive clinical insights
Advancement in automated data abstraction and implementation of semantic interoperability standards

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Conduent Inc.

Conduent Inc. - Overview
Conduent Inc. - Business segments
Conduent Inc. - Key offerings
Conduent Inc. - Segment focus
SWOT

15.5 CureMD

CureMD - Overview
CureMD - Product / Service
CureMD - Key offerings
SWOT

15.6 Elekta AB

Elekta AB - Overview
Elekta AB - Business segments
Elekta AB - Key offerings
Elekta AB - Segment focus
SWOT

15.7 Epic Systems Corp.

Epic Systems Corp. - Overview
Epic Systems Corp. - Product / Service
Epic Systems Corp. - Key offerings
SWOT

15.8 Flatiron Health

Flatiron Health - Overview
Flatiron Health - Product / Service
Flatiron Health - Key offerings
SWOT

15.9 Health Catalyst Inc.

Health Catalyst Inc. - Overview
Health Catalyst Inc. - Business segments
Health Catalyst Inc. - Key offerings
Health Catalyst Inc. - Segment focus
SWOT

15.10 ImageTrend Inc.

ImageTrend Inc. - Overview
ImageTrend Inc. - Product / Service
ImageTrend Inc. - Key offerings
SWOT

15.11 Inspirata Inc.

Inspirata Inc. - Overview
Inspirata Inc. - Product / Service
Inspirata Inc. - Key offerings
SWOT

15.12 IQVIA Holdings Inc.

IQVIA Holdings Inc. - Overview
IQVIA Holdings Inc. - Business segments
IQVIA Holdings Inc. - Key offerings
IQVIA Holdings Inc. - Segment focus
SWOT

15.13 McKesson Corp.

McKesson Corp. - Overview
McKesson Corp. - Business segments
McKesson Corp. - Key offerings
McKesson Corp. - Segment focus
SWOT

15.14 Merative L.P.

Merative L.P. - Overview
Merative L.P. - Product / Service
Merative L.P. - Key offerings
SWOT

15.15 Oracle Corp.

Oracle Corp. - Overview
Oracle Corp. - Business segments
Oracle Corp. - Key news
Oracle Corp. - Key offerings
Oracle Corp. - Segment focus
SWOT

15.16 RaySearch Laboratories

RaySearch Laboratories - Overview
RaySearch Laboratories - Product / Service
RaySearch Laboratories - Key offerings
SWOT

15.17 Siemens Healthineers AG

Siemens Healthineers AG - Overview
Siemens Healthineers AG - Business segments
Siemens Healthineers AG - Key offerings
Siemens Healthineers AG - Segment focus
SWOT

15.18 Veradigm LLC

Veradigm LLC - Overview
Veradigm LLC - Product / Service
Veradigm LLC - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Cancer Registry Software market growth will increase by USD 122078.1 thousand thousand during 2026-2030.

The Cancer Registry Software market is expected to grow at a CAGR of 12.8% during 2026-2030.

Cancer Registry Software market is segmented by End-user (Government and third party, PBM companies, Hospitals and medical practice, Private payers, Research institutes) Type (Stand-alone software, Integrated software) Deployment (On-premises, Cloud-based)

Azra AI Inc., Conduent Inc., CureMD, Dacima Software Inc., Elekta AB, Epic Systems Corp., Flatiron Health, Health Catalyst Inc., ImageTrend Inc., Inspirata Inc., IQVIA Holdings Inc., McKesson Corp., Merative L.P., NeuralFrame Inc., Oracle Corp., Ordinal Data Inc., RaySearch Laboratories, Siemens Healthineers AG, Skill Information S Co. Ltd., Veradigm LLC are a few of the key vendors in the Cancer Registry Software market.

North America will register the highest growth rate of 49.7% among the other regions. Therefore, the Cancer Registry Software market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, India, Japan, South Korea, Indonesia, Singapore, Brazil, Saudi Arabia, UAE, Turkey, Argentina, Colombia, South Africa, Israel

  • Rising cancer prevalence and requirement for evidence-based public health policy is the driving factor this market.

The Cancer Registry Software market vendors should focus on grabbing business opportunities from the End-user segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
