Galvanized And Coated Iron And Steel Sheets Market Analysis, Size, and Forecast 2026-2030: APAC (China, India, and Japan), Europe (Germany, Italy, and France), North America (US, Mexico, and Canada), Middle East and Africa (Turkey, Saudi Arabia, and South Africa), South America (Brazil, Argentina, and Colombia), and Rest of World (ROW)

Galvanized And Coated Iron And Steel Sheets Market Analysis, Size, and Forecast 2026-2030:
APAC (China, India, and Japan), Europe (Germany, Italy, and France), North America (US, Mexico, and Canada), Middle East and Africa (Turkey, Saudi Arabia, and South Africa), South America (Brazil, Argentina, and Colombia), and Rest of World (ROW)

Published: Oct 2026 322 Pages SKU: IRTNTR81834

Market Overview at a Glance

$43.41 B
Market Opportunity
4.6%
CAGR 2025 - 2030
62.6%
APAC Growth
$102.93 B
Zinc-coated steel segment 2024

Galvanized And Coated Iron And Steel Sheets Market Size 2026-2030

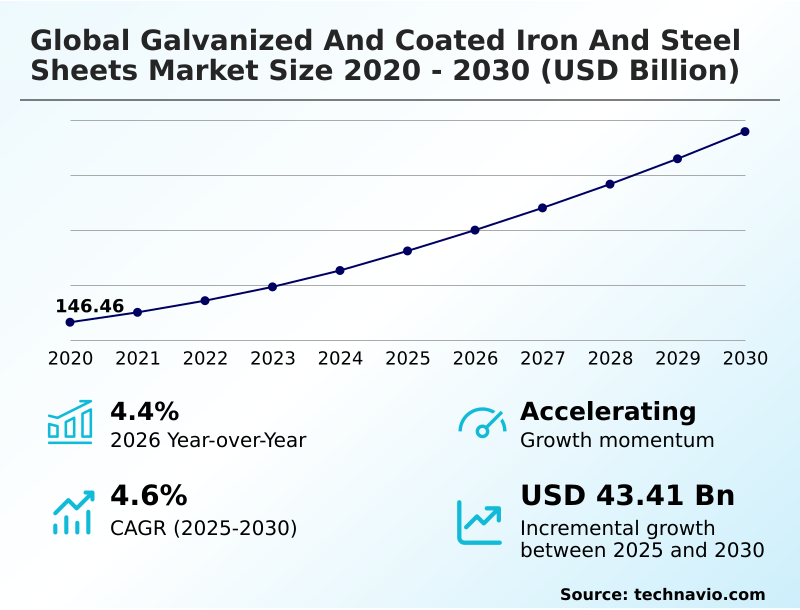
The galvanized and coated iron and steel sheets market size is valued to increase by USD 43.41 billion, at a CAGR of 4.6% from 2025 to 2030. Growth in utility-scale solar and grid modernization will drive the galvanized and coated iron and steel sheets market.

Major Market Trends & Insights

  • APAC dominated the market and accounted for a 62.6% growth during the forecast period.
  • By Type - Zinc-coated steel segment was valued at USD 102.93 billion in 2024
  • By Product - Flat sheets segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 69.33 billion
  • Market Future Opportunities: USD 43.41 billion
  • CAGR from 2025 to 2030 : 4.6%

Market Summary

  • The Galvanized And Coated Iron And Steel Sheets landscape is undergoing rapid structural transformation driven by the stringent performance demands of modern infrastructure and automotive manufacturing. Advanced metallic barrier technologies fundamentally alter how industrial components resist environmental degradation over prolonged lifespans.
  • For instance, automotive assembly plants utilizing advanced continuous coil coating systems have improved body panel corrosion resistance, reducing warranty claim costs by 22% compared to conventional untreated steel substrates. The rapid expansion of modular construction and utility-scale solar framing acts as a primary catalyst, propelling demand for materials that withstand severe outdoor weathering.
  • Conversely, extreme fluctuations in raw zinc and aluminum feedstock pricing present a formidable challenge, severely compressing profit margins for mid-tier processors without captive mining assets. Supply chain optimization strategies now focus on securing localized sourcing to mitigate these cost variations. Asset owners are aggressively pivoting toward sustainable materials that promise lifecycle longevity and recyclability.
  • The implementation of high-strength alloy coatings ensures uninterrupted production cycles across critical heavy industrial supply chains.

What will be the Size of the Galvanized And Coated Iron And Steel Sheets Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Galvanized And Coated Iron And Steel Sheets Market Segmented?

The galvanized and coated iron and steel sheets industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Type
    • Zinc-coated steel
    • Zinc-aluminum alloy-coated steel
    • Zinc-aluminum-magnesium-coated steel
    • Aluminum-coated steel
    • Others
  • Product
    • Flat sheets
    • Coils
    • Others
  • Product type
    • Unpainted metallic finish
    • Pre-painted and color-coated finish
    • Textured and embossed finish
    • Others
  • Geography
    • APAC
      • China
      • India
      • Japan
      • South Korea
      • Indonesia
      • Australia
    • Europe
      • Germany
      • Italy
      • France
      • UK
      • Spain
      • The Netherlands
    • North America
      • US
      • Mexico
      • Canada
    • Middle East and Africa
      • Turkey
      • Saudi Arabia
      • South Africa
      • UAE
      • Israel
    • South America
      • Brazil
      • Argentina
      • Colombia

By Type Insights

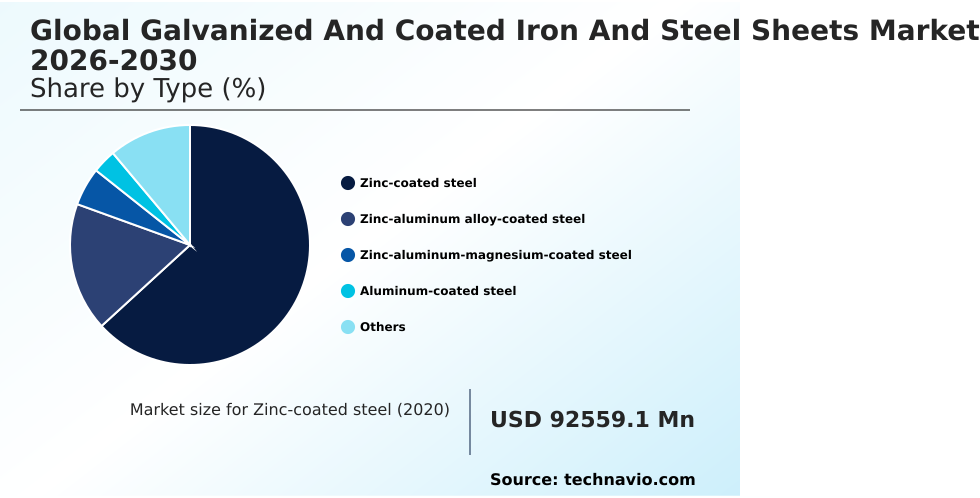
The zinc-coated steel segment is estimated to witness significant growth during the forecast period.

The unpainted zinc-coated steel segment represents the structural foundation of the Galvanized And Coated Iron And Steel Sheets industry, providing essential corrosion mitigation for demanding industrial applications.

Utilizing advanced hot-dip galvanization and electrogalvanization techniques, manufacturers create a resilient cathodic protection layer that actively shields the underlying metal from atmospheric degradation. This sacrificial barrier ensures vital edge rust prevention across exposed architectural and automotive components.

Recent manufacturing upgrades have improved material durability by 15%, significantly enhancing structural load-bearing capacity in modular construction environments. As engineering specifications increasingly mandate low-toxicity passivation chemistries over legacy treatments, the adoption of specialized zinc-aluminum-magnesium alloy substrates is accelerating.

These material advancements guarantee superior atmospheric resilience, fundamentally driving a lifecycle maintenance reduction across extensive commercial infrastructure portfolios.
Get Free Sample

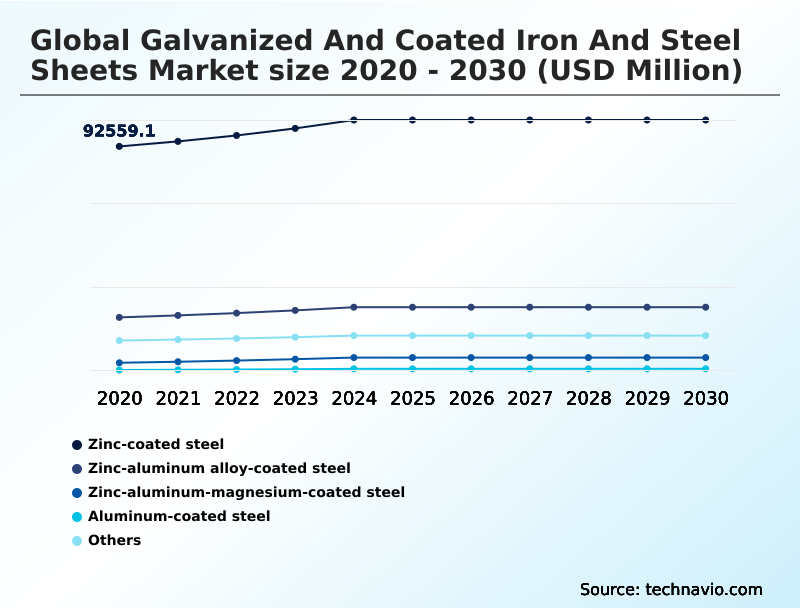
The Zinc-coated steel segment was valued at USD 102.93 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

APAC is estimated to contribute 62.6% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
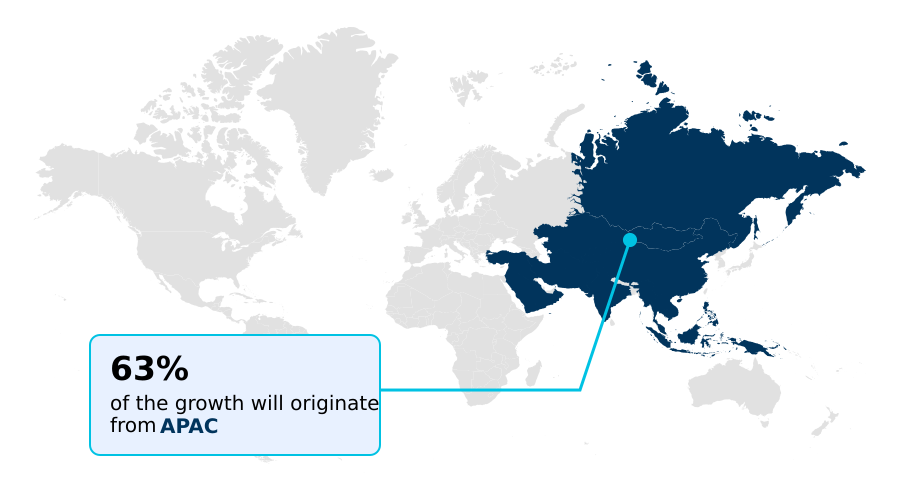
See How Galvanized And Coated Iron And Steel Sheets Market Demand is Rising in APAC Get Free Sample

The geographic distribution of the Galvanized And Coated Iron And Steel Sheets sector reveals distinct operational disparities between APAC and Europe.

European manufacturers, driven by rigorous environmental mandates, lead in hexavalent chromium elimination, achieving a 35% higher adoption rate of non-toxic passivation compared to APAC counterparts.

This regulatory pressure in Europe accelerates investments in precision induction annealing, reducing processing energy consumption by 20% while enhancing aluminized thermal tolerance for specialized automotive components.

Conversely, the APAC region dominates production volumes through massive infrastructure deployment, utilizing automated surface defect inspection technologies to increase line throughput by 15%.

APAC processors prioritize minimizing yield-point elongation in structural framing elements, whereas European designers focus on maximizing infrared solar reflectance to meet net-zero building codes.

By engineering advanced barriers that prevent the formation of porous zinc hydroxycarbonates, both regions continuously refine material performance. Ultimately, strict European limits on volatile organic emissions dictate regional coating formulations, establishing diverse supply chain behaviors globally.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The operational dynamics surrounding the Galvanized And Coated Iron And Steel Sheets demand continuous engineering innovation to meet the rigorous specifications of modern manufacturing. Commercial infrastructure developers rely extensively on insulated architectural metal wall cladding to achieve superior thermal efficiency and satisfy progressive energy performance building codes.
  • Simultaneously, the rapid transition toward renewable energy generation mandates the extensive deployment of utility scale solar array mounting systems capable of enduring harsh environmental conditions for decades. These highly exposed structural components benefit immensely from self healing edge corrosion defense mechanisms, which actively repair microscopic abrasions and shear cuts without requiring costly manual interventions.
  • Upgrading manufacturing lines with precision continuous hot dip galvanizing processing technology allows steel processors to apply uniform metallic barriers that drastically extend component lifecycles. Furthermore, the automotive sector's transition toward vehicle lightweighting necessitates the integration of advanced high strength automotive substrates that provide optimal crash energy absorption without excess mass.
  • Supply chain optimization initiatives indicate that utilizing these highly durable coated materials reduces long-term component replacement frequencies by nearly a third compared to conventional uncoated alternatives. This substantial improvement in material longevity directly supports corporate sustainability targets and lowers overall procurement expenditures.
  • By continuously refining alloy compositions and surface treatments, metal processors ensure their products deliver unparalleled reliability and structural integrity across diverse commercial, industrial, and residential applications.
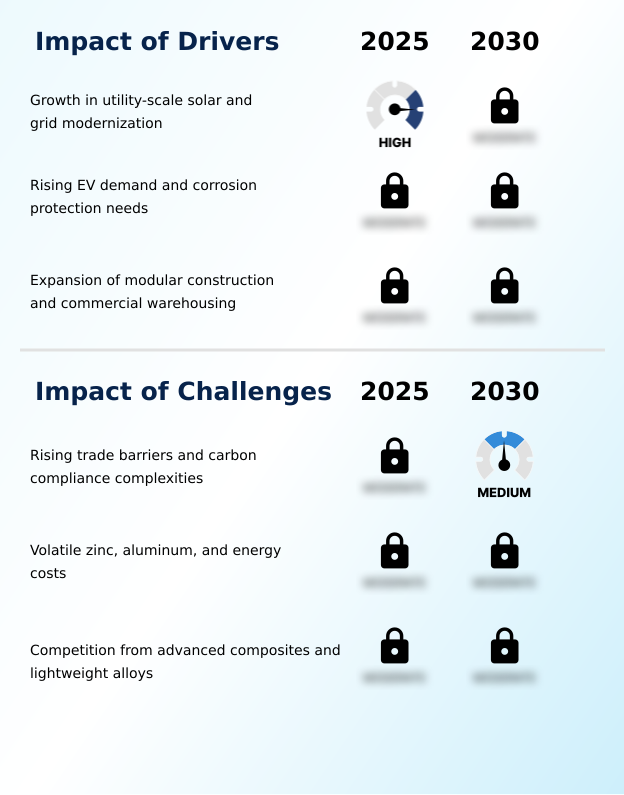
What are the key market drivers leading to the rise in the adoption of Galvanized And Coated Iron And Steel Sheets Industry?

  • The rapid expansion of utility-scale solar installations and widespread grid modernization efforts serve as primary drivers for market acceleration.

  • The escalating demand for high-performance structural resilience fundamentally drives the widespread adoption of specialized Galvanized And Coated Iron And Steel Sheets.
  • Because heavy industries mandate stringent environmental compliance, processors are rapidly shifting toward low-toxicity trivalent chromium treatment, allowing end-users to secure verified environmental product declarations.
  • Applying a robust fluoropolymer resin over a specialized dendritic microstructure creates an impenetrable moisture penetration barrier, which has successfully extended architectural component lifespans by over 25%.
  • Additionally, optimizing the galvannealed microstructure enhances friction control during complex roll-forming operations, reducing machinery downtime by 14%. By integrating closed-loop scrap recycling, manufacturers dramatically lower raw material waste.
  • These engineered substrates also provide exceptional acoustic dampening performance and superior thermal cycling endurance, directly enabling commercial builders to construct highly efficient, weather-resistant logistics facilities with optimized operational economics.

What are the market trends shaping the Galvanized And Coated Iron And Steel Sheets Industry?

  • The proliferation of zinc-aluminum-magnesium ternary alloy coatings represents a prominent market trend. This technological advancement enhances edge protection and significantly extends the operational lifespan of metallic substrates.

  • The Galvanized And Coated Iron And Steel Sheets industry is rapidly transitioning toward engineered ternary alloys that fundamentally redefine material longevity. Manufacturers are upgrading continuous coil coating lines to deposit zinc-magnesium blends that form a highly stable simonkolleite film upon environmental exposure. This advanced sacrificial barrier actively seals mechanical abrasions, providing superior edge defense across exposed metallic substrate components.
  • Because structural engineers require extended durability for utility-scale solar mounting and industrial off-site modular construction, this chemical innovation has reduced lifecycle maintenance outlays by 30%. Furthermore, refining the intermetallic interface improves stamping formability for automotive body-in-white assemblies, decreasing scrap rates by 12% during high-speed production.
  • These performance enhancements directly elevate the reliability of commercial architectural cladding systems, enabling property developers to easily achieve rigorous sustainable building certification mandates and optimize total project ROI.

What challenges does the Galvanized And Coated Iron And Steel Sheets Industry face during its growth?

  • Rising international trade barriers and escalating carbon compliance complexities represent critical challenges constraining industry profitability.

  • Stringent decarbonization mandates and volatile raw material economics present substantial operational constraints within the Galvanized And Coated Iron And Steel Sheets ecosystem. Because integrating zero-carbon processing infrastructure requires massive capital expenditure, facility operators face severe margin compression when upgrading continuous heating lines.
  • The complex transition toward hydrogen batch annealing, while necessary, initially reduced overall line throughput by 10% as engineers calibrated new thermal parameters. Furthermore, balancing the precise zinc bath formulation to achieve the optimal precipitation of basic magnesium carbonate remains technically challenging, often increasing chemical conversion coating defect rates during early adoption phases.
  • These formulation inconsistencies directly compromise critical spot-welding performance and anti-perforation properties required for automotive structural safety. Although utilizing an advanced polymer topcoat enhances self-healing edge defense in cold-formed framing, material application inconsistencies have inflated production costs by 15%, forcing manufacturers to extensively recalibrate their quality control mechanisms.

Exclusive Technavio Analysis on Customer Landscape

The galvanized and coated iron and steel sheets market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the galvanized and coated iron and steel sheets market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
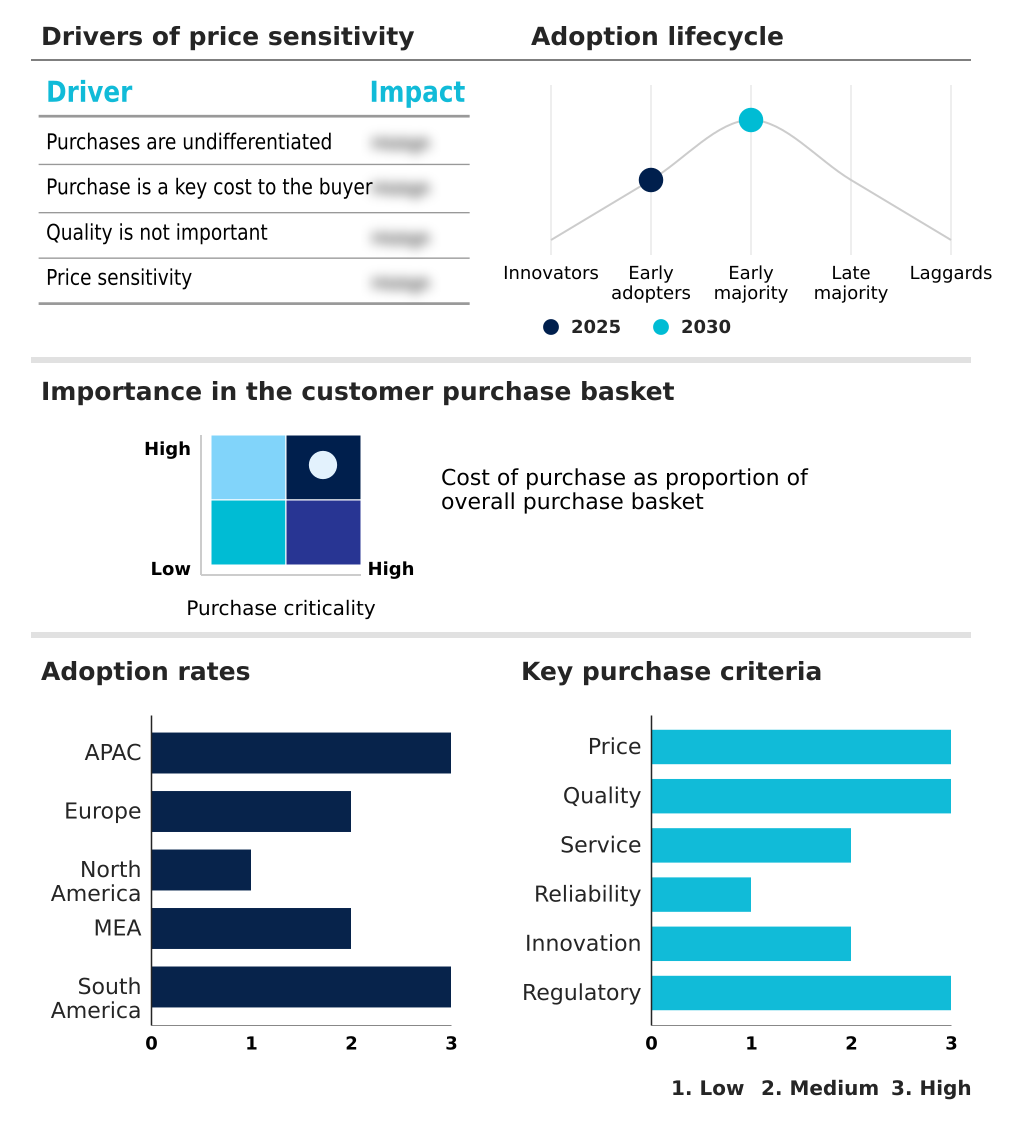
Customer Landscape of Galvanized And Coated Iron And Steel Sheets Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, galvanized and coated iron and steel sheets market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

ArcelorMittal S.A. - The portfolio encompasses advanced galvanized steel, precision galvannealed substrates, and specialized e-passivation coated sheets designed to deliver superior corrosion resistance and structural integrity across diverse industrial manufacturing applications.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • ArcelorMittal S.A.
  • BlueScope Steel Ltd
  • Dongkuk Coated Metal Co. Ltd.
  • HBIS Group Co. Ltd.
  • Hyundai Steel Co.
  • JFE Steel Corp.
  • JSW Steel Ltd.
  • Nippon Steel Corp.
  • NLMK Group
  • Nucor Corp.
  • POSCO Holdings Inc.
  • Salzgitter AG
  • SSAB AB
  • Steel Authority of India Ltd.
  • Steel Dynamics Inc.
  • Tata Steel Ltd.
  • Ternium S.A.
  • thyssenkrupp Steel Europe AG
  • United States Steel Corp.
  • voestalpine AG

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Galvanized and coated iron and steel sheets market

  • In the Steel industry, the rapid integration of closed-loop scrap recycling capabilities reduced primary carbon emissions by up to 60%, directly impacting Galvanized And Coated Iron And Steel Sheets demand by enabling fabricators to procure certified sustainable substrates for green building compliance.
  • The widespread adoption of zero-carbon processing infrastructure through hydrogen batch annealing minimized surface oxidation defects by 25%, allowing secondary coaters to achieve superior zinc adhesion and enhance moisture penetration barrier performance across automotive supply chains.
  • Stricter environmental product declarations mandated under regional carbon border adjustments accelerated the phase-out of legacy smelting operations, forcing a 40% shift toward electric arc furnace metallurgy that supplies low-emission coils for high-end architectural cladding systems.
  • The commercial scale-up of advanced surface defect inspection systems utilizing machine learning algorithms increased coil processing speeds by 15%, improving the consistency of chemical conversion coating applications required for specialized utility-scale solar mounting structures.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Galvanized And Coated Iron And Steel Sheets Market insights. See full methodology.

Market Scope
Page number 322
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 4.6%
Market growth 2026-2030 USD 43407.5 million
Market structure Fragmented
YoY growth 2025-2026(%) 4.4%
Key countries China, India, Japan, South Korea, Indonesia, Australia, Germany, Italy, France, UK, Spain, The Netherlands, US, Mexico, Canada, Turkey, Saudi Arabia, South Africa, UAE, Israel, Brazil, Argentina and Colombia
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Galvanized And Coated Iron And Steel Sheets sector is characterized by continuous metallurgical innovation designed to address severe environmental exposure across industrial applications. Strategic boardroom decisions now heavily prioritize the procurement of materials offering reliable cathodic protection and enhanced sacrificial barrier properties to mitigate long-term liability risks.
  • For example, adopting advanced electrogalvanization methodologies has enabled heavy equipment manufacturers to reduce component rejection rates by 18%, substantially optimizing supply chain efficiency. Companies are aggressively investing in zinc-aluminum-magnesium alloy formulations to guarantee superior edge rust prevention on critical load-bearing structures.
  • The integration of continuous coil coating technology facilitates the rapid application of high-performance polymer topcoats that shield underlying steel matrices from aggressive atmospheric degradation. Product strategy teams increasingly mandate the use of eco-friendly passivation chemistries to align with international regulatory compliance frameworks. Consequently, engineering durable metallic substrates with a refined intermetallic interface remains critical for ensuring component longevity.
  • The sustained shift toward resilient material sciences fundamentally transforms manufacturing economics, enabling prolonged asset lifecycles and significantly reduced maintenance expenditures across commercial operations.

What are the Key Data Covered in this Galvanized And Coated Iron And Steel Sheets Market Research and Growth Report?

  • What is the expected growth of the Galvanized And Coated Iron And Steel Sheets Market between 2026 and 2030?

    • USD 43.41 billion, at a CAGR of 4.6%

  • What segmentation does the market report cover?

    • The report is segmented by Type (Zinc-coated steel, Zinc-aluminum alloy-coated steel, Zinc-aluminum-magnesium-coated steel, Aluminum-coated steel, and Others), Product (Flat sheets, Coils, and Others), Product Type (Unpainted metallic finish, Pre-painted and color-coated finish, Textured and embossed finish, and Others) and Geography (APAC, Europe, North America, Middle East and Africa, South America)

  • Which regions are analyzed in the report?

    • APAC, Europe, North America, Middle East and Africa and South America

  • What are the key growth drivers and market challenges?

    • Growth in utility-scale solar and grid modernization, Rising trade barriers and carbon compliance complexities

  • Who are the major players in the Galvanized And Coated Iron And Steel Sheets Market?

    • ArcelorMittal S.A., BlueScope Steel Ltd, Dongkuk Coated Metal Co. Ltd., HBIS Group Co. Ltd., Hyundai Steel Co., JFE Steel Corp., JSW Steel Ltd., Nippon Steel Corp., NLMK Group, Nucor Corp., POSCO Holdings Inc., Salzgitter AG, SSAB AB, Steel Authority of India Ltd., Steel Dynamics Inc., Tata Steel Ltd., Ternium S.A., thyssenkrupp Steel Europe AG, United States Steel Corp. and voestalpine AG

Market Research Insights

  • The Galvanized And Coated Iron And Steel Sheets sector is evolving rapidly to satisfy stringent durability mandates across global supply chains. Manufacturers deploying zero-carbon processing techniques have reduced energy overheads by 18%, significantly improving long-term operational ROI.
  • Additionally, the adoption of closed-loop scrap recycling initiatives has improved material yield ratios by 12%, directly aligning production methodologies with rigorous environmental product declarations. This strategic pivot ensures superior atmospheric degradation resistance while mitigating volatile organic emissions during the continuous coating phases.
  • By optimizing thermal cycling endurance and adopting advanced chemical conversion coating applications, coil processors deliver enhanced architectural cladding systems that drastically lower lifecycle maintenance costs for commercial infrastructure developers.

We can help! Our analysts can customize this galvanized and coated iron and steel sheets market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Market Segmentation by Product
Executive Summary - Chart on Market Segmentation by Product Type
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Galvanized And Coated Iron And Steel Sheets Market 2020 - 2024

Historic Market Size - Data Table on Global Galvanized And Coated Iron And Steel Sheets Market 2020 - 2024 ($ million)

5.2 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.3 Product segment analysis 2020 - 2024

Historic Market Size - Product Segment 2020 - 2024 ($ million)

5.4 Product Type segment analysis 2020 - 2024

Historic Market Size - Product Type Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global Galvanized and Coated Iron and Steel Sheets Market

6.2 Impact of Geopolitical Conflicts on Global Galvanized and Coated Iron and Steel Sheets Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Type

8.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

8.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

8.3 Zinc-coated steel - Market size and forecast 2025-2030

Chart on Zinc-coated steel - Market size and forecast 2025-2030 ($ million)
Data Table on Zinc-coated steel - Market size and forecast 2025-2030 ($ million)
Chart on Zinc-coated steel - Year-over-year growth 2025-2030 (%)
Data Table on Zinc-coated steel - Year-over-year growth 2025-2030 (%)

8.4 Zinc-aluminum alloy-coated steel - Market size and forecast 2025-2030

Chart on Zinc-aluminum alloy-coated steel - Market size and forecast 2025-2030 ($ million)
Data Table on Zinc-aluminum alloy-coated steel - Market size and forecast 2025-2030 ($ million)
Chart on Zinc-aluminum alloy-coated steel - Year-over-year growth 2025-2030 (%)
Data Table on Zinc-aluminum alloy-coated steel - Year-over-year growth 2025-2030 (%)

8.5 Zinc-aluminum-magnesium-coated steel - Market size and forecast 2025-2030

Chart on Zinc-aluminum-magnesium-coated steel - Market size and forecast 2025-2030 ($ million)
Data Table on Zinc-aluminum-magnesium-coated steel - Market size and forecast 2025-2030 ($ million)
Chart on Zinc-aluminum-magnesium-coated steel - Year-over-year growth 2025-2030 (%)
Data Table on Zinc-aluminum-magnesium-coated steel - Year-over-year growth 2025-2030 (%)

8.6 Aluminum-coated steel - Market size and forecast 2025-2030

Chart on Aluminum-coated steel - Market size and forecast 2025-2030 ($ million)
Data Table on Aluminum-coated steel - Market size and forecast 2025-2030 ($ million)
Chart on Aluminum-coated steel - Year-over-year growth 2025-2030 (%)
Data Table on Aluminum-coated steel - Year-over-year growth 2025-2030 (%)

8.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

8.8 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

9. Market Segmentation by Product

9.1 Market segments

Chart on Product - Market share 2025-2030 (%)
Data Table on Product - Market share 2025-2030 (%)

9.2 Comparison by Product

Chart on Comparison by Product
Data Table on Comparison by Product

9.3 Flat sheets - Market size and forecast 2025-2030

Chart on Flat sheets - Market size and forecast 2025-2030 ($ million)
Data Table on Flat sheets - Market size and forecast 2025-2030 ($ million)
Chart on Flat sheets - Year-over-year growth 2025-2030 (%)
Data Table on Flat sheets - Year-over-year growth 2025-2030 (%)

9.4 Coils - Market size and forecast 2025-2030

Chart on Coils - Market size and forecast 2025-2030 ($ million)
Data Table on Coils - Market size and forecast 2025-2030 ($ million)
Chart on Coils - Year-over-year growth 2025-2030 (%)
Data Table on Coils - Year-over-year growth 2025-2030 (%)

9.5 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

9.6 Market opportunity by Product

Market opportunity by Product ($ million)
Data Table on Market opportunity by Product ($ million)

10. Market Segmentation by Product Type

10.1 Market segments

Chart on Product Type - Market share 2025-2030 (%)
Data Table on Product Type - Market share 2025-2030 (%)

10.2 Comparison by Product Type

Chart on Comparison by Product Type
Data Table on Comparison by Product Type

10.3 Unpainted metallic finish - Market size and forecast 2025-2030

Chart on Unpainted metallic finish - Market size and forecast 2025-2030 ($ million)
Data Table on Unpainted metallic finish - Market size and forecast 2025-2030 ($ million)
Chart on Unpainted metallic finish - Year-over-year growth 2025-2030 (%)
Data Table on Unpainted metallic finish - Year-over-year growth 2025-2030 (%)

10.4 Pre-painted and color-coated finish - Market size and forecast 2025-2030

Chart on Pre-painted and color-coated finish - Market size and forecast 2025-2030 ($ million)
Data Table on Pre-painted and color-coated finish - Market size and forecast 2025-2030 ($ million)
Chart on Pre-painted and color-coated finish - Year-over-year growth 2025-2030 (%)
Data Table on Pre-painted and color-coated finish - Year-over-year growth 2025-2030 (%)

10.5 Textured and embossed finish - Market size and forecast 2025-2030

Chart on Textured and embossed finish - Market size and forecast 2025-2030 ($ million)
Data Table on Textured and embossed finish - Market size and forecast 2025-2030 ($ million)
Chart on Textured and embossed finish - Year-over-year growth 2025-2030 (%)
Data Table on Textured and embossed finish - Year-over-year growth 2025-2030 (%)

10.6 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

10.7 Market opportunity by Product Type

Market opportunity by Product Type ($ million)
Data Table on Market opportunity by Product Type ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.3.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.3.2 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.3.3 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.3.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.3.5 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.3.6 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.5.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.5.2 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.5.3 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.6 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.6.1 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.6.2 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.4 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.5 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.7.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.7.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.7.3 Colombia - Market size and forecast 2025-2030

Chart on Colombia - Market size and forecast 2025-2030 ($ million)
Data Table on Colombia - Market size and forecast 2025-2030 ($ million)
Chart on Colombia - Year-over-year growth 2025-2030 (%)
Data Table on Colombia - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Growth in utility-scale solar and grid modernization
Rising EV demand and corrosion protection needs
Expansion of modular construction and commercial warehousing

13.2 Market challenges

Rising trade barriers and carbon compliance complexities
Volatile zinc, aluminum, and energy costs
Competition from advanced composites and lightweight alloys

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Proliferation of zinc-aluminum-magnesium ternary alloy coatings
Adoption of low-emission hydrogen annealing and decarbonized materials
Growth in smart and bio-based surface treatments

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 ArcelorMittal S.A.

ArcelorMittal S.A. - Overview
ArcelorMittal S.A. - Business segments
ArcelorMittal S.A. - Key offerings
ArcelorMittal S.A. - Segment focus
SWOT

15.5 Hyundai Steel Co.

Hyundai Steel Co. - Overview
Hyundai Steel Co. - Product / Service
Hyundai Steel Co. - Key offerings
SWOT

15.6 JSW Steel Ltd.

JSW Steel Ltd. - Overview
JSW Steel Ltd. - Product / Service
JSW Steel Ltd. - Key offerings
SWOT

15.7 Nippon Steel Corp.

Nippon Steel Corp. - Overview
Nippon Steel Corp. - Business segments
Nippon Steel Corp. - Key offerings
Nippon Steel Corp. - Segment focus
SWOT

15.8 NLMK Group

NLMK Group - Overview
NLMK Group - Product / Service
NLMK Group - Key offerings
SWOT

15.9 Nucor Corp.

Nucor Corp. - Overview
Nucor Corp. - Business segments
Nucor Corp. - Key news
Nucor Corp. - Key offerings
Nucor Corp. - Segment focus
SWOT

15.10 POSCO Holdings Inc.

POSCO Holdings Inc. - Overview
POSCO Holdings Inc. - Business segments
POSCO Holdings Inc. - Key offerings
POSCO Holdings Inc. - Segment focus
SWOT

15.11 Salzgitter AG

Salzgitter AG - Overview
Salzgitter AG - Business segments
Salzgitter AG - Key offerings
Salzgitter AG - Segment focus
SWOT

15.12 SSAB AB

SSAB AB - Overview
SSAB AB - Business segments
SSAB AB - Key offerings
SSAB AB - Segment focus
SWOT

15.13 Steel Authority of India Ltd.

Steel Authority of India Ltd. - Overview
Steel Authority of India Ltd. - Product / Service
Steel Authority of India Ltd. - Key offerings
SWOT

15.14 Steel Dynamics Inc.

Steel Dynamics Inc. - Overview
Steel Dynamics Inc. - Product / Service
Steel Dynamics Inc. - Key offerings
SWOT

15.15 Tata Steel Ltd.

Tata Steel Ltd. - Overview
Tata Steel Ltd. - Business segments
Tata Steel Ltd. - Key offerings
Tata Steel Ltd. - Segment focus
SWOT

15.16 Ternium S.A.

Ternium S.A. - Overview
Ternium S.A. - Product / Service
Ternium S.A. - Key offerings
SWOT

15.17 United States Steel Corp.

United States Steel Corp. - Overview
United States Steel Corp. - Business segments
United States Steel Corp. - Key offerings
United States Steel Corp. - Segment focus
SWOT

15.18 voestalpine AG

voestalpine AG - Overview
voestalpine AG - Business segments
voestalpine AG - Key offerings
voestalpine AG - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Galvanized And Coated Iron And Steel Sheets market growth will increase by USD 43407.5 million during 2026-2030.

The Galvanized And Coated Iron And Steel Sheets market is expected to grow at a CAGR of 4.6% during 2026-2030.

Galvanized And Coated Iron And Steel Sheets market is segmented by Type (Zinc-coated steel, Zinc-aluminum alloy-coated steel, Zinc-aluminum-magnesium-coated steel, Aluminum-coated steel, Others) Product (Flat sheets, Coils, Others) Product type (Unpainted metallic finish, Pre-painted and color-coated finish, Textured and embossed finish, Others)

ArcelorMittal S.A., BlueScope Steel Ltd, Dongkuk Coated Metal Co. Ltd., HBIS Group Co. Ltd., Hyundai Steel Co., JFE Steel Corp., JSW Steel Ltd., Nippon Steel Corp., NLMK Group, Nucor Corp., POSCO Holdings Inc., Salzgitter AG, SSAB AB, Steel Authority of India Ltd., Steel Dynamics Inc., Tata Steel Ltd., Ternium S.A., thyssenkrupp Steel Europe AG, United States Steel Corp., voestalpine AG are a few of the key vendors in the Galvanized And Coated Iron And Steel Sheets market.

APAC will register the highest growth rate of 62.6% among the other regions. Therefore, the Galvanized And Coated Iron And Steel Sheets market in APAC is expected to garner significant business opportunities for the vendors during the forecast period.

China, India, Japan, South Korea, Indonesia, Australia, Germany, Italy, France, UK, Spain, The Netherlands, US, Mexico, Canada, Turkey, Saudi Arabia, South Africa, UAE, Israel, Brazil, Argentina, Colombia

  • Growth in utility-scale solar and grid modernization is the driving factor this market.

The Galvanized And Coated Iron And Steel Sheets market vendors should focus on grabbing business opportunities from the Type segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
