Injection Molded Plastics Market Analysis, Size, and Forecast 2026-2030: APAC (China, India, and Japan), North America (US, Canada, and Mexico), Europe (Germany, Italy, and France), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Injection Molded Plastics Market Analysis, Size, and Forecast 2026-2030:
APAC (China, India, and Japan), North America (US, Canada, and Mexico), Europe (Germany, Italy, and France), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Published: Oct 2026 308 Pages SKU: IRTNTR44437

Market Overview at a Glance

$105.20 B
Market Opportunity
4.6%
CAGR 2025 - 2030
54.4%
APAC Growth
$132.39 B
Packaging segment 2024

Injection Molded Plastics Market Size 2026-2030

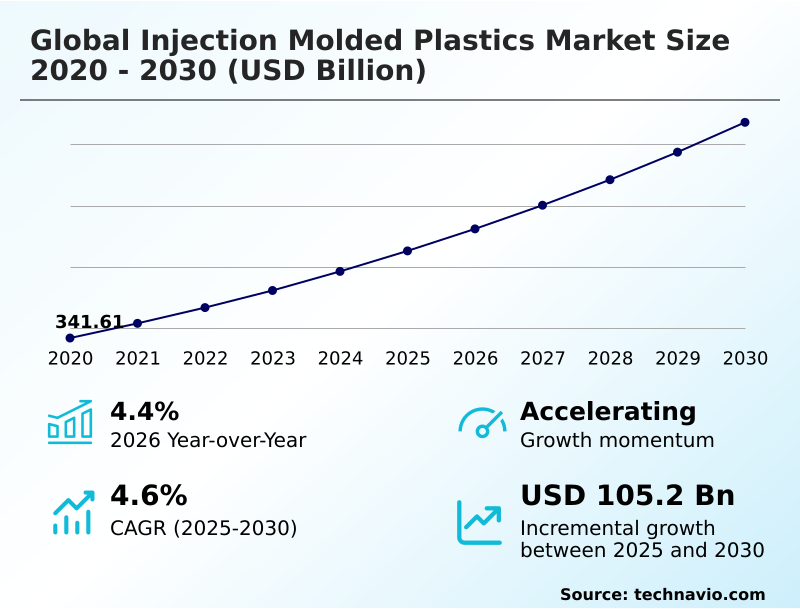
The injection molded plastics market size is valued to increase by USD 105.20 billion, at a CAGR of 4.6% from 2025 to 2030. Proliferation of lightweight components in automotive sector will drive the injection molded plastics market.

Major Market Trends & Insights

  • APAC dominated the market and accounted for a 54.4% growth during the forecast period.
  • By Application - Packaging segment was valued at USD 132.39 billion in 2024
  • By Product - Polyethylene segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 176.49 billion
  • Market Future Opportunities: USD 105.20 billion
  • CAGR from 2025 to 2030 : 4.6%

Market Summary

  • The Injection Molded Plastics Market demonstrates robust expansion driven by advanced material science and automated manufacturing techniques. Processors are increasingly adopting multi-cavity tooling to meet rigorous production demands across diverse industrial sectors.
  • A primary driver of this market is the aggressive pursuit of vehicle lightweighting, which causes manufacturers to replace heavy metal assemblies with high-performance engineered polymers to improve fuel efficiency and battery range.
  • Conversely, the market faces significant challenges from stringent environmental regulations mandating circular economy practices, forcing processors to overhaul established supply chains and incur high initial costs for recycling infrastructure.
  • In a practical supply chain scenario, a major consumer electronics manufacturer integrated predictive maintenance sensors into their molding machinery, resulting in a 25% decrease in unplanned equipment downtime compared to legacy hydraulic systems. Such operational optimizations are essential for maintaining competitive margins amid fluctuating raw material costs.
  • Advanced process controls and automated part extraction systems continue to refine product quality, ensuring manufacturers consistently achieve exact dimensional tolerances in high-volume production runs.

What will be the Size of the Injection Molded Plastics Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Injection Molded Plastics Market Segmented?

The injection molded plastics industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Application
    • Packaging
    • Consumer goods
    • Automobile
    • Others
  • Product
    • Polyethylene
    • Polypropylene
    • Polyvinyl chloride
    • Others
  • Technology
    • Hydraulic
    • Electric
    • Hybrid
  • Geography
    • APAC
      • China
      • India
      • Japan
      • South Korea
      • Australia
      • Indonesia
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • Italy
      • France
      • UK
      • Spain
      • The Netherlands
    • South America
      • Brazil
      • Argentina
      • Chile
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Turkey
      • Egypt

By Application Insights

The packaging segment is estimated to witness significant growth during the forecast period.

The packaging segment within the Injection Molded Plastics market represents a critical component of global polymer consumption, driven by demand for advanced rigid containers.

Manufacturers increasingly prioritize high-density materials like polypropylene and specialized low-density alternatives to construct rigid packaging containers that offer superior barrier protection.

This shift demands precise operational control over the pellet feed through the hopper, barrel, and screw to minimize shrinkage and ensure optimal dimensional-stability.

By adopting advanced extruder configurations, powerful clamping mechanisms, and optimized platen designs, processors have successfully improved material yield rates by 18%, reducing overall scrap in high-volume operations.

These performance improvements reflect a broader industrial mandate to balance lightweight packaging designs with structural integrity, ensuring products withstand rigorous supply chain pressures without sacrificing processing efficiency.
Get Free Sample

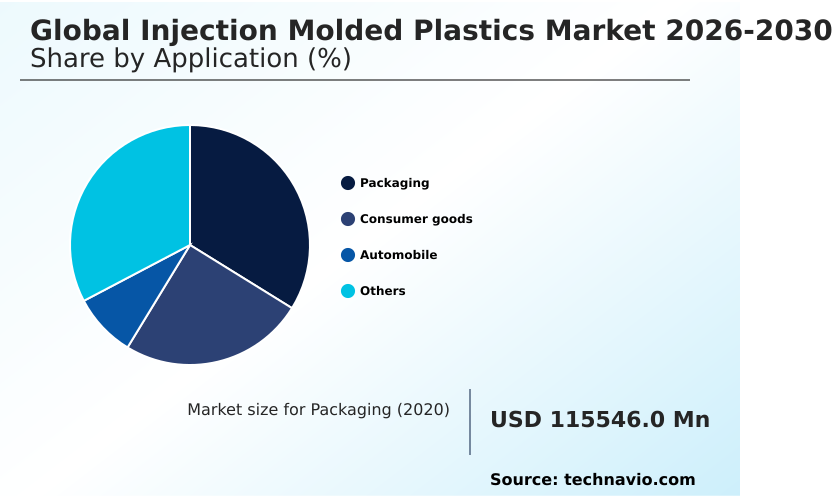
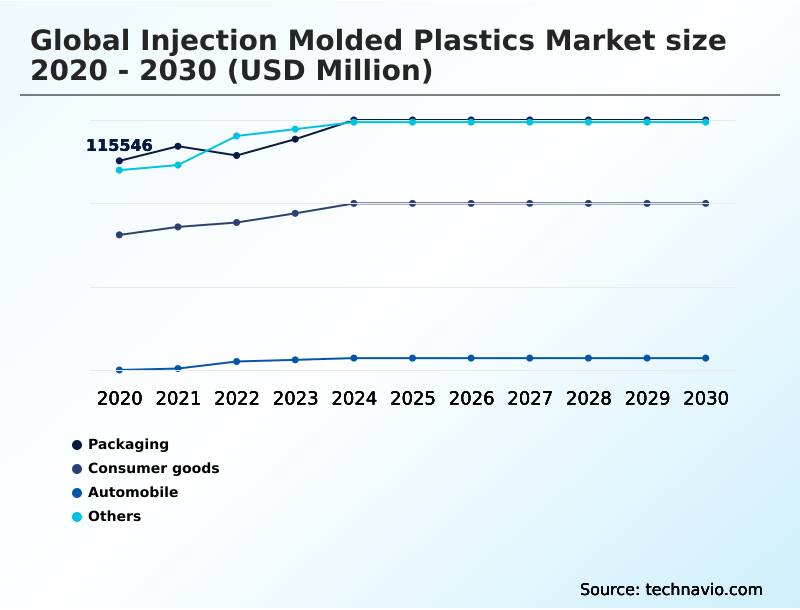
The Packaging segment was valued at USD 132.39 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

APAC is estimated to contribute 54.4% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
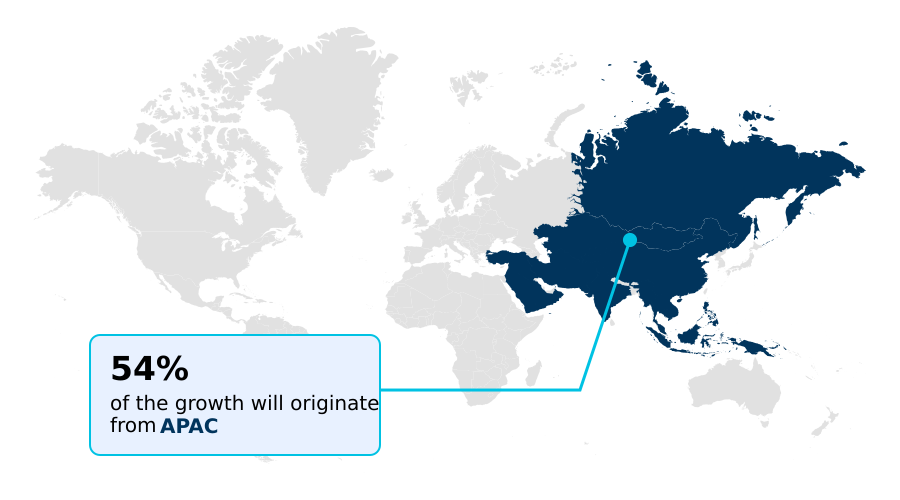
See How Injection Molded Plastics Market Demand is Rising in APAC Get Free Sample

The geographic distribution of the Injection Molded Plastics market highlights distinct operational strategies between APAC and North America.

APAC maintains dominance through massive industrial scale, where regional processors utilize high tonnage machinery and advanced tooling networks to achieve a 35% higher production throughput.

In contrast, North America prioritizes precision manufacturing, focusing on specialized micro-molding technologies to serve the rigorous medical device industry.

Consequently, North American facilities report a 28% reduction in post-production inspection times due to superior process controls governing gate placement, boss reinforcement, and rib structures to prevent sink marks.

Furthermore, the widespread adoption of hot runner networks across both regions has streamlined material flow, while meticulous attention to draft-angle and parting-line accuracy contributes to an overall 15% decrease in operational energy consumption, reinforcing supply chain resilience.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The continuous evolution of the Injection Molded Plastics market relies on sophisticated equipment and specialized resin formulations to satisfy complex industrial requirements. As consumer demand for convenience and sustainability rises, the packaging sector has heavily integrated thin-wall rigid packaging containers, which offer exceptional barrier properties while minimizing material usage.
  • Simultaneously, the transportation industry is undergoing a structural shift, accelerating the integration of automotive lightweight thermoplastic components to enhance battery range and meet stringent emission targets. This transition requires significant processing capability, prompting manufacturers to deploy high-tonnage servo hydraulic presses that deliver immense holding force and exceptional energy efficiency compared to legacy equipment.
  • The adoption of these advanced presses yields an 18% improvement in cycle time consistency, directly optimizing factory floor planning and supply chain scheduling. In the healthcare sector, regulatory mandates necessitate pristine manufacturing environments for the production of medical grade biocompatible syringes, ensuring absolute sterility and structural integrity.
  • To achieve these extreme production volumes without compromising dimensional accuracy, processors utilize highly engineered multi-cavity hot runner systems. These systems optimize the thermal flow of molten polymers, drastically reducing material degradation and cycle times. By strategically aligning these technological capabilities, businesses can streamline logistics and improve overall operational compliance, safeguarding their competitive positioning.
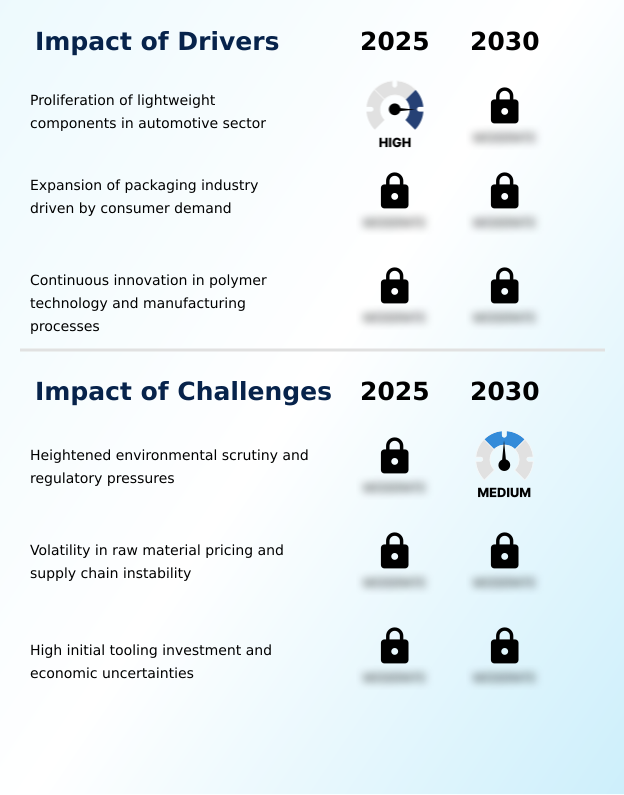
What are the key market drivers leading to the rise in the adoption of Injection Molded Plastics Industry?

  • The proliferation of lightweight components within the automotive sector serves as a primary catalyst accelerating market expansion.

  • The urgent industrial mandate for vehicle lightweighting serves as a primary demand trigger for the Injection Molded Plastics sector.
  • Automakers are systematically utilizing advanced engineering polymers such as polycarbonate and polyamide to manufacture robust lightweight structural components, replacing heavy metal structures to improve fuel efficiency.
  • This substitution forces molders to optimize complex fluid rheology to prevent internal stress and warpage during cooling.
  • By integrating sophisticated overmolding, multi-shot, and insert molding techniques, manufacturers have successfully lowered operational energy use by 12% and improved component assembly accuracy by 18%. This technological refinement directly mitigates mechanical failure and ensures strict dimensional tolerance is maintained.
  • Ultimately, these operational enhancements allow businesses to aggressively lower manufacturing overhead and rapidly scale production to meet the intensifying demand for lightweight transportation solutions.

What are the market trends shaping the Injection Molded Plastics Industry?

  • The transition toward sustainable and circular economy practices constitutes a defining trend within the current industrial landscape. This strategic pivot emphasizes material recovery and renewable feedstocks to minimize environmental impact.

  • The rapid integration of smart automation and circular material streams is a defining trend within the Injection Molded Plastics sector. Processors are increasingly transitioning to advanced thermoplastic and thermosetting compounds, driven by stringent environmental mandates. This transition requires exact control over polymer crystallinity to maintain structural integrity and eliminate cavitation during flow through the runner and sprue.
  • Consequently, businesses deploying AI-driven process monitoring have improved material utilization efficiency by 25% and reduced unplanned machine downtime by 30%. In specialized sectors, the push for enhanced biocompatibility in medical devices has led to the adoption of ultra-pure resin formulations for sterile medical syringes.
  • This shift directly impacts operational logistics by requiring upgraded cleanroom infrastructure, which ultimately enhances product reliability and shields organizations from rigorous regulatory compliance penalties globally.

What challenges does the Injection Molded Plastics Industry face during its growth?

  • Heightened environmental scrutiny and stringent regulatory pressures represent critical challenges impeding sustained industry growth.

  • Heightened environmental scrutiny and erratic raw material pricing present formidable structural limitations for the Injection Molded Plastics sector. The legislative push for higher post-consumer recycled content forces processors to manage inconsistent feedstock quality involving polyethylene, polybutylene, and polyethersulfone blends.
  • These material inconsistencies cause severe pressure fluctuations, ultimately leading to critical structural defects such as weak weld-line formations, internal void anomalies, splay, knit-line fractures, and incomplete short-shot molding. To combat these issues and prevent excess flash or draft anomalies, facilities must heavily invest in heavy-duty hydraulic presses and upgraded ejector mechanisms, driving up operational costs by 15%.
  • This financial burden reduces overall profit margins by 12% for mid-tier contract manufacturers. Consequently, businesses struggle to balance strict sustainability compliance with the economic realities of maintaining precision quality in high-volume production environments.

Exclusive Technavio Analysis on Customer Landscape

The injection molded plastics market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the injection molded plastics market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
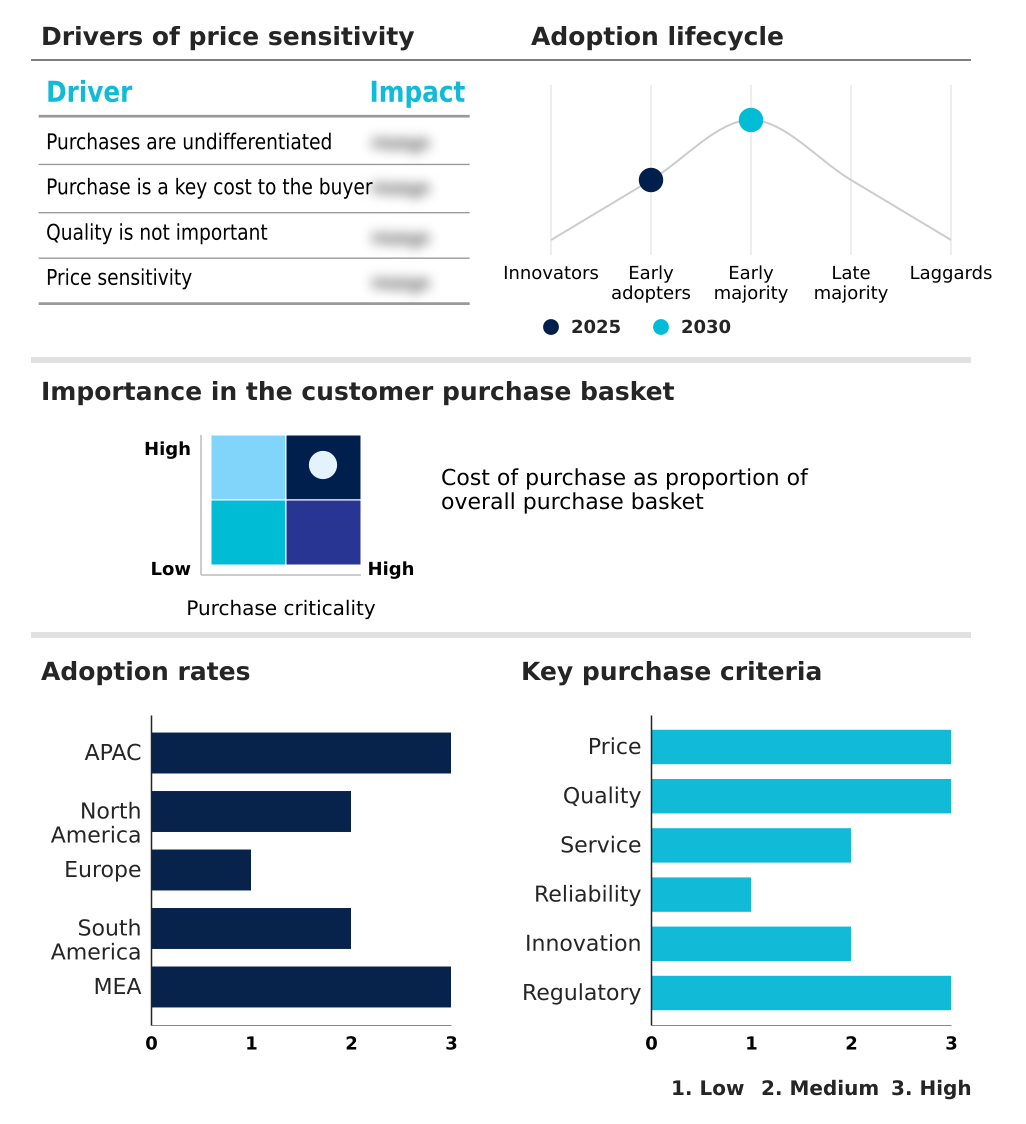
Customer Landscape of Injection Molded Plastics Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, injection molded plastics market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Accurate Molded Products - Advanced precision manufacturing solutions deliver highly automated thermoplastic forming, insert integration, and cleanroom assembly services tailored for rigorous medical, automotive, and high-volume industrial applications.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Accurate Molded Products
  • Amcor Plc
  • Crescent Industries Inc.
  • EVCO Plastics
  • Extreme Molding LLC
  • Gerresheimer AG
  • Hongrita Mold Ltd.
  • Jones Plastic and Engineering Co.
  • Mack Molding Co.
  • MMI Engineered Solutions
  • Molded Devices Inc.
  • MSI Mold Builders
  • Nolato AB
  • Proto Labs Inc.
  • PTI Engineered Plastics Inc.
  • Revere Plastics Systems LLC
  • Rosti Group AB
  • Seaway Plastics Engineering LLC
  • Sungplastic
  • The Rodon Group

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Injection molded plastics market

  • In the Specialty Chemicals industry, the rapid commercialization of bio-based low-density resins and specialized pellet formulations has shifted raw material procurement strategies, directly impacting Injection Molded Plastics demand by enabling manufacturers to optimize runner and sprue configurations for a 15% reduction in carbon footprint across high-volume packaging applications.
  • The enforcement of the EU REACH directive concerning hazardous flame retardants has accelerated the adoption of non-halogenated polybutylene compounds, compelling processors in the Injection Molded Plastics sector to upgrade their extruder and barrel infrastructure, which improved thermal processing efficiency by 12%.
  • Advancements in smart additive compounding for thermoplastic and thermosetting materials have eliminated persistent splay and flash defects during mass production, allowing the Injection Molded Plastics market to achieve a 20% increase in first-pass yield for critical automotive structural components.
  • The integration of predictive rheology software and automated gate pressure controls within high-performance specialty polymer synthesis has mitigated knit-line vulnerabilities, driving the Injection Molded Plastics sector to enhance mechanical tensile strength by 22% in aerospace enclosures.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Injection Molded Plastics Market insights. See full methodology.

Market Scope
Page number 308
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 4.6%
Market growth 2026-2030 USD 105199.0 million
Market structure Fragmented
YoY growth 2025-2026(%) 4.4%
Key countries China, India, Japan, South Korea, Australia, Indonesia, US, Canada, Mexico, Germany, Italy, France, UK, Spain, The Netherlands, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Turkey and Egypt
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Injection Molded Plastics industry is characterized by significant material innovation and stringent process control parameters. Manufacturers are extensively utilizing advanced engineering resins such as polycarbonate and polyamide to replace traditional metal substrates in structurally demanding applications. This substitution strategy is essential for corporate product planning, directly aligning with global lightweighting and energy conservation mandates.
  • To meet exact dimensional requirements, processors employ sophisticated techniques including overmolding and multi-shot injection, which seamlessly combine disparate polymers into singular, highly functional assemblies. The precision achieved through these methods ensures parts maintain strict tolerance limits under mechanical stress. Furthermore, the integration of specialized materials like polybutylene and polyethersulfone enables components to withstand extreme thermal and chemical environments.
  • By adopting automated insert molding processes, companies have achieved a 30% reduction in secondary assembly time, significantly optimizing manufacturing budgets. This continuous refinement of material science and processing architecture empowers industrial stakeholders to mitigate supply chain risks, elevate end-user product reliability, and adapt rapidly to evolving international compliance standards.

What are the Key Data Covered in this Injection Molded Plastics Market Research and Growth Report?

  • What is the expected growth of the Injection Molded Plastics Market between 2026 and 2030?

    • USD 105.20 billion, at a CAGR of 4.6%

  • What segmentation does the market report cover?

    • The report is segmented by Application (Packaging, Consumer goods, Automobile, and Others), Product (Polyethylene, Polypropylene, Polyvinyl chloride, and Others), Technology (Hydraulic, Electric, and Hybrid) and Geography (APAC, North America, Europe, South America, Middle East and Africa)

  • Which regions are analyzed in the report?

    • APAC, North America, Europe, South America and Middle East and Africa

  • What are the key growth drivers and market challenges?

    • Proliferation of lightweight components in automotive sector, Heightened environmental scrutiny and regulatory pressures

  • Who are the major players in the Injection Molded Plastics Market?

    • Accurate Molded Products, Amcor Plc, Crescent Industries Inc., EVCO Plastics, Extreme Molding LLC, Gerresheimer AG, Hongrita Mold Ltd., Jones Plastic and Engineering Co., Mack Molding Co., MMI Engineered Solutions, Molded Devices Inc., MSI Mold Builders, Nolato AB, Proto Labs Inc., PTI Engineered Plastics Inc., Revere Plastics Systems LLC, Rosti Group AB, Seaway Plastics Engineering LLC, Sungplastic and The Rodon Group

Market Research Insights

  • The Injection Molded Plastics Market is undergoing a rapid technological transformation focused on operational precision and material efficiency. Manufacturers are leveraging advanced clamping systems and optimized platen designs to enhance production velocity. By implementing closed-loop process controls, facilities have improved draft-angle consistency by 14% and reduced void defects by 22% compared to conventional manufacturing methods.
  • These enhancements directly lower material waste and improve overall equipment effectiveness. Furthermore, the integration of automated boss and rib structural molding has accelerated assembly speeds by 18%, significantly lowering overhead costs while aligning with strict regulatory compliance standards across international supply chains.

We can help! Our analysts can customize this injection molded plastics market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Market Segmentation by Product
Executive Summary - Chart on Market Segmentation by Technology
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Injection Molded Plastics Market 2020 - 2024

Historic Market Size - Data Table on Global Injection Molded Plastics Market 2020 - 2024 ($ million)

5.2 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ million)

5.3 Product segment analysis 2020 - 2024

Historic Market Size - Product Segment 2020 - 2024 ($ million)

5.4 Technology segment analysis 2020 - 2024

Historic Market Size - Technology Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global Injection Molded Plastics Market

6.2 Impact of Geopolitical Conflicts on Global Injection Molded Plastics Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Application

8.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

8.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

8.3 Packaging - Market size and forecast 2025-2030

Chart on Packaging - Market size and forecast 2025-2030 ($ million)
Data Table on Packaging - Market size and forecast 2025-2030 ($ million)
Chart on Packaging - Year-over-year growth 2025-2030 (%)
Data Table on Packaging - Year-over-year growth 2025-2030 (%)

8.4 Consumer goods - Market size and forecast 2025-2030

Chart on Consumer goods - Market size and forecast 2025-2030 ($ million)
Data Table on Consumer goods - Market size and forecast 2025-2030 ($ million)
Chart on Consumer goods - Year-over-year growth 2025-2030 (%)
Data Table on Consumer goods - Year-over-year growth 2025-2030 (%)

8.5 Automobile - Market size and forecast 2025-2030

Chart on Automobile - Market size and forecast 2025-2030 ($ million)
Data Table on Automobile - Market size and forecast 2025-2030 ($ million)
Chart on Automobile - Year-over-year growth 2025-2030 (%)
Data Table on Automobile - Year-over-year growth 2025-2030 (%)

8.6 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

8.7 Market opportunity by Application

Market opportunity by Application ($ million)
Data Table on Market opportunity by Application ($ million)

9. Market Segmentation by Product

9.1 Market segments

Chart on Product - Market share 2025-2030 (%)
Data Table on Product - Market share 2025-2030 (%)

9.2 Comparison by Product

Chart on Comparison by Product
Data Table on Comparison by Product

9.3 Polyethylene - Market size and forecast 2025-2030

Chart on Polyethylene - Market size and forecast 2025-2030 ($ million)
Data Table on Polyethylene - Market size and forecast 2025-2030 ($ million)
Chart on Polyethylene - Year-over-year growth 2025-2030 (%)
Data Table on Polyethylene - Year-over-year growth 2025-2030 (%)

9.4 Polypropylene - Market size and forecast 2025-2030

Chart on Polypropylene - Market size and forecast 2025-2030 ($ million)
Data Table on Polypropylene - Market size and forecast 2025-2030 ($ million)
Chart on Polypropylene - Year-over-year growth 2025-2030 (%)
Data Table on Polypropylene - Year-over-year growth 2025-2030 (%)

9.5 Polyvinyl chloride - Market size and forecast 2025-2030

Chart on Polyvinyl chloride - Market size and forecast 2025-2030 ($ million)
Data Table on Polyvinyl chloride - Market size and forecast 2025-2030 ($ million)
Chart on Polyvinyl chloride - Year-over-year growth 2025-2030 (%)
Data Table on Polyvinyl chloride - Year-over-year growth 2025-2030 (%)

9.6 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

9.7 Market opportunity by Product

Market opportunity by Product ($ million)
Data Table on Market opportunity by Product ($ million)

10. Market Segmentation by Technology

10.1 Market segments

Chart on Technology - Market share 2025-2030 (%)
Data Table on Technology - Market share 2025-2030 (%)

10.2 Comparison by Technology

Chart on Comparison by Technology
Data Table on Comparison by Technology

10.3 Hydraulic - Market size and forecast 2025-2030

Chart on Hydraulic - Market size and forecast 2025-2030 ($ million)
Data Table on Hydraulic - Market size and forecast 2025-2030 ($ million)
Chart on Hydraulic - Year-over-year growth 2025-2030 (%)
Data Table on Hydraulic - Year-over-year growth 2025-2030 (%)

10.4 Electric - Market size and forecast 2025-2030

Chart on Electric - Market size and forecast 2025-2030 ($ million)
Data Table on Electric - Market size and forecast 2025-2030 ($ million)
Chart on Electric - Year-over-year growth 2025-2030 (%)
Data Table on Electric - Year-over-year growth 2025-2030 (%)

10.5 Hybrid - Market size and forecast 2025-2030

Chart on Hybrid - Market size and forecast 2025-2030 ($ million)
Data Table on Hybrid - Market size and forecast 2025-2030 ($ million)
Chart on Hybrid - Year-over-year growth 2025-2030 (%)
Data Table on Hybrid - Year-over-year growth 2025-2030 (%)

10.6 Market opportunity by Technology

Market opportunity by Technology ($ million)
Data Table on Market opportunity by Technology ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.3.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.3.2 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.3.3 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.3.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.3.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.3.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.4 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.4.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.4.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.4.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.5 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.5.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.5.2 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.5.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.5.4 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.5.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.5.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.6 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.7 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.7.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.7.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.7.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.7.4 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.7.5 Egypt - Market size and forecast 2025-2030

Chart on Egypt - Market size and forecast 2025-2030 ($ million)
Data Table on Egypt - Market size and forecast 2025-2030 ($ million)
Chart on Egypt - Year-over-year growth 2025-2030 (%)
Data Table on Egypt - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Proliferation of lightweight components in automotive sector
Expansion of packaging industry driven by consumer demand
Continuous innovation in polymer technology and manufacturing processes

13.2 Market challenges

Heightened environmental scrutiny and regulatory pressures
Volatility in raw material pricing and supply chain instability
High initial tooling investment and economic uncertainties

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Shift towards sustainable and circular economy practices
Integration of digitalization and industry 4.0 principles
Rising demand for high-performance and specialized polymers

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Amcor Plc

Amcor Plc - Overview
Amcor Plc - Business segments
Amcor Plc - Key news
Amcor Plc - Key offerings
Amcor Plc - Segment focus
SWOT

15.5 Crescent Industries Inc.

Crescent Industries Inc. - Overview
Crescent Industries Inc. - Product / Service
Crescent Industries Inc. - Key offerings
SWOT

15.6 EVCO Plastics

EVCO Plastics - Overview
EVCO Plastics - Product / Service
EVCO Plastics - Key offerings
SWOT

15.7 Gerresheimer AG

Gerresheimer AG - Overview
Gerresheimer AG - Business segments
Gerresheimer AG - Key offerings
Gerresheimer AG - Segment focus
SWOT

15.8 Hongrita Mold Ltd.

Hongrita Mold Ltd. - Overview
Hongrita Mold Ltd. - Product / Service
Hongrita Mold Ltd. - Key offerings
SWOT

15.9 Jones Plastic and Engineering Co.

Jones Plastic and Engineering Co. - Overview
Jones Plastic and Engineering Co. - Product / Service
Jones Plastic and Engineering Co. - Key offerings
SWOT

15.10 Mack Molding Co.

Mack Molding Co. - Overview
Mack Molding Co. - Product / Service
Mack Molding Co. - Key offerings
SWOT

15.11 MMI Engineered Solutions

MMI Engineered Solutions - Overview
MMI Engineered Solutions - Product / Service
MMI Engineered Solutions - Key offerings
SWOT

15.12 Molded Devices Inc.

Molded Devices Inc. - Overview
Molded Devices Inc. - Product / Service
Molded Devices Inc. - Key offerings
SWOT

15.13 Nolato AB

Nolato AB - Overview
Nolato AB - Business segments
Nolato AB - Key offerings
Nolato AB - Segment focus
SWOT

15.14 Proto Labs Inc.

Proto Labs Inc. - Overview
Proto Labs Inc. - Business segments
Proto Labs Inc. - Key offerings
Proto Labs Inc. - Segment focus
SWOT

15.15 PTI Engineered Plastics Inc.

PTI Engineered Plastics Inc. - Overview
PTI Engineered Plastics Inc. - Product / Service
PTI Engineered Plastics Inc. - Key offerings
SWOT

15.16 Rosti Group AB

Rosti Group AB - Overview
Rosti Group AB - Product / Service
Rosti Group AB - Key offerings
SWOT

15.17 Seaway Plastics Engineering LLC

Seaway Plastics Engineering LLC - Overview
Seaway Plastics Engineering LLC - Product / Service
Seaway Plastics Engineering LLC - Key offerings
SWOT

15.18 The Rodon Group

The Rodon Group - Overview
The Rodon Group - Product / Service
The Rodon Group - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Injection Molded Plastics market growth will increase by USD 105199.0 million during 2026-2030.

The Injection Molded Plastics market is expected to grow at a CAGR of 4.6% during 2026-2030.

Injection Molded Plastics market is segmented by Application (Packaging, Consumer goods, Automobile, Others) Product (Polyethylene, Polypropylene, Polyvinyl chloride, Others) Technology (Hydraulic, Electric, Hybrid)

Accurate Molded Products, Amcor Plc, Crescent Industries Inc., EVCO Plastics, Extreme Molding LLC, Gerresheimer AG, Hongrita Mold Ltd., Jones Plastic and Engineering Co., Mack Molding Co., MMI Engineered Solutions, Molded Devices Inc., MSI Mold Builders, Nolato AB, Proto Labs Inc., PTI Engineered Plastics Inc., Revere Plastics Systems LLC, Rosti Group AB, Seaway Plastics Engineering LLC, Sungplastic, The Rodon Group are a few of the key vendors in the Injection Molded Plastics market.

APAC will register the highest growth rate of 54.4% among the other regions. Therefore, the Injection Molded Plastics market in APAC is expected to garner significant business opportunities for the vendors during the forecast period.

China, India, Japan, South Korea, Australia, Indonesia, US, Canada, Mexico, Germany, Italy, France, UK, Spain, The Netherlands, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Turkey, Egypt

  • Proliferation of lightweight components in automotive sector is the driving factor this market.

The Injection Molded Plastics market vendors should focus on grabbing business opportunities from the Application segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
