Logistics Services Software Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), APAC (China, Japan, and India), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

Logistics Services Software Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), APAC (China, Japan, and India), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

Published: Oct 2026 307 Pages SKU: IRTNTR40172

Market Overview at a Glance

$7.69 B
Market Opportunity
8.3%
CAGR 2025 - 2030
33.1%
North America Growth
$4.56 B
Retail and e-commerce segment 2024

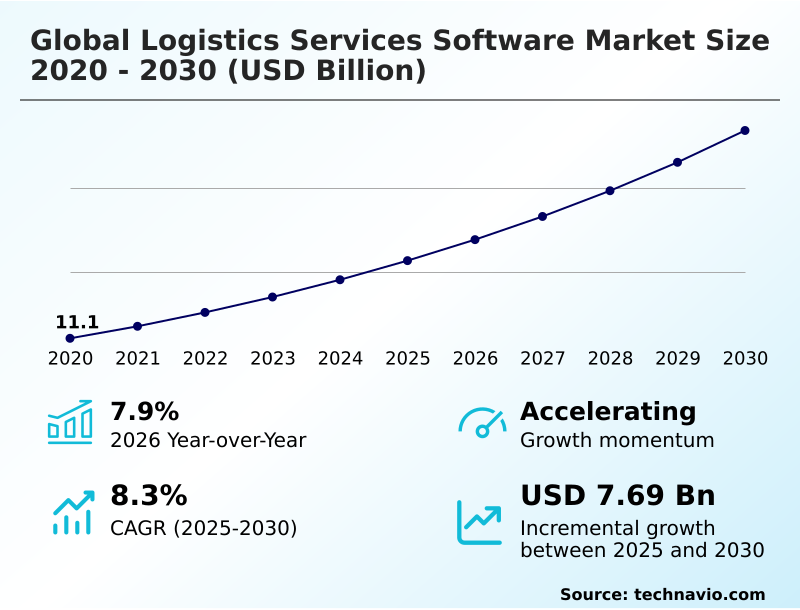
Logistics Services Software Market Size 2026-2030

The logistics services software market size is valued to increase by USD 7.69 billion, at a CAGR of 8.3% from 2025 to 2030. Proliferation of AI and machine learning in predictive operations will drive the logistics services software market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 33.1% growth during the forecast period.
  • By End-user - Retail and e-commerce segment was valued at USD 4.56 billion in 2024
  • By Deployment - On-premises segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 12.28 billion
  • Market Future Opportunities: USD 7.69 billion
  • CAGR from 2025 to 2030 : 8.3%

Market Summary

  • The Logistics Services Software Market operates as the critical digital backbone for supply chain execution, facilitating the seamless coordination of multi-modal freight and decentralized inventory. Enterprise shippers consistently transition toward modular, cloud-hosted architectures to secure operational transparency and mitigate transit volatility.
  • In a practical supply chain scenario, a third-party logistics provider leveraging digital tracking platforms can rapidly identify transit bottlenecks and reroute shipments before costly port delays occur. Organizations utilizing these predictive orchestration engines report a 25% improvement in on-time delivery rates compared to those relying on fragmented legacy platforms.
  • The proliferation of artificial intelligence and machine learning in predictive operations continuously propels market adoption, enabling proactive disruption modeling. Conversely, persistent cybersecurity exposures across interconnected logistics networks pose a substantial challenge, as distributed API endpoints increase the vulnerability of sensitive commercial data. Advanced software design remains essential to overcoming these integration barriers.
  • Consequently, businesses prioritize unified ecosystems capable of delivering high-fidelity visibility while maintaining strict digital security compliance across complex international trade corridors.

What will be the Size of the Logistics Services Software Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Logistics Services Software Market Segmented?

The logistics services software industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • End-user
    • Retail and e-commerce
    • Manufacturing
    • Healthcare
    • Automotive
    • Others
  • Deployment
    • On-premises
    • Cloud-based
  • Type
    • Transportation management
    • Warehouse management
    • Asset and fleet management
    • Data management
    • Others
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Turkey
      • Israel
    • South America
      • Brazil
      • Argentina
      • Chile

By End-user Insights

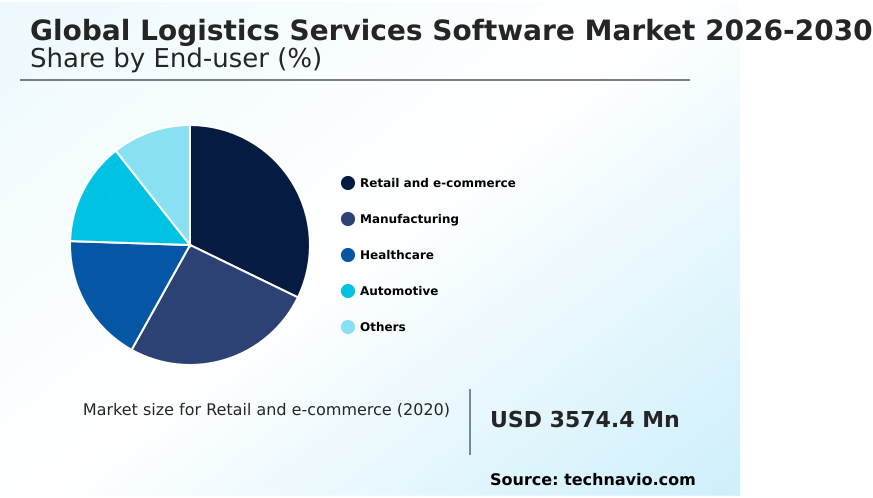
The retail and e-commerce segment is estimated to witness significant growth during the forecast period.

The retail and e-commerce end-user segment commands extensive adoption of advanced digital solutions as omnichannel fulfillment strategies continuously reshape fulfillment operations. Retail operators increasingly deploy transportation management systems alongside warehouse execution tools to navigate escalating order volumes.

Modern platforms orchestrate last-mile dispatching workflows seamlessly, enabling businesses to fulfill same-day delivery mandates with high precision. By integrating intelligent task interleaving and automated inventory slotting, enterprise merchants can dynamically rebalance stock across urban distribution nodes.

The implementation of automated order wave planning and multi-carrier integration directly enhances operational agility, yielding a 15% reduction in overall order processing times.

This targeted deployment of sophisticated cloud-native logistics platforms allows retail enterprises to maintain zero-defect supply chain execution, minimizing transit delays while simultaneously elevating customer service reliability across decentralized fulfillment networks.
Get Free Sample

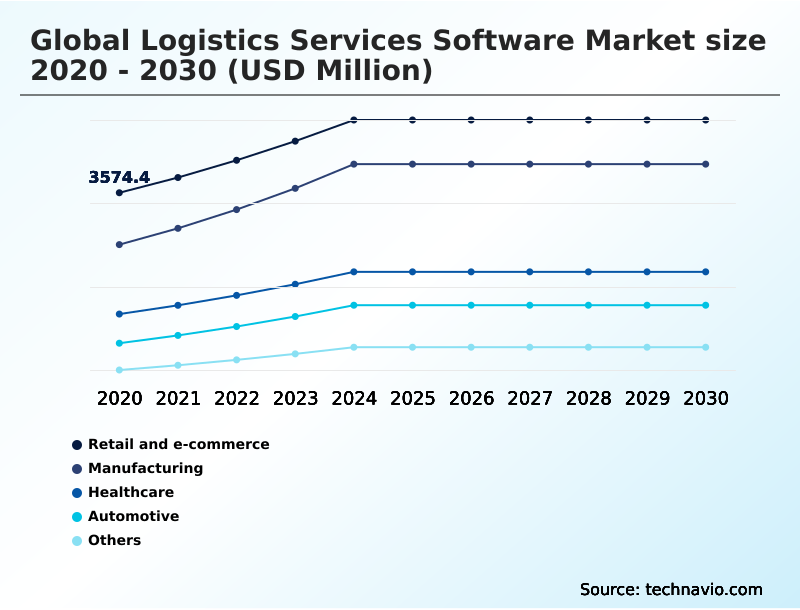
The Retail and e-commerce segment was valued at USD 4.56 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 33.1% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
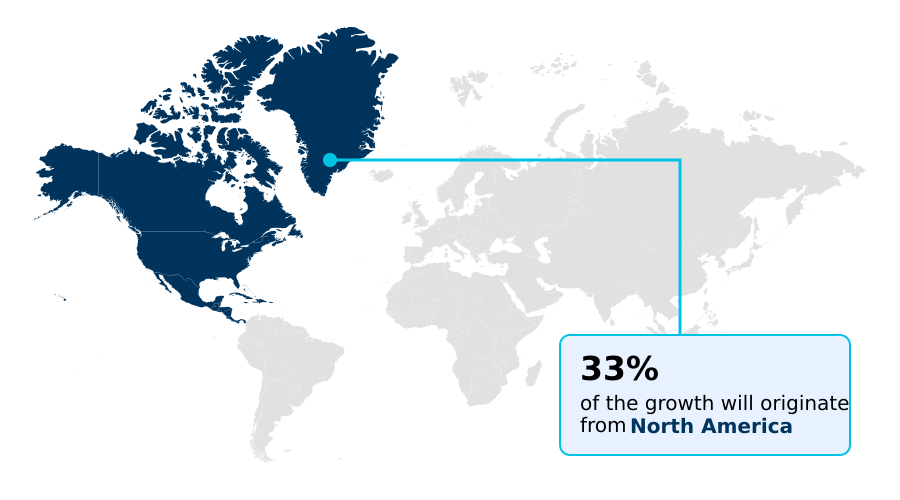
See How Logistics Services Software Market Demand is Rising in North America Get Free Sample

The regional adoption of the Logistics Services Software Market varies significantly based on digital infrastructure maturity and localized trade compliance requirements.

North America demonstrates advanced integration of supply chain orchestration systems, achieving a 30% higher penetration rate of automated customs clearance algorithms compared to Europe.

This rapid adoption is driven by stringent electronic logging device compliance and high consumer demand for rapid fulfillment. In response, North American fleet operators heavily utilize real-time fleet telematics to ensure cross-border freight tracking reliability and optimize multimodal transit capacity.

Conversely, European enterprises prioritize sustainability mandates, leading to a 25% faster deployment of carbon-aware routing algorithms and environmental footprint tracking tools.

European businesses must adapt to strict Scope 3 emissions reporting, compelling the rapid procurement of global trade management systems equipped with real-time regulatory compliance engines. These structural differences dictate how regional supply chains mitigate fuel expenditures effectively.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The evolution of the Logistics Services Software Market is deeply intertwined with the necessity to optimize complex, globalized fulfillment networks. As enterprise shippers seek to modernize legacy operations, the implementation of cloud based automated transportation management becomes a critical operational requirement.
  • These sophisticated platforms empower logistics intermediaries to seamlessly orchestrate carrier selection, yielding a measurable 15% improvement in dock scheduling efficiency compared to traditional manual dispatch methods. To navigate international trade corridors effectively, businesses increasingly rely on cross border dynamic customs clearance systems, which automatically validate electronic tax invoices and minimize terminal dwell times.
  • Furthermore, maintaining granular visibility over shifting supply chain nodes is achieved through real time multi modal freight tracking, enabling dispatchers to proactively reroute shipments during unexpected weather or port disruptions. Within highly automated fulfillment centers, the deployment of autonomous warehouse robotics orchestration platforms ensures that inbound material handling and outbound order wave planning are synchronized perfectly, significantly reducing labor bottlenecks.
  • To further streamline delivery execution, enterprises leverage ai driven predictive route optimization software, which continuously analyzes live traffic telematics and fuel consumption rates. By prioritizing these highly integrated digital frameworks, corporate logistics operators can successfully mitigate transit volatility, enhance compliance accuracy, and sustain high-volume operational throughput across diverse geographic environments.
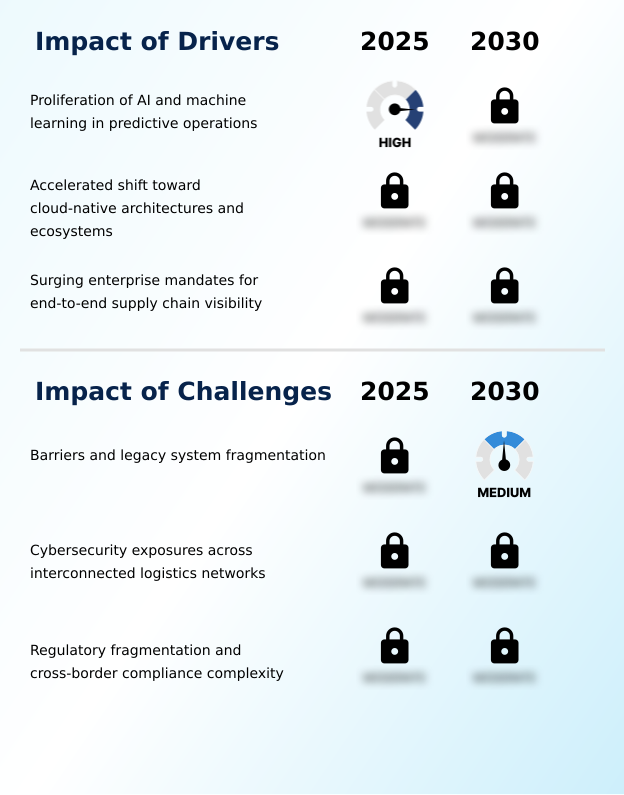
What are the key market drivers leading to the rise in the adoption of Logistics Services Software Industry?

  • The continuous proliferation of artificial intelligence and machine learning in predictive operations serves as a primary catalyst accelerating market expansion.

  • The accelerating enterprise mandate for end-to-end operational visibility serves as a primary catalyst driving the Logistics Services Software Market.
  • Modern fulfillment networks generate massive volumes of transit data, compelling businesses to adopt predictive demand analytics and automated load dispatches to optimize carrier allocation.
  • By leveraging real-time exception handling and predictive route optimization, logistics operators have reduced unplanned vehicle downtime by 30% and lowered overall energy use by 12%.
  • The pressing need to mitigate transit bottlenecks forces companies to deploy multi-modal disruption modeling alongside predictive maintenance analytics. This technological pivot allows dispatchers to dynamically reroute freight around congested ports using dynamic carrier dispatching, safeguarding customer service agreements.
  • Furthermore, managing industrial freight via sequence-in-line delivery models and monitoring assets through real-time battery degradation monitoring ensures that manufacturers maintain continuous production without suffering costly material shortages or automated material handling delays.

What are the market trends shaping the Logistics Services Software Industry?

  • The transition toward autonomous operational orchestration is rapidly emerging as a defining trend within the market, enabling organizations to seamlessly execute complex supply chain workflows without manual intervention.

  • The convergence of supply chain execution platforms into unified ecosystems fundamentally redefines the Logistics Services Software Market. Organizations are rapidly divesting from fragmented legacy systems to deploy continuous microservices-based updates via microservices-based cloud architectures, eliminating structural data silos. This technological consolidation provides single-pane-of-glass visibility, synchronizing inbound reception with outbound dispatching flawlessly.
  • By implementing unified data pipelines and agentic decision-making frameworks, enterprises have improved forecast accuracy by 18% and reduced cross-departmental communication delays by 22%. Furthermore, the adoption of edge-ai computer vision within yard management systems accelerates trailer processing speeds significantly. These integrated ecosystems empower third-party logistics providers to utilize dynamic customs clearance and automated electronic tax invoice validation concurrently.
  • Consequently, businesses gain the agility to manage reverse logistics engines efficiently, ensuring that complex freight movements remain compliant while sustaining high-velocity throughput.

What challenges does the Logistics Services Software Industry face during its growth?

  • Persistent technological barriers and the fragmentation of legacy systems represent critical restraints hindering widespread industry modernization.

  • Persistent legacy system fragmentation and pervasive architectural bottlenecks create formidable barriers within the Logistics Services Software Market. A substantial majority of global freight intermediaries continue to rely on localized, disconnected infrastructure that severely impedes real-time data synchronization. When organizations attempt to integrate modern autonomous mobile robots or electronic product code tracing systems, they encounter significant operational latency.
  • Overcoming these integration hurdles requires costly custom middleware, which increases administrative overhead by 25% and slows deployment timelines by 15%. Additionally, maintaining hours-of-service compliance and executing dangerous goods documentation workflows across disjointed platforms heightens the risk of regulatory penalties.
  • The inability to establish seamless api-first software design fundamentally undermines predictive network visibility, forcing logistics managers to execute reactive, manual automated freight auditing rather than leveraging predictive models. Consequently, calculating accurate freight costs via real-time tariff calculations and monitoring sensitive goods with cold-chain telemetry tracking becomes highly error-prone.

Exclusive Technavio Analysis on Customer Landscape

The logistics services software market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the logistics services software market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
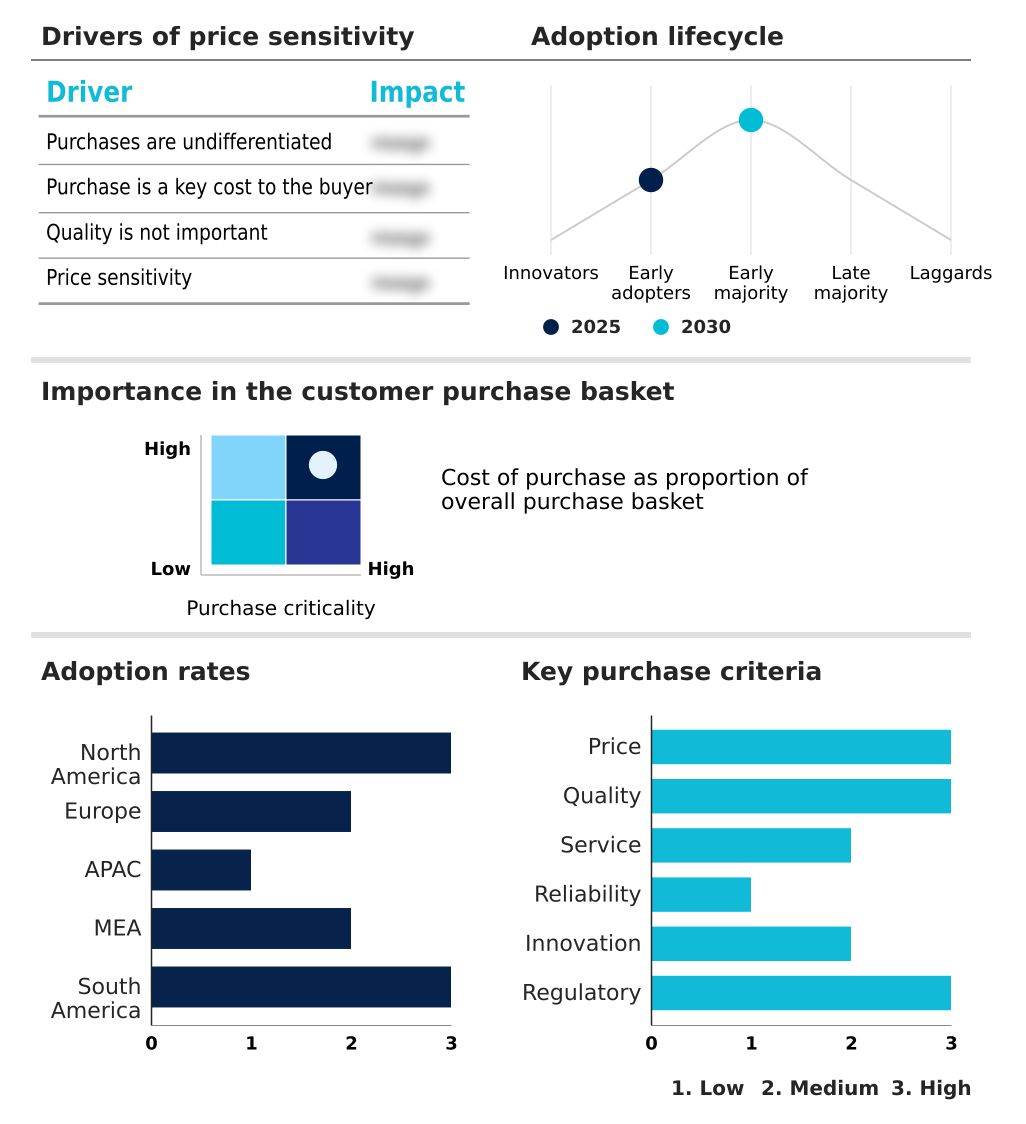
Customer Landscape of Logistics Services Software Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, logistics services software market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Aptean - The vendor provides comprehensive logistics services software featuring advanced transportation management and warehouse execution solutions designed to optimize freight and inventory orchestration seamlessly across multi-modal networks.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Aptean
  • Blue Yonder Group Inc.
  • Descartes Systems Group Inc.
  • E2open Parent Holdings Inc.
  • Epicor Software Corp.
  • Extensiv
  • FarEye Technologies Pvt. Ltd.
  • Generix Group
  • Infor Inc.
  • Magaya Corp.
  • Manhattan Associates Inc.
  • MercuryGate International Inc.
  • Oracle Corp.
  • project44
  • Ramco Systems Ltd.
  • SAP SE
  • Shipwell
  • Tecsys Inc.
  • WiseTech Global Ltd.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Logistics services software market

  • In the Application Software industry, the integration of generative AI into enterprise workflow automation has reduced manual data entry bottlenecks, directly impacting Logistics Services Software demand by accelerating the adoption of continuous microservices-based updates and automated load dispatches.
  • The proliferation of zero-trust security architectures across cloud-based enterprise platforms has fortified decentralized data exchange, increasing reliance on Logistics Services Software that utilizes microservices-based cloud architectures and single-pane-of-glass visibility to safeguard unified data pipelines.
  • Stringent corporate sustainability reporting mandates such as the EU Corporate Sustainability Reporting Directive have forced global enterprises to measure Scope 3 emissions, driving urgent procurement of Logistics Services Software equipped with environmental footprint tracking and multi-modal disruption modeling.
  • The widespread deployment of industrial IoT sensor networks in manufacturing environments has generated massive telemetry datasets, amplifying the necessity for Logistics Services Software capable of real-time exception handling and edge-ai computer vision to maintain zero-defect supply chain execution.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Logistics Services Software Market insights. See full methodology.

Market Scope
Page number 307
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 8.3%
Market growth 2026-2030 USD 7689.9 million
Market structure Fragmented
YoY growth 2025-2026(%) 7.9%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Saudi Arabia, UAE, South Africa, Turkey, Israel, Brazil, Argentina and Chile
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Logistics Services Software Market is rapidly evolving from fragmented recording tools into predictive, autonomous execution ecosystems. Enterprise operators are accelerating their transition toward centralized platforms to secure granular oversight across disparate multi-modal transport corridors. A defining strategic shift is the widespread adoption of agentic decision-making frameworks, which fundamentally alters how boardrooms approach operational budgeting and structural risk mitigation.
  • By embedding these intelligent frameworks into daily workflows, companies have achieved a 30% reduction in manual processing time for complex freight auditing. This autonomy directly empowers dispatchers to utilize automated freight auditing and real-time tariff calculations without administrative delays. Furthermore, stringent environmental mandates compel organizations to deploy carbon-aware routing algorithms, effectively linking corporate compliance directly to transit routing decisions.
  • To manage specialized commodities, industries leverage cold-chain telemetry tracking to prevent high-value spoilage during long-haul transit. The integration of automated material handling and intelligent task interleaving within distribution centers further maximizes floor space utilization. Consequently, businesses that implement these advanced digital infrastructures achieve superior supply chain resilience, enabling precise execution despite continuous global trade volatility.

What are the Key Data Covered in this Logistics Services Software Market Research and Growth Report?

  • What is the expected growth of the Logistics Services Software Market between 2026 and 2030?

    • USD 7.69 billion, at a CAGR of 8.3%

  • What segmentation does the market report cover?

    • The report is segmented by End-user (Retail and e-commerce, Manufacturing, Healthcare, Automotive, and Others), Deployment (On-premises, and Cloud-based), Type (Transportation management, Warehouse management, Asset and fleet management, Data management, and Others) and Geography (North America, Europe, APAC, Middle East and Africa, South America)

  • Which regions are analyzed in the report?

    • North America, Europe, APAC, Middle East and Africa and South America

  • What are the key growth drivers and market challenges?

    • Proliferation of AI and machine learning in predictive operations, Barriers and legacy system fragmentation

  • Who are the major players in the Logistics Services Software Market?

    • Aptean, Blue Yonder Group Inc., Descartes Systems Group Inc., E2open Parent Holdings Inc., Epicor Software Corp., Extensiv, FarEye Technologies Pvt. Ltd., Generix Group, Infor Inc., Magaya Corp., Manhattan Associates Inc., MercuryGate International Inc., Oracle Corp., project44, Ramco Systems Ltd., SAP SE, Shipwell, Tecsys Inc. and WiseTech Global Ltd.

Market Research Insights

  • The Logistics Services Software Market is undergoing rapid modernization as enterprises prioritize digital agility to counter supply chain volatility. By leveraging api-first software design and single-pane-of-glass visibility, organizations transition from reactive tracking to proactive network orchestration. Companies deploying dynamic carrier dispatching algorithms have achieved a 20% reduction in empty-mile transit, maximizing fleet asset utilization.
  • Furthermore, the integration of real-time exception handling allows operators to mitigate port congestion effectively, improving overall fulfillment throughput by 18%. Implementing continuous microservices-based updates ensures that compliance and security protocols remain resilient without requiring operational downtime. These technological shifts empower businesses to execute highly complex omnichannel fulfillment strategies while substantially lowering administrative overhead and enhancing transit reliability.

We can help! Our analysts can customize this logistics services software market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Deployment
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Logistics Services Software Market 2020 - 2024

Historic Market Size - Data Table on Global Logistics Services Software Market 2020 - 2024 ($ million)

5.2 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.3 Deployment segment analysis 2020 - 2024

Historic Market Size - Deployment Segment 2020 - 2024 ($ million)

5.4 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI in Global Logistics Services Software Market

6.2 Impact of Geopolitical Conflicts on Global Logistics Services Software Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by End-user

8.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

8.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

8.3 Retail and e-commerce - Market size and forecast 2025-2030

Chart on Retail and e-commerce - Market size and forecast 2025-2030 ($ million)
Data Table on Retail and e-commerce - Market size and forecast 2025-2030 ($ million)
Chart on Retail and e-commerce - Year-over-year growth 2025-2030 (%)
Data Table on Retail and e-commerce - Year-over-year growth 2025-2030 (%)

8.4 Manufacturing - Market size and forecast 2025-2030

Chart on Manufacturing - Market size and forecast 2025-2030 ($ million)
Data Table on Manufacturing - Market size and forecast 2025-2030 ($ million)
Chart on Manufacturing - Year-over-year growth 2025-2030 (%)
Data Table on Manufacturing - Year-over-year growth 2025-2030 (%)

8.5 Healthcare - Market size and forecast 2025-2030

Chart on Healthcare - Market size and forecast 2025-2030 ($ million)
Data Table on Healthcare - Market size and forecast 2025-2030 ($ million)
Chart on Healthcare - Year-over-year growth 2025-2030 (%)
Data Table on Healthcare - Year-over-year growth 2025-2030 (%)

8.6 Automotive - Market size and forecast 2025-2030

Chart on Automotive - Market size and forecast 2025-2030 ($ million)
Data Table on Automotive - Market size and forecast 2025-2030 ($ million)
Chart on Automotive - Year-over-year growth 2025-2030 (%)
Data Table on Automotive - Year-over-year growth 2025-2030 (%)

8.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

8.8 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

9. Market Segmentation by Deployment

9.1 Market segments

Chart on Deployment - Market share 2025-2030 (%)
Data Table on Deployment - Market share 2025-2030 (%)

9.2 Comparison by Deployment

Chart on Comparison by Deployment
Data Table on Comparison by Deployment

9.3 On-premises - Market size and forecast 2025-2030

Chart on On-premises - Market size and forecast 2025-2030 ($ million)
Data Table on On-premises - Market size and forecast 2025-2030 ($ million)
Chart on On-premises - Year-over-year growth 2025-2030 (%)
Data Table on On-premises - Year-over-year growth 2025-2030 (%)

9.4 Cloud-based - Market size and forecast 2025-2030

Chart on Cloud-based - Market size and forecast 2025-2030 ($ million)
Data Table on Cloud-based - Market size and forecast 2025-2030 ($ million)
Chart on Cloud-based - Year-over-year growth 2025-2030 (%)
Data Table on Cloud-based - Year-over-year growth 2025-2030 (%)

9.5 Market opportunity by Deployment

Market opportunity by Deployment ($ million)
Data Table on Market opportunity by Deployment ($ million)

10. Market Segmentation by Type

10.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

10.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

10.3 Transportation management - Market size and forecast 2025-2030

Chart on Transportation management - Market size and forecast 2025-2030 ($ million)
Data Table on Transportation management - Market size and forecast 2025-2030 ($ million)
Chart on Transportation management - Year-over-year growth 2025-2030 (%)
Data Table on Transportation management - Year-over-year growth 2025-2030 (%)

10.4 Warehouse management - Market size and forecast 2025-2030

Chart on Warehouse management - Market size and forecast 2025-2030 ($ million)
Data Table on Warehouse management - Market size and forecast 2025-2030 ($ million)
Chart on Warehouse management - Year-over-year growth 2025-2030 (%)
Data Table on Warehouse management - Year-over-year growth 2025-2030 (%)

10.5 Asset and fleet management - Market size and forecast 2025-2030

Chart on Asset and fleet management - Market size and forecast 2025-2030 ($ million)
Data Table on Asset and fleet management - Market size and forecast 2025-2030 ($ million)
Chart on Asset and fleet management - Year-over-year growth 2025-2030 (%)
Data Table on Asset and fleet management - Year-over-year growth 2025-2030 (%)

10.6 Data management - Market size and forecast 2025-2030

Chart on Data management - Market size and forecast 2025-2030 ($ million)
Data Table on Data management - Market size and forecast 2025-2030 ($ million)
Chart on Data management - Year-over-year growth 2025-2030 (%)
Data Table on Data management - Year-over-year growth 2025-2030 (%)

10.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

10.8 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.5.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.6 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.6.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.4 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.6.5 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.7.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.7.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.7.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Proliferation of AI and machine learning in predictive operations
Accelerated shift toward cloud-native architectures and ecosystems
Surging enterprise mandates for end-to-end supply chain visibility

13.2 Market challenges

Barriers and legacy system fragmentation
Cybersecurity exposures across interconnected logistics networks
Regulatory fragmentation and cross-border compliance complexity

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Transition toward autonomous operational orchestration
Convergence of supply chain execution platforms into unified ecosystems
Integration of carbon auditability and autonomous trade compliance engine

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Aptean

Aptean - Overview
Aptean - Product / Service
Aptean - Key offerings
SWOT

15.5 Blue Yonder Group Inc.

Blue Yonder Group Inc. - Overview
Blue Yonder Group Inc. - Product / Service
Blue Yonder Group Inc. - Key offerings
SWOT

15.6 Descartes Systems Group Inc.

Descartes Systems Group Inc. - Overview
Descartes Systems Group Inc. - Business segments
Descartes Systems Group Inc. - Key offerings
Descartes Systems Group Inc. - Segment focus
SWOT

15.7 E2open Parent Holdings Inc.

E2open Parent Holdings Inc. - Overview
E2open Parent Holdings Inc. - Product / Service
E2open Parent Holdings Inc. - Key offerings
SWOT

15.8 Epicor Software Corp.

Epicor Software Corp. - Overview
Epicor Software Corp. - Product / Service
Epicor Software Corp. - Key offerings
SWOT

15.9 Extensiv

Extensiv - Overview
Extensiv - Product / Service
Extensiv - Key offerings
SWOT

15.10 Generix Group

Generix Group - Overview
Generix Group - Product / Service
Generix Group - Key offerings
SWOT

15.11 Infor Inc.

Infor Inc. - Overview
Infor Inc. - Product / Service
Infor Inc. - Key offerings
SWOT

15.12 Manhattan Associates Inc.

Manhattan Associates Inc. - Overview
Manhattan Associates Inc. - Business segments
Manhattan Associates Inc. - Key offerings
Manhattan Associates Inc. - Segment focus
SWOT

15.13 Oracle Corp.

Oracle Corp. - Overview
Oracle Corp. - Business segments
Oracle Corp. - Key news
Oracle Corp. - Key offerings
Oracle Corp. - Segment focus
SWOT

15.14 Ramco Systems Ltd.

Ramco Systems Ltd. - Overview
Ramco Systems Ltd. - Business segments
Ramco Systems Ltd. - Key offerings
Ramco Systems Ltd. - Segment focus
SWOT

15.15 SAP SE

SAP SE - Overview
SAP SE - Business segments
SAP SE - Key news
SAP SE - Key offerings
SAP SE - Segment focus
SWOT

15.16 Shipwell

Shipwell - Overview
Shipwell - Product / Service
Shipwell - Key offerings
SWOT

15.17 Tecsys Inc.

Tecsys Inc. - Overview
Tecsys Inc. - Product / Service
Tecsys Inc. - Key offerings
SWOT

15.18 WiseTech Global Ltd.

WiseTech Global Ltd. - Overview
WiseTech Global Ltd. - Product / Service
WiseTech Global Ltd. - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Logistics Services Software market growth will increase by USD 7689.9 million during 2026-2030.

The Logistics Services Software market is expected to grow at a CAGR of 8.3% during 2026-2030.

Logistics Services Software market is segmented by End-user (Retail and e-commerce, Manufacturing, Healthcare, Automotive, Others) Deployment (On-premises, Cloud-based) Type (Transportation management, Warehouse management, Asset and fleet management, Data management, Others)

Aptean, Blue Yonder Group Inc., Descartes Systems Group Inc., E2open Parent Holdings Inc., Epicor Software Corp., Extensiv, FarEye Technologies Pvt. Ltd., Generix Group, Infor Inc., Magaya Corp., Manhattan Associates Inc., MercuryGate International Inc., Oracle Corp., project44, Ramco Systems Ltd., SAP SE, Shipwell, Tecsys Inc., WiseTech Global Ltd. are a few of the key vendors in the Logistics Services Software market.

North America will register the highest growth rate of 33.1% among the other regions. Therefore, the Logistics Services Software market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Saudi Arabia, UAE, South Africa, Turkey, Israel, Brazil, Argentina, Chile

  • Proliferation of AI and machine learning in predictive operations is the driving factor this market.

The Logistics Services Software market vendors should focus on grabbing business opportunities from the End-user segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
