


US Neurodiagnostic And Monitoring Devices Market Size 2026-2030
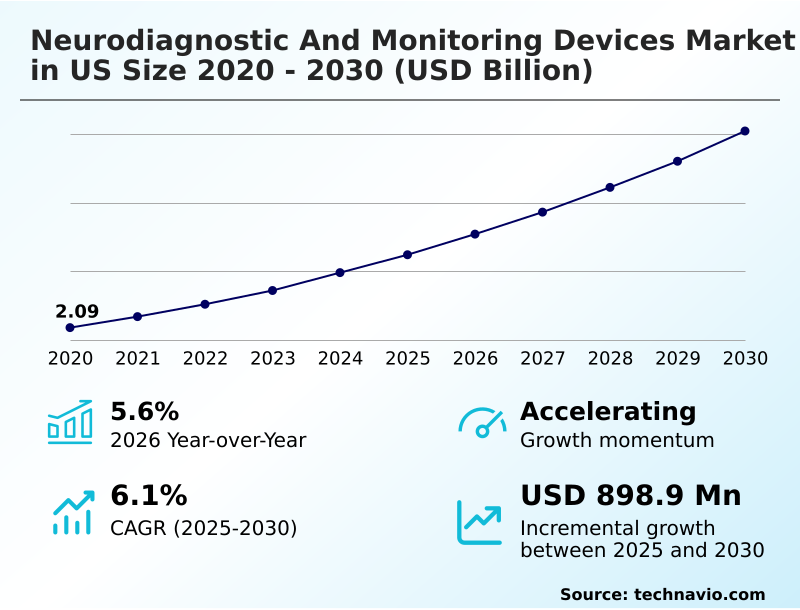
The us neurodiagnostic and monitoring devices market size is valued to increase by USD 898.9 million, at a CAGR of 6.1% from 2025 to 2030. Escalating incidence of acute neurological conditions and rapid bedside adoption will drive the us neurodiagnostic and monitoring devices market.
Major Market Trends & Insights
- By Application - Stroke segment was valued at USD 789.2 million in 2024
- By Product - ICP monitoring devices segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 1.43 billion
- Market Future Opportunities: USD 898.9 million
- CAGR from 2025 to 2030 : 6.1%
Market Summary
- The Neurodiagnostic And Monitoring Devices Market in US experiences robust operational shifts as clinical institutions transition from intermittent assessments to continuous, high-fidelity neural surveillance. An escalating volume of high-risk spinal fusions and neurovascular interventions acts as a primary catalyst, compelling hospitals to integrate continuous intraoperative neurophysiological monitoring to prevent permanent iatrogenic damage.
- Consequently, supply chain managers in acute care networks are standardizing procurement around modular diagnostic suites to streamline inventory and reduce consumable waste. This strategic consolidation has improved equipment utilization rates by 15% across major healthcare facilities. However, stringent payer pre-authorization mandates and complex coding frameworks present persistent administrative challenges, frequently delaying capital allocations for advanced hardware upgrades.
- To circumvent these financial barriers, facilities prioritize systems offering autonomous interpretation software and sensor fusion integration, which drastically reduce the workload on specialized neurophysiologists. Ultimately, the systemic convergence of automated cerebral blood flow assessments and noninvasive telemetry establishes a new benchmark for proactive brain preservation across intensive care units.
What will be the Size of the US Neurodiagnostic And Monitoring Devices Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the US Neurodiagnostic And Monitoring Devices Market Segmented?
The us neurodiagnostic and monitoring devices industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Application
- Stroke
- Migraine
- Epilepsy
- Parkinsons disease
- Ischemic stroke
- Product
- ICP monitoring devices
- EEG devices
- EMG devices
- Others
- End-user
- Hospitals
- Clinics
- Laboratories
- Technology
- Non-invasive monitoring
- Invasive monitoring
- Geography
- North America
- US
- North America
By Application Insights
The stroke segment is estimated to witness significant growth during the forecast period.
The stroke segment establishes a dominant baseline in the Neurodiagnostic And Monitoring Devices Market in US 2026-2030, driven by the critical necessity for rapid electrophysiological evaluation during acute neurovascular incidents.
Medical practitioners rely on continuous brain function trending to detect silent neurological events that conventional assessments frequently miss. By deploying advanced electroencephalography algorithms and cerebral oximetry, acute care networks can identify microvascular failures and optimize cerebral perfusion targets.
This proactive intervention approach has demonstrably improved patient outcomes, with continuous monitoring reducing diagnostic delays by up to 25% across emergency departments. Furthermore, integrating point of care evaluation alongside wireless data transmission streamlines clinical workflows.
Automated pattern recognition helps isolate ischemic events early, fundamentally shifting neurocritical care from retrospective observation to real-time preservation.
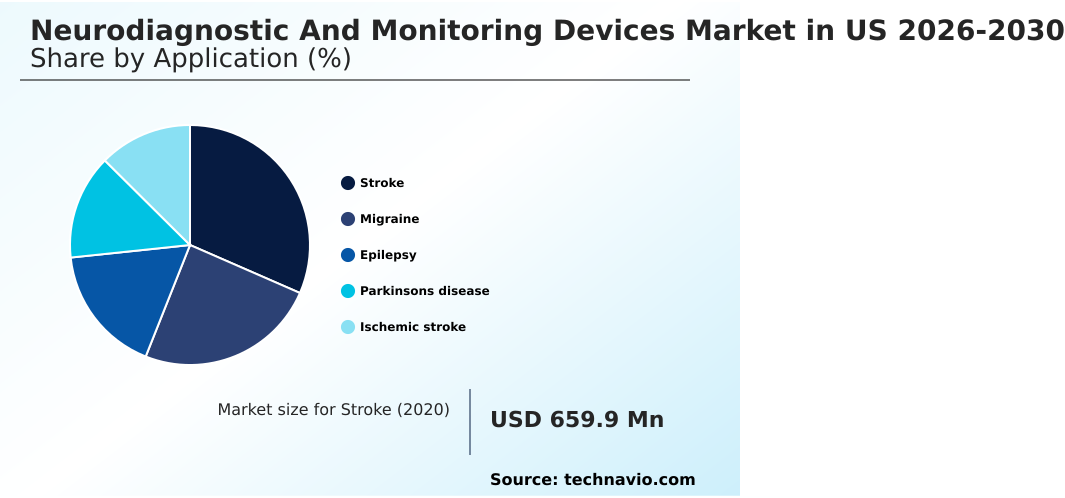
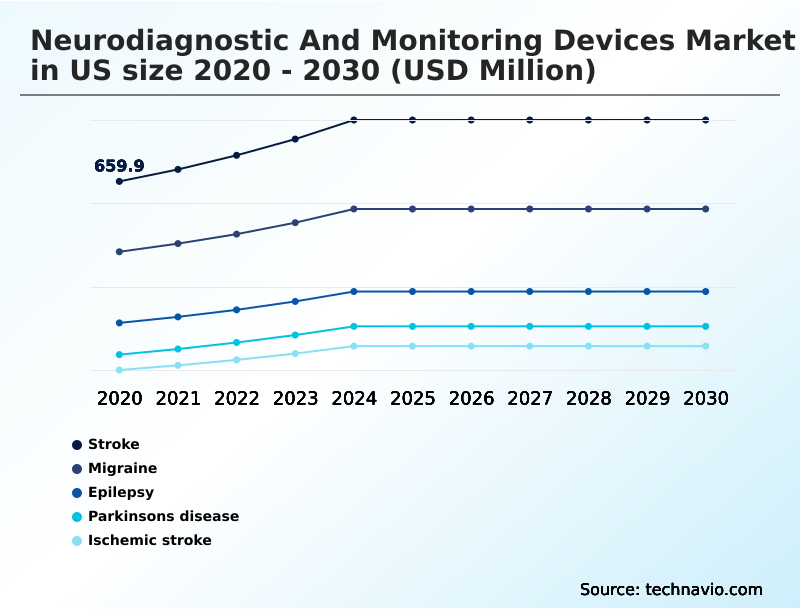
The Stroke segment was valued at USD 789.2 million in 2024 and showed a gradual increase during the forecast period.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The structural evolution of the Neurodiagnostic And Monitoring Devices Market in US reflects a deep institutional commitment to precision medicine and continuous physiological tracking. Clinical guidelines increasingly mandate continuous intraoperative neurophysiological monitoring during complex cardiovascular and spinal surgeries, establishing a rigorous standard for preventing neurological deficits.
- This procedural shift influences supply chain planning, as hospital administrators secure long-term procurement contracts for modular sensory equipment to ensure uninterrupted operational readiness. Simultaneously, the demand for automated cerebral blood flow assessments has expanded rapidly across comprehensive stroke centers, allowing critical care teams to maintain optimal neurovascular regulation during acute emergencies.
- As decentralized care models gain prominence, outpatient clinics demonstrate a 40% higher adoption rate of portable bedside neurological diagnostic apparatus compared to traditional inpatient wards, significantly reducing facility overhead while maintaining high diagnostic throughput. Furthermore, intensive care units actively transition toward noninvasive cerebral oxygenation tissue tracking to monitor microvascular imbalances without the inherent risks of surgical probe insertion.
- This emphasis on non-invasive modalities extends to ambulatory environments, where the deployment of wireless ambulatory cortical activity tracking provides neurologists with objective, multiday physiological datasets. By aligning capital expenditure with these advanced recording platforms, healthcare networks ensure precise data acquisition, elevate patient compliance, and fundamentally optimize their diagnostic service delivery architectures.
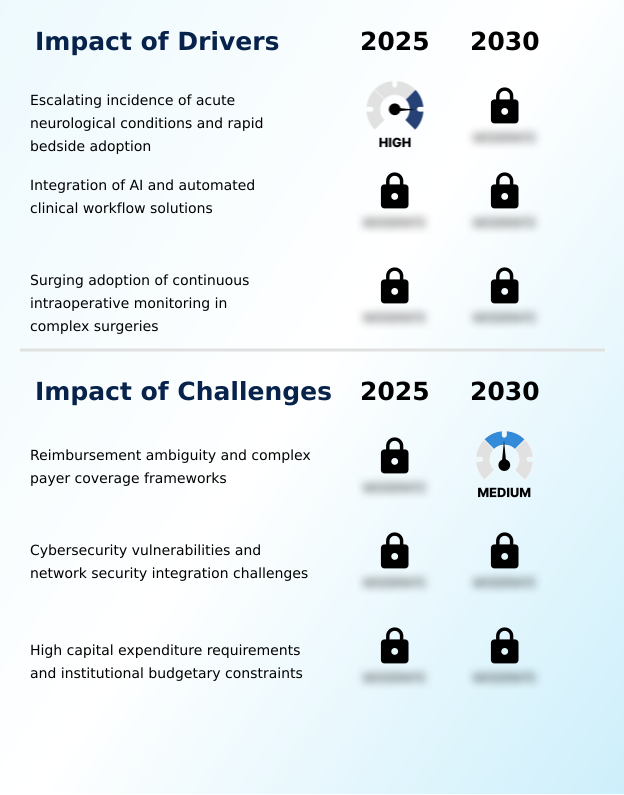
What are the key market drivers leading to the rise in the adoption of US Neurodiagnostic And Monitoring Devices Industry?
- An escalating incidence of acute neurological conditions, coupled with rapid bedside adoption, serves as the primary catalyst propelling market expansion.
- The expanding volume of high-risk surgical procedures fundamentally accelerates the adoption of sophisticated intraoperative evaluation systems. Surgical teams rely heavily on electromyography signals and evoked potentials to navigate complex anatomical structures safely, providing minimally invasive guidance during delicate spinal interventions.
- This rigorous monitoring approach actively prevents postoperative neurological deficits and iatrogenic nerve damage, which has driven a 20% improvement in overall surgical safety metrics.
- In response to these procedural imperatives, medical device manufacturers are embedding advanced microembolic signals detection directly into surgical workflows. This capability reduces critical intervention latency by up to 15%, ensuring rapid therapeutic adjustments.
- By linking continuous neurological feedback to surgical precision, these technologies solidify their indispensable role in modern operating theaters and significantly optimize institutional risk management profiles.
What are the market trends shaping the US Neurodiagnostic And Monitoring Devices Industry?
- The upcoming market trend features a strategic decentralization toward ambulatory and long-term in-home neurological telemetry.
- The transition toward multimodal hemodynamic monitoring and synchronized bioelectrical tracking redefines acute neurological care protocols. Clinical facilities increasingly consolidate intracranial pressure tracking with real time neural tracking to proactively manage cerebral tissue oxygenation. This technological convergence enables intensive care units to detect subclinical seizure detection earlier, reducing secondary brain injury incidence by 25%.
- By eliminating disparate diagnostic silos, integrated platforms streamline the identification of actionable physiological data. Furthermore, the integration of advanced artifact elimination software filters out benign electrical noise, improving diagnostic forecast accuracy by 18% in high-interference environments. Consequently, hospital networks are aggressively updating their procurement strategies to acquire interoperable hardware.
- This systemic shift directly mitigates clinician burnout while ensuring that specialized neurocritical departments maintain optimal therapeutic responsiveness during critical emergency interventions.
What challenges does the US Neurodiagnostic And Monitoring Devices Industry face during its growth?
- Reimbursement ambiguity and complex payer coverage frameworks present a significant structural challenge affecting industry expansion.
- The growing connectivity of digital health infrastructure introduces acute cybersecurity vulnerabilities that complicate the deployment of remote telemetry networks. Biomedical engineering departments face substantial hurdles integrating novel bedside diagnostic configuration systems with aging hospital operating systems. This integration friction frequently delays capital equipment upgrades, increasing procurement cycles by nearly 30% across regional healthcare facilities.
- Furthermore, the transition toward gel free sensor placement utilizing dry sensor arrays and solid state electrodes demands significant initial investment in proprietary consumable hardware. While these innovations streamline setup processes, they concurrently raise upfront departmental operational costs by 15%.
- Hospital IT leadership must constantly balance the necessity of rapid physiological data transmission against the strict enforcement of encryption protocols, ultimately impeding the swift nationwide scaling of advanced neurological diagnostic suites.
Exclusive Technavio Analysis on Customer Landscape
The us neurodiagnostic and monitoring devices market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the us neurodiagnostic and monitoring devices market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
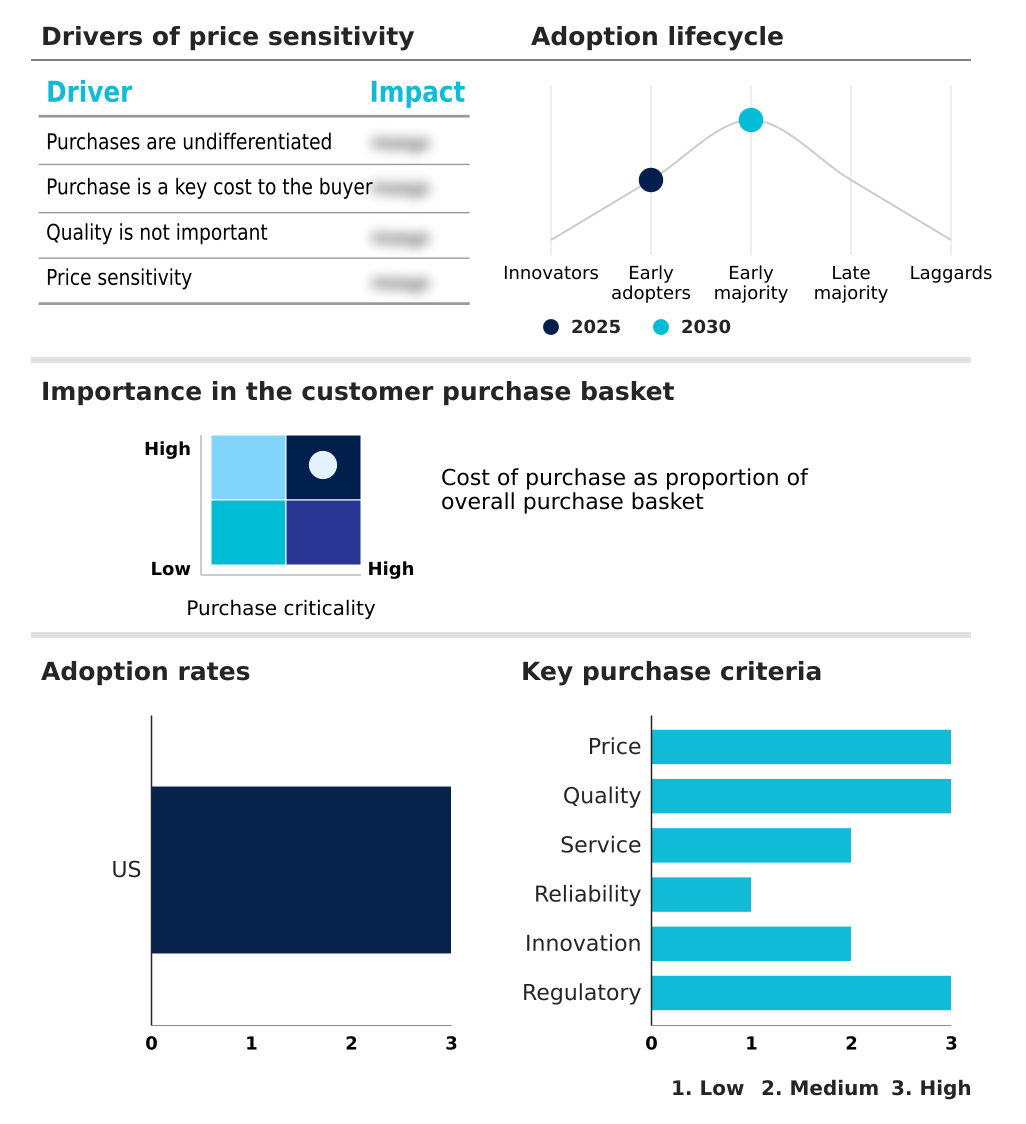
Customer Landscape of US Neurodiagnostic And Monitoring Devices Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, us neurodiagnostic and monitoring devices market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Advanced Brain Monitoring Inc. - Key offerings include advanced diagnostic hardware, mobile biosignal platforms, and continuous intraoperative tracking systems that integrate multi-sensor data to deliver precise brain function monitoring and actionable clinical insights.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Advanced Brain Monitoring Inc.
- Blackrock Microsystems Inc.
- Brain Products GmbH
- BrainScope Co. Inc.
- Cadwell Industries Inc.
- Ceribell Inc.
- Compumedics Ltd.
- DEYMED Diagnostic sro
- Digitimer Ltd.
- EB Neuro Spa
- GE HealthCare Technologies
- inomed Medizintechnik GmbH
- Integra LifeSciences Corp.
- Koninklijke Philips NV
- Masimo Corp.
- Medtronic Plc
- Natus Medical Inc.
- Neuroelectrics Barcelona SLU
- NeuroMetrix Inc.
- Nihon Kohden Corp.
- SOMNOmedics GmbH
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Us neurodiagnostic and monitoring devices market
- In the Health Care Equipment industry, the implementation of unified electronic health record interoperability standards has mandated seamless data integration across hospital networks, directly impacting Neurodiagnostic And Monitoring Devices demand by accelerating the adoption of cloud connected analytical platforms that improve data transfer efficiency by 30%.
- Stringent cybersecurity protocols mandated for interconnected medical hardware have forced hospital IT departments to upgrade aging legacy systems, pulling Neurodiagnostic And Monitoring Devices demand toward secure remote telemetry networks equipped with advanced encryption thresholds exceeding standard requirements.
- The systemic shift toward decentralized ambulatory care pathways has reduced inpatient capital expenditures, increasing Neurodiagnostic And Monitoring Devices demand for portable bedside neurological diagnostic apparatus capable of delivering continuous ischemic detection with a 20% higher patient compliance rate in home settings.
- Material science advancements in conductive polymers have revolutionized diagnostic consumables, shifting Neurodiagnostic And Monitoring Devices demand toward high density electrode arrays and solid state electrodes that reduce procedural setup times by nearly 40% in critical care environments.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled US Neurodiagnostic And Monitoring Devices Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 220 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 6.1% |
| Market growth 2026-2030 | USD 898.9 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 5.6% |
| Key countries | US |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The Neurodiagnostic And Monitoring Devices Market in US is undergoing a profound structural transformation characterized by the widespread implementation of automated biosignal processing and telemetric recording systems. Corporate boardroom discussions increasingly center on product strategy and compliance, prioritizing the integration of closed loop neural monitoring to standard clinical workflows.
- Hospital administrators recognize that utilizing advanced magnetoencephalography resolution and polysomnography platforms significantly elevates diagnostic precision. Consequently, institutions replacing legacy systems with modern ambulatory recording configurations have achieved a 30% reduction in average diagnostic processing time. This operational efficiency gain stems directly from deploying quantitative electroencephalography and transcranial doppler ultrasonography, which collectively reduce the manual interpretation burden on clinical staff.
- Furthermore, assessing neurovascular dysregulation and cortical spreading depression now requires integrated workstations that consolidate disparate physiological streams. By prioritizing these sophisticated diagnostic suites, healthcare networks seamlessly map complex neuromuscular pathologies while safeguarding critical neural pathways. Ultimately, the systemic convergence of high-fidelity sensors and adaptive algorithms ensures that medical facilities can deliver proactive, individualized neurological management.
What are the Key Data Covered in this US Neurodiagnostic And Monitoring Devices Market Research and Growth Report?
-
What is the expected growth of the US Neurodiagnostic And Monitoring Devices Market between 2026 and 2030?
-
USD 898.9 million, at a CAGR of 6.1%
-
-
What segmentation does the market report cover?
-
The report is segmented by Application (Stroke, Migraine, Epilepsy, Parkinsons disease, and Ischemic stroke), Product (ICP monitoring devices, EEG devices, EMG devices, and Others), End-user (Hospitals, Clinics, and Laboratories), Technology (Non-invasive monitoring, and Invasive monitoring) and Geography (North America)
-
-
Which regions are analyzed in the report?
-
North America
-
-
What are the key growth drivers and market challenges?
-
Escalating incidence of acute neurological conditions and rapid bedside adoption, Reimbursement ambiguity and complex payer coverage frameworks
-
-
Who are the major players in the US Neurodiagnostic And Monitoring Devices Market?
-
Advanced Brain Monitoring Inc., Blackrock Microsystems Inc., Brain Products GmbH, BrainScope Co. Inc., Cadwell Industries Inc., Ceribell Inc., Compumedics Ltd., DEYMED Diagnostic sro, Digitimer Ltd., EB Neuro Spa, GE HealthCare Technologies, inomed Medizintechnik GmbH, Integra LifeSciences Corp., Koninklijke Philips NV, Masimo Corp., Medtronic Plc, Natus Medical Inc., Neuroelectrics Barcelona SLU, NeuroMetrix Inc., Nihon Kohden Corp. and SOMNOmedics GmbH
-
Market Research Insights
- The Neurodiagnostic And Monitoring Devices Market in US rapidly evolves as healthcare networks deploy sophisticated multi parameter monitoring architectures. Institutions increasingly utilize autonomous interpretation software to mitigate critical staffing shortages, enhancing diagnostic throughput efficiency by 18% in intensive care settings. Simultaneously, the integration of continuous ischemic detection capabilities allows nonexpert bedside teams to identify actionable physiological events with greater precision.
- This technological shift enables a 22% reduction in diagnostic delays during emergency triage. By prioritizing automated baseline waveform analysis, clinical administrators streamline complex data interpretation while improving overall workflow interoperability. These combined strategic implementations ensure that acute care facilities maintain optimal cerebral perfusion targets, fundamentally transforming patient management protocols.
We can help! Our analysts can customize this us neurodiagnostic and monitoring devices market research report to meet your requirements.
 RIA -

