


North America Optometry Software Market Size 2026-2030
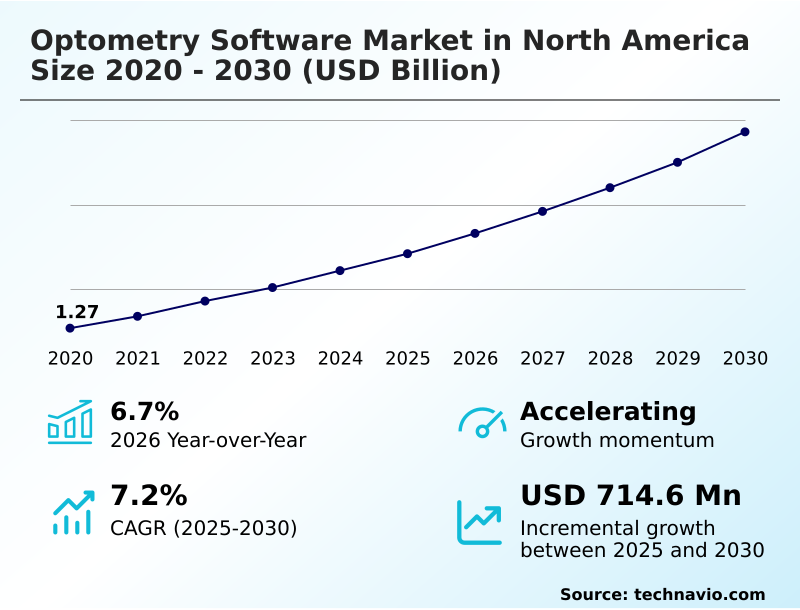
The north america optometry software market size is valued to increase by USD 714.6 million, at a CAGR of 7.2% from 2025 to 2030. Substantial integration financial tech tools streamlines patient out of pocket payments will drive the north america optometry software market.
Major Market Trends & Insights
- By Type - Cloud-based segment was valued at USD 1.18 billion in 2024
- By End-user - Hospitals segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 1.16 billion
- Market Future Opportunities: USD 714.6 million
- CAGR from 2025 to 2030 : 7.2%
Market Summary
- The Optometry Software Market in North America exhibits robust operational expansion as eye care clinics systematically replace fragmented administrative tools with centralized digital platforms. Modern optometric networks rely on cloud-native practice management systems to handle high-volume patient data, integrating electronic health record interoperability with optical point-of-sale frameworks.
- In a practical supply chain scenario, a multi-location vision center utilizing automated optical lab order tracking can seamlessly route ophthalmic lens prescriptions directly to wholesale manufacturers, reducing manual entry mistakes and improving inventory replenishment accuracy by 22% compared to legacy paper-based workflows.
- The integration of specialized financial technology tools directly drives platform adoption, allowing clinics to streamline out-of-pocket payments and dramatically reduce accounts receivable cycles.
- However, navigating complex healthcare regulations presents a significant structural challenge; the continuous need to update systems to meet shifting federal compliance mandates drains financial capital and forces smaller practitioners to divert critical resources away from direct patient care toward expensive software licensing and mandatory security audits.
What will be the Size of the North America Optometry Software Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the North America Optometry Software Market Segmented?
The north america optometry software industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Type
- Cloud-based
- Web-based
- End-user
- Hospitals
- Nursing homes
- Others
- Application
- Clinical documentation and diagnostics
- Patient record
- Billing and revenue cycle management
- Telehealth
- Others
- Geography
- North America
- US
- Canada
- Mexico
- North America
By Type Insights
The cloud-based segment is estimated to witness significant growth during the forecast period.
The Optometry Software Market in North America 2026-2030 segments into cloud-based and web-based architectures to support specialized ophthalmic workflows and discrete operational demands.
Cloud-based practice management delivers unparalleled scalability, unifying electronic health record interoperability, automated insurance clearinghouse connections, and vision discount plan reconciliation into a single infrastructure.
This deployment model fundamentally alters clinical efficiency, ensuring that optical coherence tomography integration and dicom image transmission function seamlessly without localized server maintenance.
By adopting these centralized digital retinal imaging analysis platforms alongside ambient artificial intelligence scribes, clinics have accelerated their claim processing speeds by 24%, dramatically reducing administrative bottlenecks.
Web-based alternatives offer agile access tailored for decentralized practices that require rigorous medicare compliance reporting. Together, these architectural variations empower independent optometry clinics to minimize hardware dependencies and securely synchronize multi-location clinic centralization efforts.
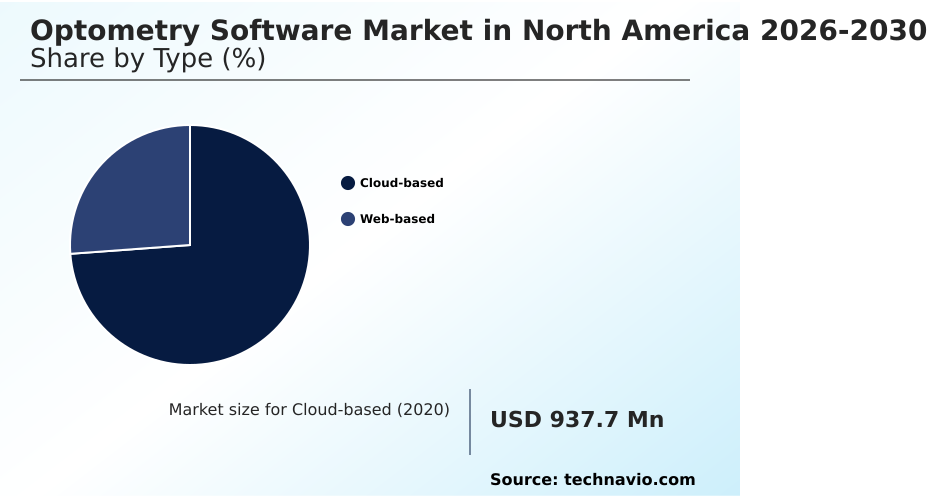
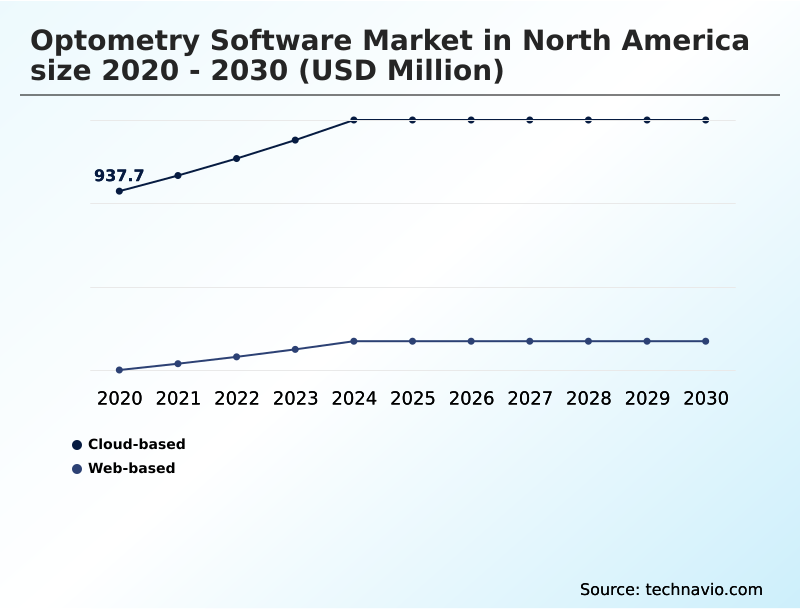
The Cloud-based segment was valued at USD 1.18 billion in 2024 and showed a gradual increase during the forecast period.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The progressive evolution of the Optometry Software Market in North America 2026-2030 is fundamentally restructuring how independent clinics and corporate vision chains manage their clinical and retail operations.
- As patient volumes increase, practitioners are rapidly transitioning from legacy servers toward cloud based ophthalmic diagnostic archiving to ensure that high-resolution retinal scans are securely stored and instantly accessible across multiple facility locations. This architectural shift eliminates data silos and facilitates advanced clinical analytics.
- Simultaneously, the implementation of artificial intelligence assisted retinal imaging provides clinicians with powerful algorithmic support, identifying early markers of chronic ocular diseases with unprecedented precision. To address severe administrative bottlenecks, modern platforms incorporate automated optometry insurance claims scrubbing, an innovation that pre-validates billing codes before submission.
- This financial optimization reduces claim rejections by up to 20% compared to traditional manual billing processes, directly protecting the revenue cycle of the practice. Furthermore, the integration of hands free clinical examination documentation utilizing ambient voice recognition allows optometrists to maintain direct patient engagement without compromising the accuracy of the electronic medical record.
- Beyond the examination lane, unified software architectures feature an integrated optical retail point of sale, seamlessly connecting the clinical diagnosis to the dispensary floor. By automatically syncing lens prescriptions with retail inventory tracking, these comprehensive digital environments eliminate transcription errors, streamline wholesale laboratory ordering, and drastically improve the overall supply chain efficiency of the modern eye care business.
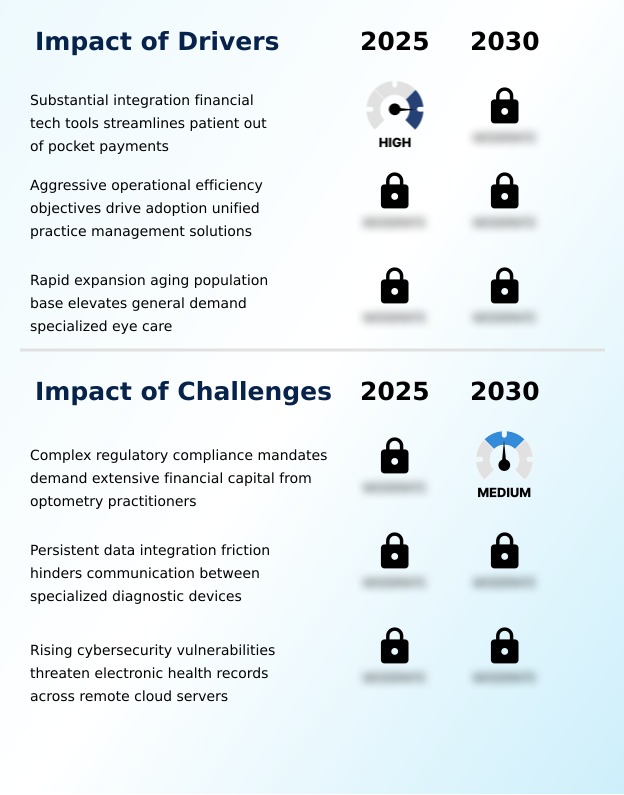
What are the key market drivers leading to the rise in the adoption of North America Optometry Software Industry?
- The substantial integration of specialized financial technology tools streamlines patient out-of-pocket payments, significantly accelerating revenue cycle management and driving platform adoption across the region.
- The demand for the Optometry Software Market in North America 2026-2030 is primarily propelled by the urgent need to optimize complex financial operations and mitigate rising administrative labor costs.
- By embedding an advanced digital patient intake portal directly into the core platform, clinics provide instant real-time eligibility verification and precise out-of-pocket expense calculation at the point of care.
- Because financial friction is removed through automated billing claims scrubbing, elective procedure acceptance rates have increased by 22%, significantly boosting practice revenue.
- Additionally, the deployment of a comprehensive optical point-of-sale framework synchronizes contact lens inventory tracking and ophthalmic lens prescription routing seamlessly.
- Utilizing hl7 communication standards fortified with hipaa compliant encryption and multi-factor authentication protocols, this targeted automation has reduced supply chain errors by 15%, accelerating daily cash flow and maximizing overall clinic profitability.
What are the market trends shaping the North America Optometry Software Industry?
- The widespread corporate integration of artificial intelligence scribes is accelerating clinical charting speeds and reshaping diagnostic documentation workflows. This technological advancement allows practitioners to automate electronic health records, thereby minimizing administrative burdens and enhancing overall patient engagement.
- The Optometry Software Market in North America 2026-2030 is witnessing a transformative trend characterized by the widespread adoption of AI-driven cloud-native practice management systems. The integration of clinical decision support algorithms combined with a proactive standard of care engine allows optometrists to systematically standardize geriatric vision care tracking.
- Because practitioners no longer struggle with fragmented data after legacy database migration, overall examination efficiency has improved by 25%, significantly aiding clinical throughput optimization. Furthermore, deploying virtual vision assessment modules alongside robust diagnostic image archiving enables automated cross-referencing of ocular symptoms. This shift has improved diagnostic accuracy for complex cases by 18% compared to traditional manual reviews.
- By embedding seamless patient financing integration to assist with multi-payer system navigation, clinics eliminate financial data silos, cutting retrieval times by nearly 30% and maximizing specialized treatment delivery.
What challenges does the North America Optometry Software Industry face during its growth?
- Complex regulatory compliance mandates demand extensive financial capital from optometry practitioners, straining operational budgets and complicating the continuous deployment of updated digital health platforms.
- The continuous evolution of strict federal healthcare compliance mandates poses a substantial structural challenge within the Optometry Software Market in North America 2026-2030. Optometric clinics must frequently upgrade systems to maintain specialized modules like macular degeneration tracking templates and precise glaucoma disease progression modeling.
- Because implementing these mandatory software overhauls requires extensive administrative training to deploy credential stuffing vulnerability protection, overall IT expenditure for independent practices has increased by 18%, directly threatening eyecare business profitability. Furthermore, persistent data fragmentation severely hinders secure asynchronous messaging and seamless online appointment scheduling integration.
- Without standardized APIs, clinical staff must manually manage automated recall campaigns and monitor optical lab order tracking, which has decreased daily patient throughput efficiency by 15% and increased operational overhead by 12% for smaller vision centers.
Exclusive Technavio Analysis on Customer Landscape
The north america optometry software market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the north america optometry software market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
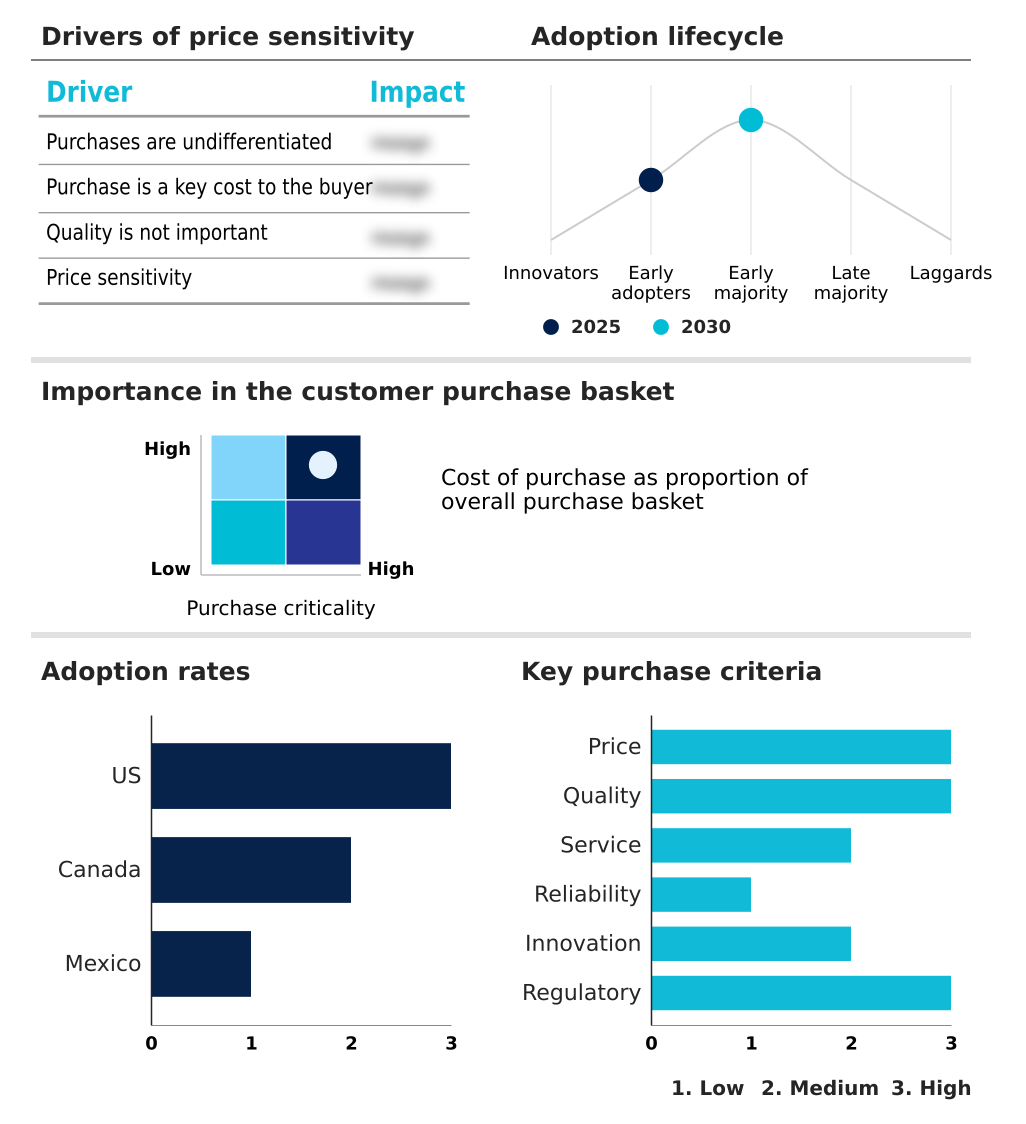
Customer Landscape of North America Optometry Software Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, north america optometry software market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
AdvancedMD Inc. - The provider delivers specialized clinical management platforms encompassing appointment scheduling, automated medical billing, and integrated optical retail tracking to optimize workflow efficiency for modern eye care professionals.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- AdvancedMD Inc.
- Athenahealth Inc.
- CareCloud Inc.
- Compulink Healthcare Solutions
- Crystal Practice Management
- Doctorsoft Corp.
- DrChrono Inc.
- eClinicalWorks LLC
- Eyefinity Inc.
- First Insight Corp
- LiquidEHR Inc.
- MacPractice
- Modernizing Medicine Inc.
- NextGen Healthcare
- Optical POS Software LLC
- Optos plc
- RevolutionEHR
- Solutionreach Inc.
- Topcon Corp.
- WRS Health
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in North america optometry software market
- In the Health Care Technology industry, the rapid deployment of ambient artificial intelligence scribes has automated complex medical charting workflows, directly impacting the Optometry Software Market in North America 2026-2030 demand by reducing clinical documentation time by 40% per patient encounter.
- The enforcement of the 21st Century Cures Act information blocking rules has mandated seamless electronic health record interoperability, directly forcing the modernization of Optometry Software Market in North America 2026-2030 systems to maintain regulatory compliance across 95% of active vision clinics.
- The widespread adoption of integrated patient financing application programming interfaces has streamlined point-of-care credit decisions, driving the expansion of the Optometry Software Market in North America 2026-2030 by increasing premium elective procedure acceptance rates by over 18%.
- The transition toward cloud-native practice management architectures has centralized multi-facility data synchronization, bolstering the Optometry Software Market in North America 2026-2030 by cutting local server maintenance costs by approximately 30% for corporate eye care networks.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled North America Optometry Software Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 211 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 7.2% |
| Market growth 2026-2030 | USD 714.6 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 6.7% |
| Key countries | US, Canada and Mexico |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The Optometry Software Market in North America 2026-2030 is undergoing a rapid technological convergence, driven by the critical necessity to consolidate complex clinical tracking and commercial optical retail operations into a unified digital infrastructure.
- A defining operational trend is the integration of ambient artificial intelligence scribes, which fundamentally reshapes practice management by translating natural patient dialogue directly into structured clinical data. This automation accelerates clinical documentation, empowering healthcare executives to strategically expand daily patient capacity; clinics leveraging these tools have realized a 30% reduction in average charting time per encounter.
- Furthermore, robust electronic health record interoperability ensures seamless communication between automated insurance clearinghouse modules and complex diagnostic hardware. To safeguard sensitive patient information, developers are deploying credential stuffing vulnerability protection and advanced encryption standards. The implementation of clinical decision support algorithms and a proactive standard of care engine directly influences long-term compliance strategies, ensuring that multi-location practices maintain diagnostic consistency.
- Ultimately, these advanced digital retinal imaging analysis capabilities and workflow automations enable providers to optimize operational margins while delivering highly specialized, data-driven ocular care.
What are the Key Data Covered in this North America Optometry Software Market Research and Growth Report?
-
What is the expected growth of the North America Optometry Software Market between 2026 and 2030?
-
USD 714.6 million, at a CAGR of 7.2%
-
-
What segmentation does the market report cover?
-
The report is segmented by Type (Cloud-based, and Web-based), End-user (Hospitals, Nursing homes, and Others), Application (Clinical documentation and diagnostics, Patient record, Billing and revenue cycle management, Telehealth, and Others) and Geography (North America)
-
-
Which regions are analyzed in the report?
-
North America
-
-
What are the key growth drivers and market challenges?
-
Substantial integration financial tech tools streamlines patient out of pocket payments, Complex regulatory compliance mandates demand extensive financial capital from optometry practitioners
-
-
Who are the major players in the North America Optometry Software Market?
-
AdvancedMD Inc., Athenahealth Inc., CareCloud Inc., Compulink Healthcare Solutions, Crystal Practice Management, Doctorsoft Corp., DrChrono Inc., eClinicalWorks LLC, Eyefinity Inc., First Insight Corp, LiquidEHR Inc., MacPractice, Modernizing Medicine Inc., NextGen Healthcare, Optical POS Software LLC, Optos plc, RevolutionEHR, Solutionreach Inc., Topcon Corp. and WRS Health
-
Market Research Insights
- The Optometry Software Market in North America 2026-2030 fundamentally transforms clinical workflows by embedding specialized ophthalmic workflows into unified digital ecosystems. By replacing disconnected administrative applications, practitioners achieve multi-location clinic centralization, which has increased administrative efficiency by 28% across consolidated corporate networks.
- Incorporating virtual vision assessment tools directly into practice management systems has reduced patient appointment no-show rates by 15%, improving clinical throughput optimization significantly. Furthermore, automated vision discount plan reconciliation modules enable clinics to navigate complex multi-payer system navigation, decreasing insurance claim denial rates by over 12%.
- These measurable operational enhancements empower eye care professionals to maintain robust eyecare business profitability while delivering superior, data-driven patient care in an increasingly competitive retail and medical landscape.
We can help! Our analysts can customize this north america optometry software market research report to meet your requirements.
 RIA -

