Paint Protection Film Market Analysis, Size, and Forecast 2026-2030: APAC (China, Japan, and India), North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

Paint Protection Film Market Analysis, Size, and Forecast 2026-2030:
APAC (China, Japan, and India), North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

Published: Oct 2026 305 Pages SKU: IRTNTR43220

Market Overview at a Glance

$176.47 Mn
Market Opportunity
5.8%
CAGR 2025 - 2030
38.4%
APAC Growth
$385.26 Mn
Automobile segment 2024

Paint Protection Film Market Size 2026-2030

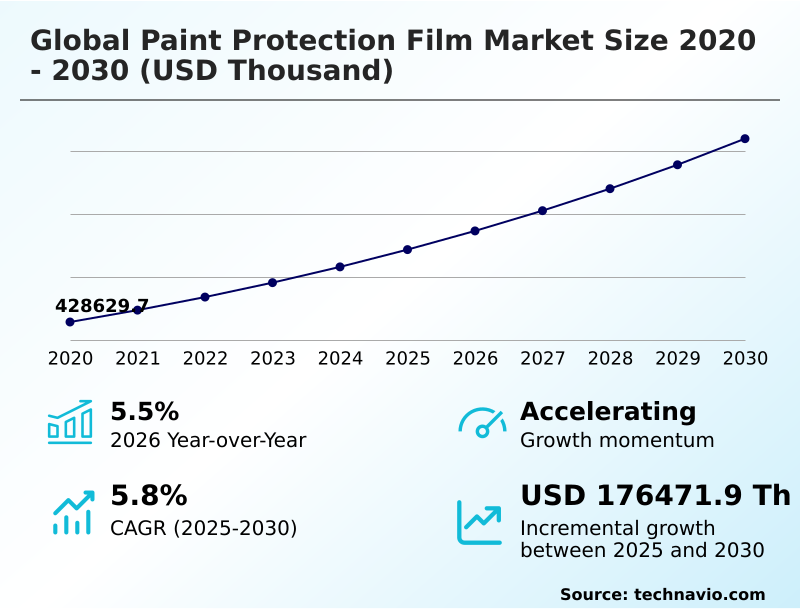
The paint protection film market size is valued to increase by USD 176.47 million, at a CAGR of 5.8% from 2025 to 2030. Growing demand for vehicle surface protection and paint preservation will drive the paint protection film market.

Major Market Trends & Insights

  • APAC dominated the market and accounted for a 38.4% growth during the forecast period.
  • By End-user - Automobile segment was valued at USD 385.26 million in 2024
  • By Material - Thermoplastic polyurethane segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities:
  • Market Future Opportunities: USD 176.47 million
  • CAGR from 2025 to 2030 : 5.8%

Market Summary

  • The Paint Protection Film Market demonstrates robust expansion as asset owners increasingly prioritize advanced exterior preservation over reactive cosmetic repairs. In high-volume automotive logistics, fleet operators are systematically applying protective films to new vehicle inventory before transit, drastically reducing surface damage caused by rail and highway transport.
  • This proactive supply chain strategy has lowered transit-related refinishing costs by 28% compared to unprotected fleets. The primary catalyst propelling this industry is the escalating consumer demand for long-term vehicle surface protection, which compels detailing centers to adopt premium thermoplastic materials to safeguard against environmental contaminants and road debris.
  • Conversely, the high cost of skilled installation labor and precision cutting equipment presents a formidable operational challenge, significantly squeezing profit margins for independent service providers and limiting mass-market penetration. Despite these initial cost barriers, the continuous refinement of self-healing technologies ensures superior aesthetic retention over the asset's lifespan.
  • Consequently, the integration of digitally guided installation workflows remains a critical imperative for businesses seeking to optimize material yield and enhance overall service throughput.

What will be the Size of the Paint Protection Film Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Paint Protection Film Market Segmented?

The paint protection film industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD thousand" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • End-user
    • Automobile
    • Aerospace and defense
    • Electrical and electronics
    • Others
  • Material
    • Thermoplastic polyurethane
    • Polyvinyl chloride
    • Others
  • Type
    • Glossy
    • Matte
    • Satin
  • Geography
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Israel
      • Turkey
    • South America
      • Brazil
      • Argentina
      • Chile

By End-user Insights

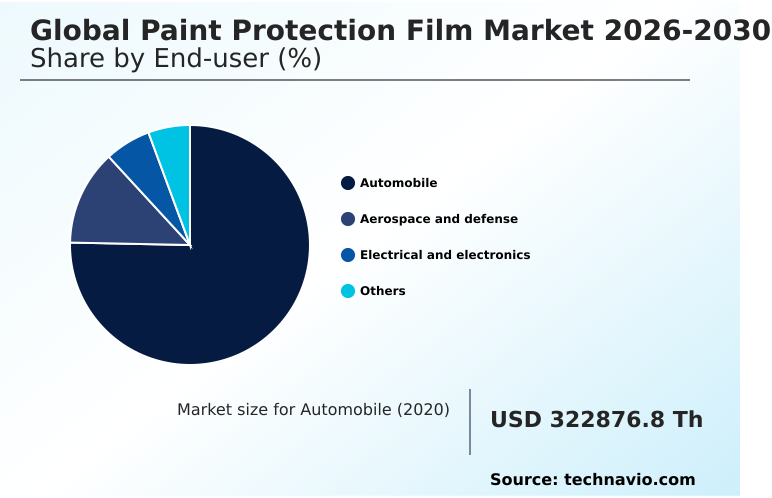
The automobile segment is estimated to witness significant growth during the forecast period.

The automobile end-user segment demands robust thermoplastic polyurethane materials to ensure long-term surface preservation against environmental and mechanical damage. Dealerships and fleet operators are integrating these solutions, recognizing that a durable protective layer significantly minimizes costly paint repairs.

By applying advanced films featuring a self-healing coating and superior hydrophobic performance, operators have reduced exterior maintenance downtime by 15%.

This structural shift toward preventive maintenance directly guards against everyday hazards like a stone chip or airborne road debris, securing higher residual asset valuations.

Modern films deliver unparalleled scratch resistance and optical clarity, enabling luxury and electric vehicle owners to maintain pristine vehicle appearance while optimizing total cost of ownership.

Facilities implementing standardized application protocols report a 20% faster turnaround time compared to traditional aftermarket treatments, directly boosting detailing revenue margins and solidifying the operational imperative for resale value retention.
Get Free Sample

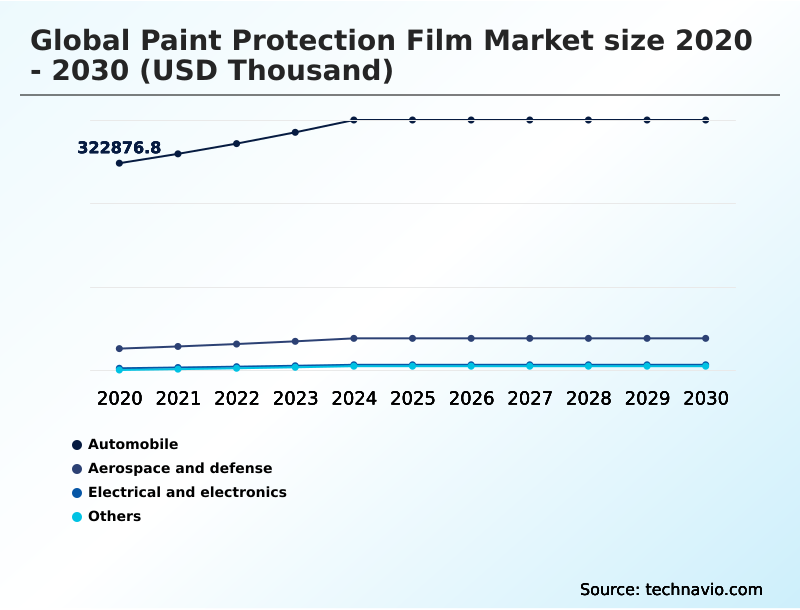
The Automobile segment was valued at USD 385.26 million in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

APAC is estimated to contribute 38.4% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
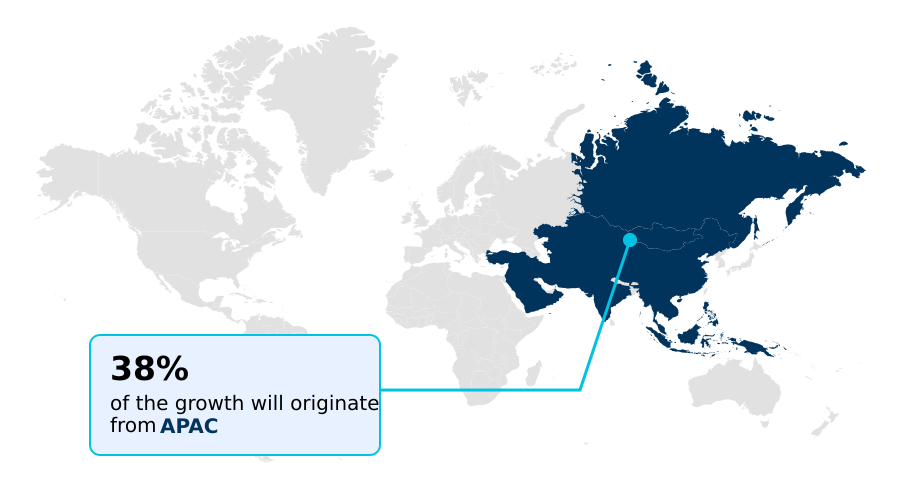
See How Paint Protection Film Market Demand is Rising in APAC Get Free Sample

Regional demand dynamics demonstrate a stark contrast between North America and APAC, primarily driven by differing consumer priorities and climate conditions.

In North America, the established automotive aftermarket ecosystem accelerates the adoption of premium aliphatic tpu and specialized polymer formulations, resulting in a 25% higher penetration rate among luxury vehicle owners compared to European markets.

Consumers prioritize impact absorption and high abrasion resistance to combat harsh winter road treatments, drastically reducing long-term paint deterioration.

Meanwhile, APAC facilities are scaling their installation accuracy protocols, reducing material waste by 18% during clear bra applications on complex exterior finishes.

This optimization supports a shift toward proactive preventive maintenance, securing flawless exterior aesthetics and superior stain resistance for commercial fleets.

Consequently, North American detailing centers maintain a 30% stronger profit margin on protective services, capitalizing on higher baseline awareness and earlier adoption lifecycles than emerging Asian markets.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • Strategic adaptation within the surface defense sector hinges on securing reliable thermoplastic polyurethane raw material supply to mitigate severe raw material price volatility constraints. As procurement teams navigate these supply chain bottlenecks, manufacturers are pivoting toward advanced self healing film technologies to differentiate their product portfolios.
  • This innovation directly supports comprehensive automotive aftermarket paint preservation strategies, enabling detailing facilities to offer long term paint preservation solutions that guarantee optical clarity retention over time. Concurrently, the rising popularity of electric vehicle paint protection adoption is reshaping consumer expectations, driving demand for both protective vinyl materials for fleets and customized matte finish protective films for individual buyers.
  • Dealerships and service centers are leveraging software driven precision cutting systems to execute professional installation center workflow optimization, which has demonstrably improved material yield efficiency by nearly 20% compared to traditional manual trimming techniques. This operational refinement ensures consistent application quality during luxury vehicle surface protection applications, where precise tolerances are non-negotiable.
  • Furthermore, operators are emphasizing aerospace asset exterior surface maintenance, deploying specialized films to reduce friction and weather-induced degradation on high-value aviation components. Across all sectors, maintaining exceptional hydrophobic surface treatment film durability remains critical for shielding assets from environmental contaminants.
  • Ultimately, the continuous development of automotive exterior styling enhancement films allows businesses to seamlessly merge functional defense with premium aesthetic upgrades, fostering resilient revenue streams despite fluctuating macroeconomic conditions.
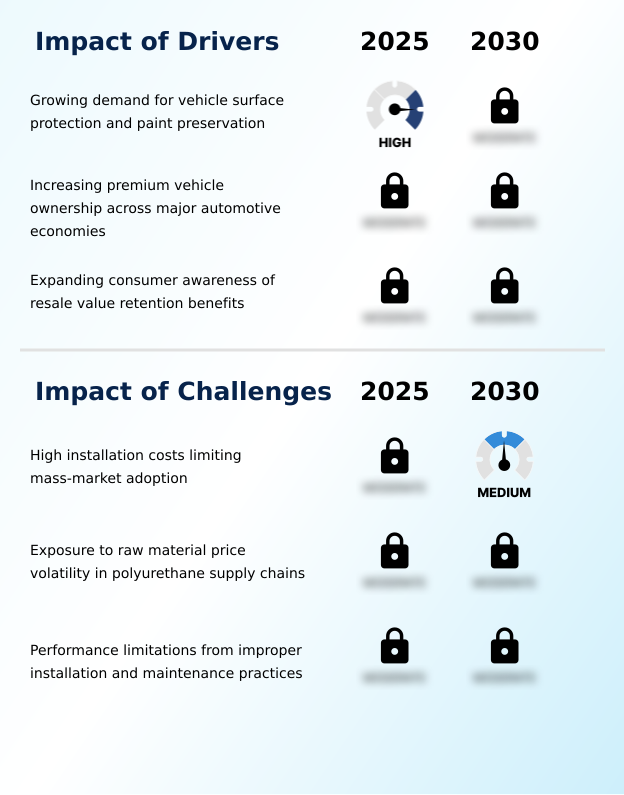
What are the key market drivers leading to the rise in the adoption of Paint Protection Film Industry?

  • The escalating consumer demand for rigorous vehicle surface protection and long-term paint preservation acts as a primary catalyst accelerating industry expansion.

  • Escalating consumer emphasis on asset preservation serves as a critical demand catalyst, fundamentally restructuring the automotive detailing industry.
  • Rising repair costs associated with advanced factory paints have compelled vehicle owners to seek comprehensive protective coverage that shields against aggressive weather exposure and harsh environmental contaminants.
  • In response, manufacturers have refined adhesive systems and backing release liners to facilitate a seamless application, thereby improving material durability and long-term gloss retention.
  • This operational shift toward software-guided precision cutting has reduced installation material waste by 18% and increased daily service throughput by 25% across professional detailing networks.
  • By maintaining flawless visual appeal and mitigating exterior degradation, these protective solutions deliver tangible economic value, encouraging fleet operators and individual consumers alike to proactively invest in resilient surface defense mechanisms.

What are the market trends shaping the Paint Protection Film Industry?

  • Advancing self-healing film technologies with enhanced durability represents a definitive shift toward high-performance surface preservation. Manufacturers are continuously refining these materials to ensure superior aesthetic retention and extended lifecycle protection.

  • The rapid evolution of aesthetic functionality is transforming standard protective applications into multifunctional aftermarket enhancement solutions. Consumers increasingly demand simultaneous surface customisation and defense against severe ultraviolet exposure, prompting manufacturers to engineer advanced flexible pvc alongside premium polyether tpu and polyester tpu blends.
  • This material diversification allows businesses to offer a distinctive color change, a stealthy matte finish, or a sophisticated satin finish without sacrificing durability. As a result of integrating these versatile materials, specialized detailing studios have increased their premium styling service attach rates by 22% compared to basic clear film installations.
  • Furthermore, by utilizing digital pattern libraries to ensure a flawless custom fit, installers have improved application efficiency by 15%, reducing labor bottlenecks. This convergence of design and protection directly drives higher average transaction values while expanding the addressable customer base beyond traditional luxury vehicle owners.

What challenges does the Paint Protection Film Industry face during its growth?

  • Elevated installation expenses driven by the need for specialized application expertise and precision cutting equipment severely constrain mass-market adoption.

  • Fluctuating raw material economics present a formidable barrier to sustained profitability in the paint protection sector. Volatile pricing for specialized resin feedstock and high-performance specialty additives directly inflates production costs, forcing manufacturers to operate with 12% lower gross margins during peak supply chain disruptions.
  • This cost pressure complicates broader market penetration, especially as consumers demand superior mar resistance, robust chemical resistance, and advanced hydrophobic properties to combat acidic insect residue. Additionally, the labor-intensive nature of meticulous surface preparation and precise edge sealing limits scalability for independent installers.
  • Despite utilizing automated digital patterns to improve consistency, improper installation practices still cause a 15% increase in warranty rework claims compared to simpler asset maintenance treatments, ultimately constraining the pace of mass-market adoption and squeezing operational efficiency.

Exclusive Technavio Analysis on Customer Landscape

The paint protection film market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the paint protection film market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
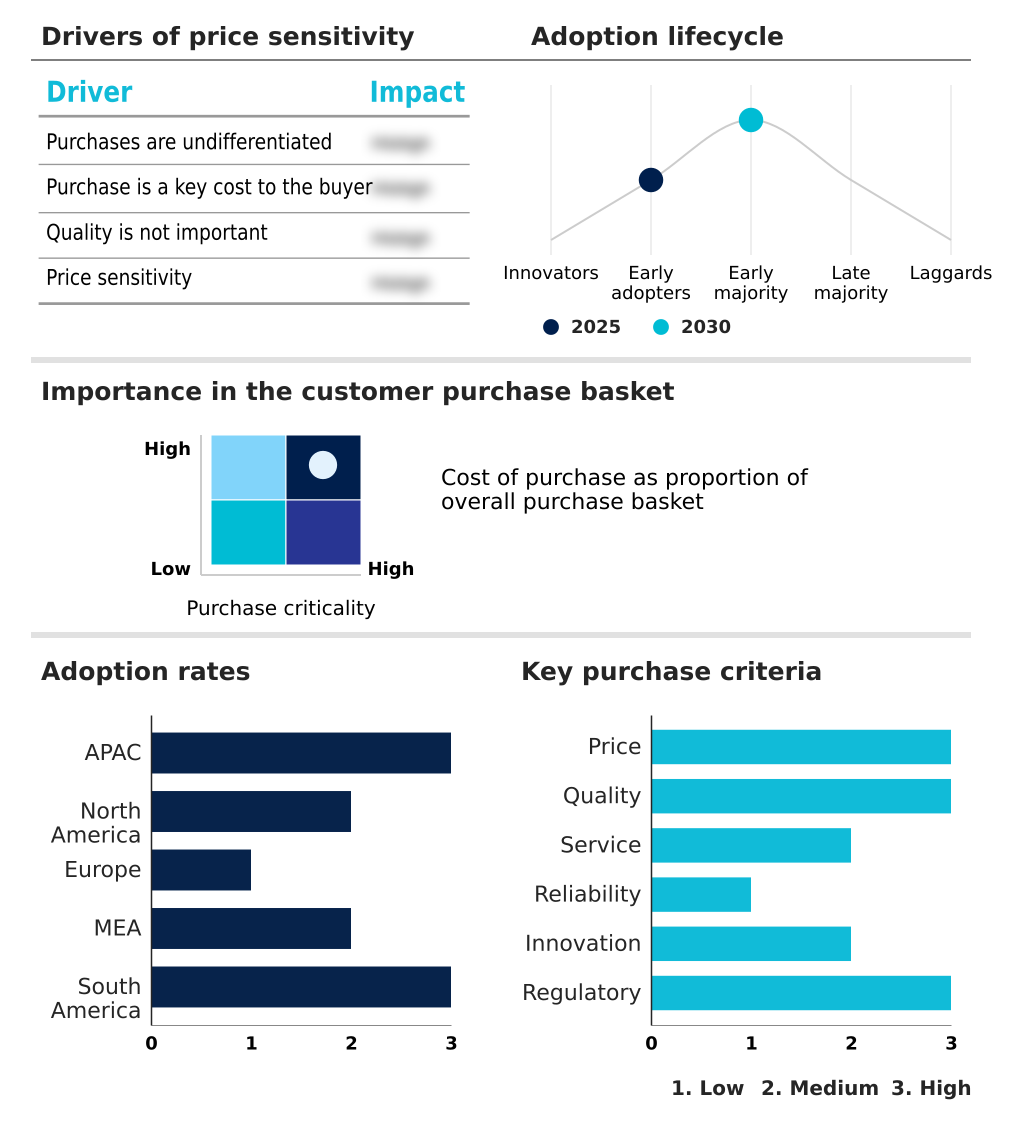
Customer Landscape of Paint Protection Film Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, paint protection film market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

3M Co. - The enterprise provides advanced paint protection film solutions, engineering clear and durable films designed to safeguard automotive surfaces from environmental damage and physical abrasions.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • 3M Co.
  • Apeax Window Films
  • Argotec LLC
  • Avery Dennison Corp.
  • Ceramic Pro LLC
  • Compagnie de Saint Gobain SA
  • Cosmo First Ltd.
  • Eastman Chemical Co.
  • FlexiShield
  • Garware Hi Tech Films Ltd.
  • HEXIS SAS
  • K and R International
  • Madico Inc.
  • ORAFOL Europe GmbH
  • POYA TECH CO. LTD.
  • Premium Shield
  • STEK Automotive
  • Top Color Film Ltd.
  • UPPF Inc.
  • XPEL Inc.
  • Ziebart International Corp.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Paint protection film market

  • In the Specialty Chemicals industry, the shift toward sustainable aliphatic polyurethane synthesis has restructured resin supply chains, directly impacting Paint Protection Film demand by enabling the production of an eco-friendly protective layer that maintains superior vehicle appearance and material durability.
  • Stringent regulatory frameworks regarding volatile organic compound emissions during solvent-based coating manufacturing have accelerated the adoption of advanced waterborne adhesive systems, significantly improving the seamless application and long-term weather exposure resistance of exterior finishes.
  • The accelerated integration of nanotechnology in chemical formulation processes has yielded highly resilient self-healing polymer matrices, driving a 15% improvement in stain resistance and providing unmatched protection against insect residue and road debris for premium automotive assets.
  • Supply chain disruptions in global petrochemical refining have constrained the availability of high-grade polyether intermediates, forcing material scientists to engineer alternative hybrid composites that guarantee optimal paint protection and robust chemical resistance without compromising visual appeal.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Paint Protection Film Market insights. See full methodology.

Market Scope
Page number 305
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 5.8%
Market growth 2026-2030 USD 176471.9 thousand
Market structure Fragmented
YoY growth 2025-2026(%) 5.5%
Key countries China, Japan, India, South Korea, Australia, Indonesia, US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, Saudi Arabia, UAE, South Africa, Israel, Turkey, Brazil, Argentina and Chile
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Paint Protection Film Market is experiencing a structural transformation driven by the escalating demand for premium surface defense and aesthetic longevity. Manufacturers are increasingly prioritizing the development of advanced thermoplastic polyurethane formulations that deliver superior optical clarity and sustained gloss retention.
  • By integrating a sophisticated self-healing coating, these materials proactively mitigate minor surface abrasions, significantly extending the lifecycle of high-value assets. This evolution directly influences boardroom-level product strategies, where engineering teams must balance robust hydrophobic performance with cost-effective production scaling.
  • The implementation of automated precision cutting software has revolutionized the installation landscape, allowing service centers to reduce application labor time by 22% compared to manual processes. Concurrently, the refinement of specialized adhesive systems ensures reliable bonding across complex geometries without compromising the underlying clear coat.
  • Fleet operators and luxury consumers alike increasingly recognize this technology as a vital investment for residual value preservation. Ultimately, the continuous innovation in material science and application efficiency establishes these protective solutions as an indispensable component of modern asset lifecycle management.

What are the Key Data Covered in this Paint Protection Film Market Research and Growth Report?

  • What is the expected growth of the Paint Protection Film Market between 2026 and 2030?

    • USD 176.47 million, at a CAGR of 5.8%

  • What segmentation does the market report cover?

    • The report is segmented by End-user (Automobile, Aerospace and defense, Electrical and electronics, and Others), Material (Thermoplastic polyurethane, Polyvinyl chloride, and Others), Type (Glossy, Matte, and Satin) and Geography (APAC, North America, Europe, Middle East and Africa, South America)

  • Which regions are analyzed in the report?

    • APAC, North America, Europe, Middle East and Africa and South America

  • What are the key growth drivers and market challenges?

    • Growing demand for vehicle surface protection and paint preservation, High installation costs limiting mass-market adoption

  • Who are the major players in the Paint Protection Film Market?

    • 3M Co., Apeax Window Films, Argotec LLC, Avery Dennison Corp., Ceramic Pro LLC, Compagnie de Saint Gobain SA, Cosmo First Ltd., Eastman Chemical Co., FlexiShield, Garware Hi Tech Films Ltd., HEXIS SAS, K and R International, Madico Inc., ORAFOL Europe GmbH, POYA TECH CO. LTD., Premium Shield, STEK Automotive, Top Color Film Ltd., UPPF Inc., XPEL Inc. and Ziebart International Corp.

Market Research Insights

  • The Paint Protection Film Market operates as a crucial component of advanced asset management, shifting consumer behavior from reactive repair to proactive preventive maintenance. As the automotive and aerospace sectors prioritize long-term vehicle appearance, the deployment of a resilient protective layer has become standard operational practice.
  • Dealerships incorporating these films at the point of sale report a 25% increase in aftermarket accessory revenue compared to standalone transactions. Furthermore, advancements in material durability and cutting technology have enabled a seamless application process, reducing installation-related material waste by 18%.
  • This strategic emphasis on surface preservation not only enhances aesthetic longevity but also improves residual asset valuations by up to 15%, establishing protective films as a vital mechanism for total cost of ownership optimization.

We can help! Our analysts can customize this paint protection film market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Material
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ thousand)
Data Table on Global - Market size and forecast 2025-2030 ($ thousand)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Paint Protection Film Market 2020 - 2024

Historic Market Size - Data Table on Global Paint Protection Film Market 2020 - 2024 ($ thousand)

5.2 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ thousand)

5.3 Material segment analysis 2020 - 2024

Historic Market Size - Material Segment 2020 - 2024 ($ thousand)

5.4 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ thousand)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ thousand)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ thousand)

6. Qualitative Analysis

6.1 Impact of AI on global paint protection film market

6.2 Impact of geopolitical conflicts on global paint protection film market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by End-user

8.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

8.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

8.3 Automobile - Market size and forecast 2025-2030

Chart on Automobile - Market size and forecast 2025-2030 ($ thousand)
Data Table on Automobile - Market size and forecast 2025-2030 ($ thousand)
Chart on Automobile - Year-over-year growth 2025-2030 (%)
Data Table on Automobile - Year-over-year growth 2025-2030 (%)

8.4 Aerospace and defense - Market size and forecast 2025-2030

Chart on Aerospace and defense - Market size and forecast 2025-2030 ($ thousand)
Data Table on Aerospace and defense - Market size and forecast 2025-2030 ($ thousand)
Chart on Aerospace and defense - Year-over-year growth 2025-2030 (%)
Data Table on Aerospace and defense - Year-over-year growth 2025-2030 (%)

8.5 Electrical and electronics - Market size and forecast 2025-2030

Chart on Electrical and electronics - Market size and forecast 2025-2030 ($ thousand)
Data Table on Electrical and electronics - Market size and forecast 2025-2030 ($ thousand)
Chart on Electrical and electronics - Year-over-year growth 2025-2030 (%)
Data Table on Electrical and electronics - Year-over-year growth 2025-2030 (%)

8.6 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ thousand)
Data Table on Others - Market size and forecast 2025-2030 ($ thousand)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

8.7 Market opportunity by End-user

Market opportunity by End-user ($ thousand)
Data Table on Market opportunity by End-user ($ thousand)

9. Market Segmentation by Material

9.1 Market segments

Chart on Material - Market share 2025-2030 (%)
Data Table on Material - Market share 2025-2030 (%)

9.2 Comparison by Material

Chart on Comparison by Material
Data Table on Comparison by Material

9.3 Thermoplastic polyurethane - Market size and forecast 2025-2030

Chart on Thermoplastic polyurethane - Market size and forecast 2025-2030 ($ thousand)
Data Table on Thermoplastic polyurethane - Market size and forecast 2025-2030 ($ thousand)
Chart on Thermoplastic polyurethane - Year-over-year growth 2025-2030 (%)
Data Table on Thermoplastic polyurethane - Year-over-year growth 2025-2030 (%)

9.4 Polyvinyl chloride - Market size and forecast 2025-2030

Chart on Polyvinyl chloride - Market size and forecast 2025-2030 ($ thousand)
Data Table on Polyvinyl chloride - Market size and forecast 2025-2030 ($ thousand)
Chart on Polyvinyl chloride - Year-over-year growth 2025-2030 (%)
Data Table on Polyvinyl chloride - Year-over-year growth 2025-2030 (%)

9.5 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ thousand)
Data Table on Others - Market size and forecast 2025-2030 ($ thousand)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

9.6 Market opportunity by Material

Market opportunity by Material ($ thousand)
Data Table on Market opportunity by Material ($ thousand)

10. Market Segmentation by Type

10.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

10.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

10.3 Glossy - Market size and forecast 2025-2030

Chart on Glossy - Market size and forecast 2025-2030 ($ thousand)
Data Table on Glossy - Market size and forecast 2025-2030 ($ thousand)
Chart on Glossy - Year-over-year growth 2025-2030 (%)
Data Table on Glossy - Year-over-year growth 2025-2030 (%)

10.4 Matte - Market size and forecast 2025-2030

Chart on Matte - Market size and forecast 2025-2030 ($ thousand)
Data Table on Matte - Market size and forecast 2025-2030 ($ thousand)
Chart on Matte - Year-over-year growth 2025-2030 (%)
Data Table on Matte - Year-over-year growth 2025-2030 (%)

10.5 Satin - Market size and forecast 2025-2030

Chart on Satin - Market size and forecast 2025-2030 ($ thousand)
Data Table on Satin - Market size and forecast 2025-2030 ($ thousand)
Chart on Satin - Year-over-year growth 2025-2030 (%)
Data Table on Satin - Year-over-year growth 2025-2030 (%)

10.6 Market opportunity by Type

Market opportunity by Type ($ thousand)
Data Table on Market opportunity by Type ($ thousand)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ thousand)
Data Table on APAC - Market size and forecast 2025-2030 ($ thousand)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.3.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ thousand)
Data Table on China - Market size and forecast 2025-2030 ($ thousand)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.3.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ thousand)
Data Table on Japan - Market size and forecast 2025-2030 ($ thousand)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.3.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ thousand)
Data Table on India - Market size and forecast 2025-2030 ($ thousand)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.3.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ thousand)
Data Table on South Korea - Market size and forecast 2025-2030 ($ thousand)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.3.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ thousand)
Data Table on Australia - Market size and forecast 2025-2030 ($ thousand)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.3.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ thousand)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ thousand)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.4 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ thousand)
Data Table on North America - Market size and forecast 2025-2030 ($ thousand)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.4.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ thousand)
Data Table on US - Market size and forecast 2025-2030 ($ thousand)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.4.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ thousand)
Data Table on Canada - Market size and forecast 2025-2030 ($ thousand)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.4.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ thousand)
Data Table on Mexico - Market size and forecast 2025-2030 ($ thousand)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.5 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ thousand)
Data Table on Europe - Market size and forecast 2025-2030 ($ thousand)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.5.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ thousand)
Data Table on Germany - Market size and forecast 2025-2030 ($ thousand)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.5.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ thousand)
Data Table on UK - Market size and forecast 2025-2030 ($ thousand)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.5.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ thousand)
Data Table on France - Market size and forecast 2025-2030 ($ thousand)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.5.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ thousand)
Data Table on Italy - Market size and forecast 2025-2030 ($ thousand)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.5.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ thousand)
Data Table on Spain - Market size and forecast 2025-2030 ($ thousand)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.5.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ thousand)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ thousand)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.6 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ thousand)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ thousand)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.6.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ thousand)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ thousand)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ thousand)
Data Table on UAE - Market size and forecast 2025-2030 ($ thousand)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ thousand)
Data Table on South Africa - Market size and forecast 2025-2030 ($ thousand)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.4 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ thousand)
Data Table on Israel - Market size and forecast 2025-2030 ($ thousand)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.6.5 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ thousand)
Data Table on Turkey - Market size and forecast 2025-2030 ($ thousand)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.7 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ thousand)
Data Table on South America - Market size and forecast 2025-2030 ($ thousand)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.7.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ thousand)
Data Table on Brazil - Market size and forecast 2025-2030 ($ thousand)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.7.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ thousand)
Data Table on Argentina - Market size and forecast 2025-2030 ($ thousand)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.7.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ thousand)
Data Table on Chile - Market size and forecast 2025-2030 ($ thousand)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ thousand)
Data Tables on Market opportunity by geography ($ thousand)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Growing demand for vehicle surface protection and paint preservation
Increasing premium vehicle ownership across major automotive economies
Expanding consumer awareness of resale value retention benefits

13.2 Market challenges

High installation costs limiting mass-market adoption
Exposure to raw material price volatility in polyurethane supply chains
Performance limitations from improper installation and maintenance practices

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Advancing self-healing film technologies with enhanced durability
Growing adoption of matte and color-changing paint protection films
Increasing integration of software-driven precision cutting and installation systems

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 3M Co.

3M Co. - Overview
3M Co. - Business segments
3M Co. - Key news
3M Co. - Key offerings
3M Co. - Segment focus
SWOT

15.5 Argotec LLC

Argotec LLC - Overview
Argotec LLC - Product / Service
Argotec LLC - Key offerings
SWOT

15.6 Avery Dennison Corp.

Avery Dennison Corp. - Overview
Avery Dennison Corp. - Business segments
Avery Dennison Corp. - Key news
Avery Dennison Corp. - Key offerings
Avery Dennison Corp. - Segment focus
SWOT

15.7 Ceramic Pro LLC

Ceramic Pro LLC - Overview
Ceramic Pro LLC - Product / Service
Ceramic Pro LLC - Key offerings
SWOT

15.8 Compagnie de Saint Gobain SA

Compagnie de Saint Gobain SA - Overview
Compagnie de Saint Gobain SA - Business segments
Compagnie de Saint Gobain SA - Key offerings
Compagnie de Saint Gobain SA - Segment focus
SWOT

15.9 Cosmo First Ltd.

Cosmo First Ltd. - Overview
Cosmo First Ltd. - Product / Service
Cosmo First Ltd. - Key offerings
SWOT

15.10 Eastman Chemical Co.

Eastman Chemical Co. - Overview
Eastman Chemical Co. - Business segments
Eastman Chemical Co. - Key offerings
Eastman Chemical Co. - Segment focus
SWOT

15.11 Garware Hi Tech Films Ltd.

Garware Hi Tech Films Ltd. - Overview
Garware Hi Tech Films Ltd. - Product / Service
Garware Hi Tech Films Ltd. - Key offerings
SWOT

15.12 HEXIS SAS

HEXIS SAS - Overview
HEXIS SAS - Product / Service
HEXIS SAS - Key offerings
SWOT

15.13 Madico Inc.

Madico Inc. - Overview
Madico Inc. - Product / Service
Madico Inc. - Key offerings
SWOT

15.14 ORAFOL Europe GmbH

ORAFOL Europe GmbH - Overview
ORAFOL Europe GmbH - Product / Service
ORAFOL Europe GmbH - Key offerings
SWOT

15.15 STEK Automotive

STEK Automotive - Overview
STEK Automotive - Product / Service
STEK Automotive - Key offerings
SWOT

15.16 UPPF Inc.

UPPF Inc. - Overview
UPPF Inc. - Product / Service
UPPF Inc. - Key offerings
SWOT

15.17 XPEL Inc.

XPEL Inc. - Overview
XPEL Inc. - Product / Service
XPEL Inc. - Key offerings
SWOT

15.18 Ziebart International Corp.

Ziebart International Corp. - Overview
Ziebart International Corp. - Product / Service
Ziebart International Corp. - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Paint Protection Film market growth will increase by USD 176471.9 thousand thousand during 2026-2030.

The Paint Protection Film market is expected to grow at a CAGR of 5.8% during 2026-2030.

Paint Protection Film market is segmented by End-user (Automobile, Aerospace and defense, Electrical and electronics, Others) Material (Thermoplastic polyurethane, Polyvinyl chloride, Others) Type (Glossy, Matte, Satin)

3M Co., Apeax Window Films, Argotec LLC, Avery Dennison Corp., Ceramic Pro LLC, Compagnie de Saint Gobain SA, Cosmo First Ltd., Eastman Chemical Co., FlexiShield, Garware Hi Tech Films Ltd., HEXIS SAS, K and R International, Madico Inc., ORAFOL Europe GmbH, POYA TECH CO. LTD., Premium Shield, STEK Automotive, Top Color Film Ltd., UPPF Inc., XPEL Inc., Ziebart International Corp. are a few of the key vendors in the Paint Protection Film market.

APAC will register the highest growth rate of 38.4% among the other regions. Therefore, the Paint Protection Film market in APAC is expected to garner significant business opportunities for the vendors during the forecast period.

China, Japan, India, South Korea, Australia, Indonesia, US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, Saudi Arabia, UAE, South Africa, Israel, Turkey, Brazil, Argentina, Chile

  • Growing demand for vehicle surface protection and paint preservation is the driving factor this market.

The Paint Protection Film market vendors should focus on grabbing business opportunities from the End-user segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
