Semiconductor Foundry Market Analysis, Size, and Forecast 2026-2030: APAC (Taiwan, China, and Japan), North America (US, Canada, and Mexico), Europe (Germany, France, and Italy), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Semiconductor Foundry Market Analysis, Size, and Forecast 2026-2030:
APAC (Taiwan, China, and Japan), North America (US, Canada, and Mexico), Europe (Germany, France, and Italy), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Published: Oct 2026 310 Pages SKU: IRTNTR41403

Market Overview at a Glance

$85.33 B
Market Opportunity
8.7%
CAGR 2025 - 2030
67.5%
APAC Growth
$126.68 B
Pure-play foundries segment 2024

Semiconductor Foundry Market Size 2026-2030

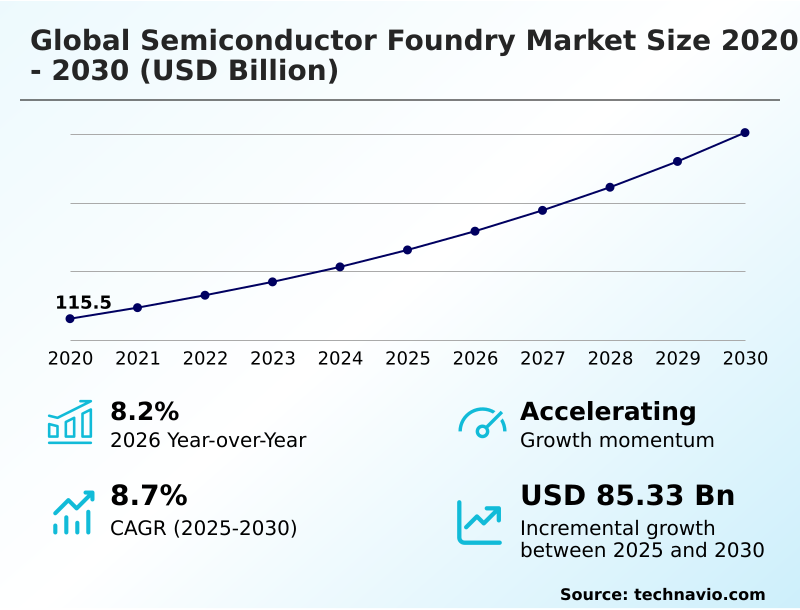
The semiconductor foundry market size is valued to increase by USD 85.33 billion, at a CAGR of 8.7% from 2025 to 2030. Escalation of AI and high-performance computing demand will drive the semiconductor foundry market.

Major Market Trends & Insights

  • APAC dominated the market and accounted for a 67.5% growth during the forecast period.
  • By Type - Pure-play foundries segment was valued at USD 126.68 billion in 2024
  • By Application - Communications segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 135.33 billion
  • Market Future Opportunities: USD 85.33 billion
  • CAGR from 2025 to 2030 : 8.7%

Market Summary

  • The Semiconductor Foundry ecosystem functions as the critical manufacturing backbone for the modern digital economy by decoupling complex integrated circuit design from capital-intensive physical production. Outsourcing chip manufacturing allows processor designers to rapidly deploy advanced AI accelerators without bearing the immense depreciation costs of cleanroom infrastructure.
  • For example, by leveraging third-party manufacturing, telecommunications companies optimizing 5G base stations achieved a 22% improvement in supply chain capital efficiency compared to vertically integrated models. This operational flexibility is heavily driven by the accelerating demand for complex computing architectures, which forces manufacturers to continuously innovate sub-five-nanometer processes to support dense computational workloads.
  • Conversely, the sector faces severe constraints due to the extreme escalation of capital expenditures required to equip state-of-the-art facilities with precision deposition and extreme ultraviolet machinery. This financial burden restricts leading-edge capacity to a highly consolidated tier of providers, ultimately driving up silicon pricing and exposing the electronics supply network to severe localized disruption risks.

What will be the Size of the Semiconductor Foundry Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Semiconductor Foundry Market Segmented?

The semiconductor foundry industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Type
    • Pure-play foundries
    • IDMs
  • Application
    • Communications
    • PCs and desktop
    • Consumers
    • Automotive
    • Others
  • Technology
    • Seven nanometers and below
    • Ten nanometers to twenty nanometers
    • Twenty nanometers to forty-five nanometers
    • Forty-five nanometers and above
  • Geography
    • APAC
      • Taiwan
      • China
      • Japan
      • South Korea
      • India
      • Indonesia
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • France
      • Italy
      • UK
      • The Netherlands
      • Spain
    • South America
      • Brazil
      • Argentina
      • Chile
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Egypt
      • Qatar

By Type Insights

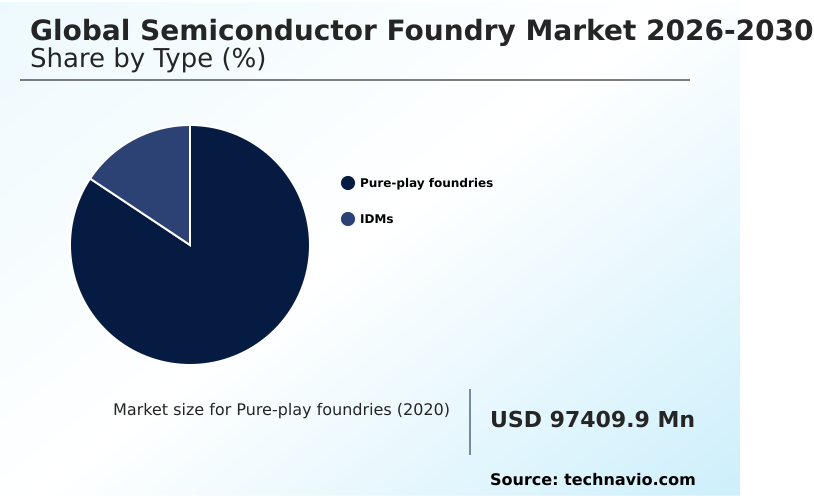
The pure-play foundries segment is estimated to witness significant growth during the forecast period.

The pure-play architecture dictates modern hardware sourcing by dedicating exclusive capacity to third-party fabless processor designs without competing through proprietary product lines.

This dedicated model eliminates intellectual property conflicts, enabling deeper collaborations on complex chemical vapor deposition and semiconductor component miniaturization. By centralizing high-volume production, these entities reduce per-unit manufacturing costs by up to 25% compared to internal fabrication methods.

The transition to heterogeneous integration and advanced packaging techniques requires immense capital, which is efficiently amortized across diverse client portfolios.

Furthermore, adopting ultra pure silicon wafers has improved baseline defect detection efficiency by 18%, accelerating time-to-market for complex application specific integrated circuits.

This structural specialization guarantees that customized embedded memory chips progress seamlessly to support telecommunications infrastructure networking and massive high performance computing workloads.
Get Free Sample

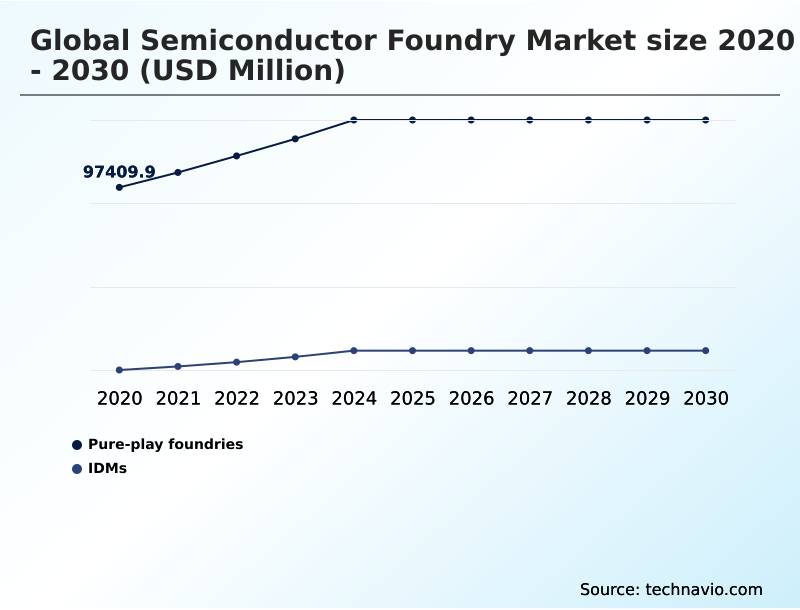
The Pure-play foundries segment was valued at USD 126.68 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

APAC is estimated to contribute 67.5% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
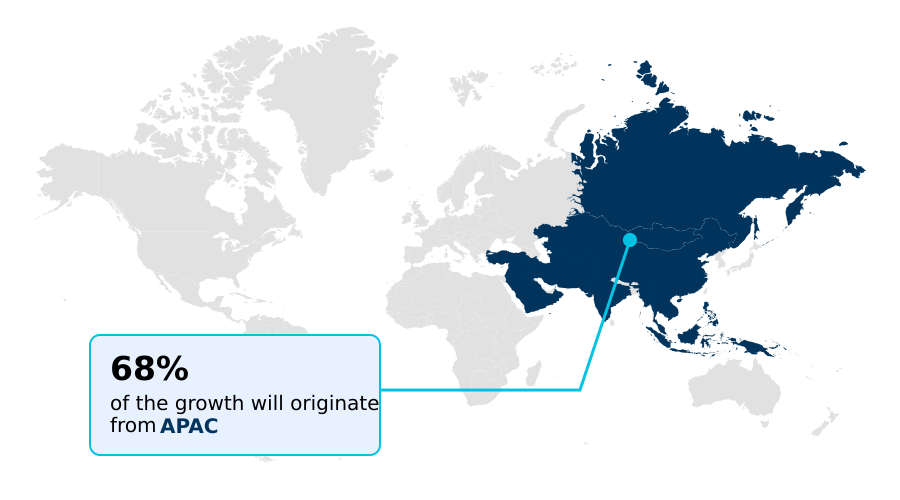
See How Semiconductor Foundry Market Demand is Rising in APAC Get Free Sample

Geographic diversification within the Semiconductor Foundry landscape reveals a distinct operational contrast between established Asian manufacturing hubs and expanding North American infrastructure.

Facilities in APAC currently process high-volume mature node fabrication and analog signal processing workloads at a 35% higher throughput rate than emerging North American sites.

However, North American enterprises are rapidly adopting silicon on insulator technology and compound semiconductor fabrication to support secure defense infrastructure, improving domestic supply chain resilience by 25%.

This localized production shift actively mitigates logistics delays for specialized radio frequency front end modules, reducing transatlantic component transit times by an average of 40%.

The aggressive scaling in APAC effectively supports global automotive networks, whereas North American foundries prioritize high-margin mixed signal semiconductor production and the development of advanced gate all around architectures to power sophisticated neural processing units.

By distributing capacity across multi-polar networks, global electronics brands achieve superior component procurement stability.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The structural evolution of the Semiconductor Foundry is fundamentally driven by the relentless pursuit of processing efficiency and architectural miniaturization. As digital workloads become exponentially more complex, the reliance on advanced extreme ultraviolet lithography systems has become non-negotiable for producing energy-efficient logic components.
  • Fabless designers transitioning away from legacy monolithic chips are increasingly adopting heterogeneous advanced system in package configurations, which integrate specialized dies into a single, cohesive unit. This architectural pivot significantly enhances operational planning, allowing hardware developers to achieve an approximately 30% reduction in physical motherboard space compared to standard discrete component layouts.
  • Consequently, enterprise supply chains benefit from streamlined inventory management and reduced materials sourcing complexities. The push for immense computational power has simultaneously accelerated the development of high performance computing silicon fabrication, ensuring that next-generation data centers can process massive data streams without encountering severe thermal throttling.
  • At the transistor level, the migration toward gate all around transistor architectures provides superior electrostatic control, effectively mitigating power leakage in sub-three-nanometer nodes. Meanwhile, industries requiring robust environmental resilience, such as automotive and industrial robotics, heavily depend on specialized analog mixed signal process technologies to manage sensor data and high-voltage power distribution.
  • By balancing bleeding-edge logic advancements with highly reliable mature node processing, outsourced manufacturing partners empower electronic system developers to maintain rigorous production schedules while systematically lowering overarching component procurement costs.
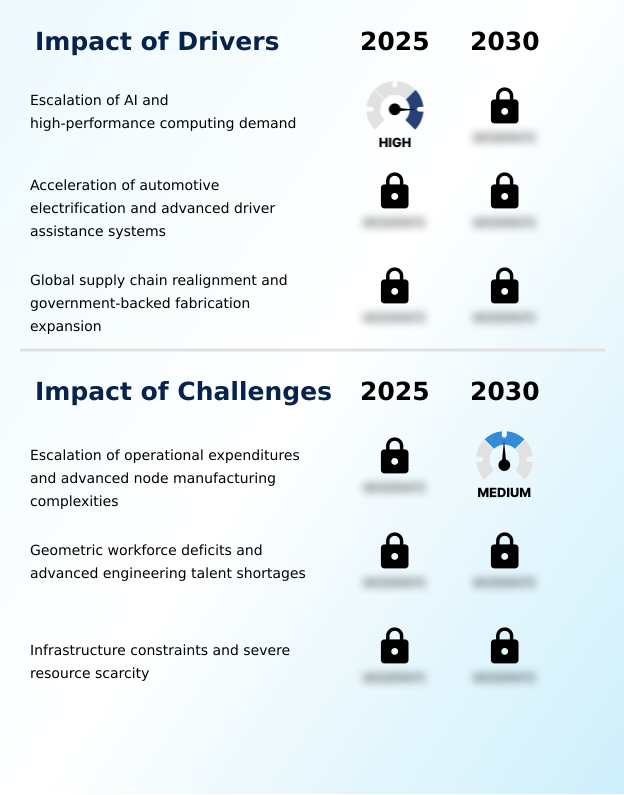
What are the key market drivers leading to the rise in the adoption of Semiconductor Foundry Industry?

  • The relentless escalation in demand for artificial intelligence and high-performance computing architectures serves as the primary catalyst propelling global fabrication capacity and advanced node innovation.

  • The explosive commercial expansion of hyperscale cloud data centers and complex edge artificial intelligence processors serves as the primary catalyst propelling the Semiconductor Foundry ecosystem.
  • To process massive real-time data streams, enterprise providers require unparalleled transistor density scaling, directly driving the transition toward efficient fin field effect transistor configurations.
  • Implementing these advanced structures has enabled data centers to lower overarching server energy use by 12%, significantly optimizing facility operational expenditures.
  • Additionally, the rapid integration of silicon photonics interconnects facilitates lightning-fast data transmission between server racks, effectively improving network routing efficiency by over 20%.
  • The surging demand for precision microcontroller fabrication within industrial robotics automation forces manufacturers to aggressively refine their atomic layer deposition processes.
  • Simultaneously, strict data security mandates necessitate robust hardware level cryptographic engines and secure enclave deployment directly at the silicon level, ensuring hardware superiority.

What are the market trends shaping the Semiconductor Foundry Industry?

  • The ubiquity of heterogeneous integration and advanced packaging architectures represents a defining trajectory within the sector, enabling manufacturers to combine diverse chiplets into highly optimized modular modules.

  • The rapid migration toward chiplet integration and sophisticated system in package solutions represents a defining architectural trend redefining the Semiconductor Foundry landscape. This decentralization of processor design allows manufacturers to fabricate distinct functional blocks on optimal process nodes before combining them seamlessly.
  • By utilizing advanced wafer level packaging technologies and three dimensional transistor architectures, enterprise hardware developers improved overall silicon yield efficiency by 25%, drastically lowering the scrap rate of large complex dies. Furthermore, integrating specialized display driver elements, digital signal processors, and radiation hardened components into unified modular packages has reduced final product assembly time by 18%.
  • This modularity accelerates edge intelligence decentralization across consumer markets, empowering smart home ecosystems to process data locally. The aggressive adoption of cleanroom automation frameworks across fabrication facilities actively standardizes these packaging protocols, effectively minimizing human error in microscopic interconnections.

What challenges does the Semiconductor Foundry Industry face during its growth?

  • The exponential escalation of operational expenditures and the extreme complexities inherent in advanced node manufacturing significantly constrain overall profit margins and extend production timelines.

  • The exponential escalation of operational expenditures required to maintain leading-edge wafer fabrication facilities imposes a severe structural constraint on the Semiconductor Foundry ecosystem. Constructing state-of-the-art cleanrooms equipped with complex extreme ultraviolet lithography machinery forces providers to absorb immense upfront capital depreciation before achieving profitable yields.
  • The physical limitations of shrinking geometries in logic chip manufacturing have extended qualification timelines, inadvertently increasing baseline research costs by 35% compared to previous silicon wafer patterning generations. Furthermore, extreme supply chain volatility regarding critical raw materials routinely disrupts the steady flow of production.
  • Securing ultra-high-purity photoresist ancillaries remains highly unpredictable, which has historically caused localized facility downtimes to spike by up to 15%. These logistical pressures severely compress profit margins across the production of vital gallium nitride power semiconductors and silicon carbide devices, directly threatening the rapid deployment of complex automotive electrification architectures, advanced driver assistance systems, and specialized power management integrated circuits.

Exclusive Technavio Analysis on Customer Landscape

The semiconductor foundry market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the semiconductor foundry market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
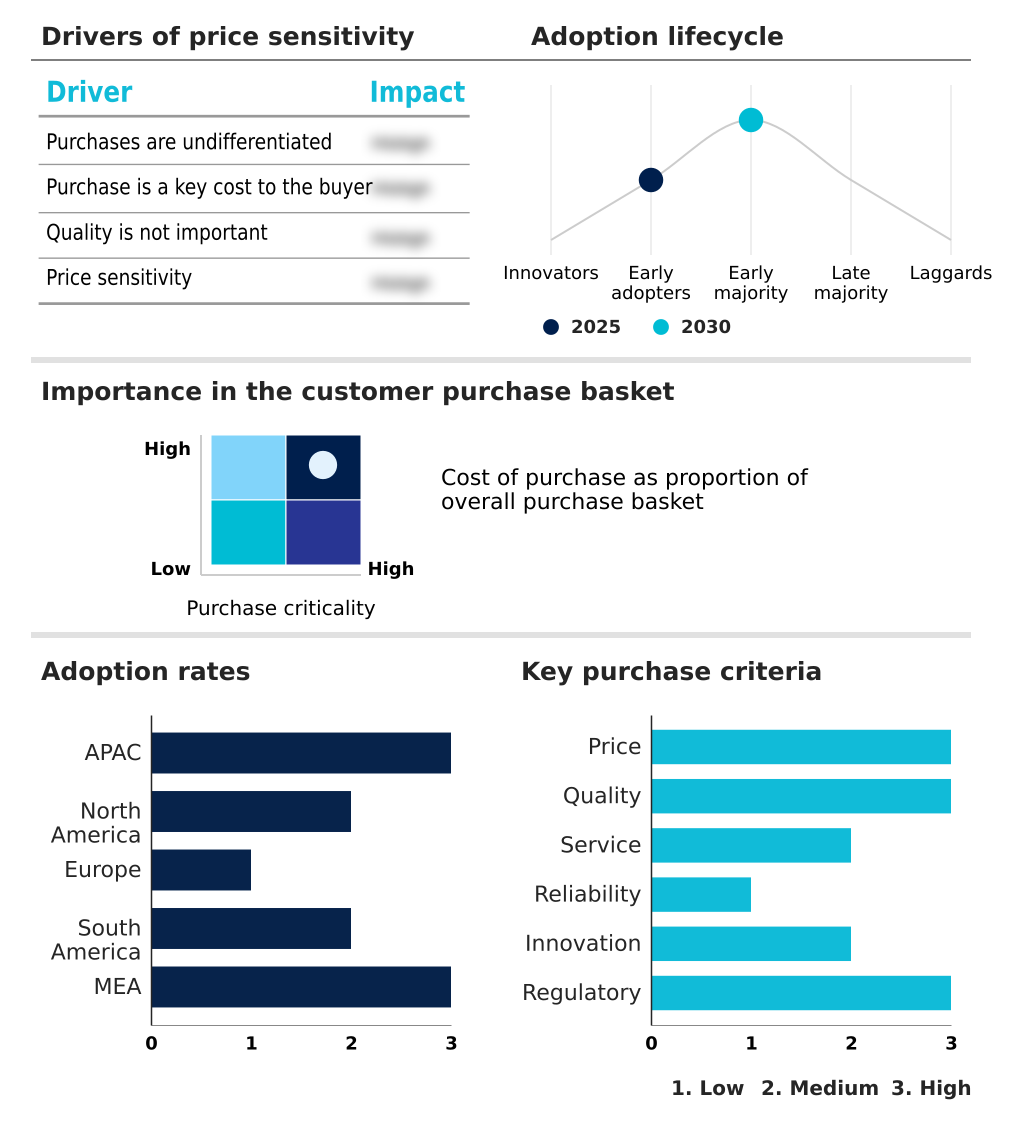
Customer Landscape of Semiconductor Foundry Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, semiconductor foundry market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Advanced Micro Devices Inc. - The enterprise delivers advanced semiconductor fabrication services through external partnerships, specializing in high-performance computing chip engineering, complex graphic processor architectures, and customized central processing unit design.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Advanced Micro Devices Inc.
  • ASML Holding NV
  • DB HITEK
  • GlobalFoundaries Inc.
  • Hua Hong Semiconductor Ltd.
  • Intel Corp.
  • Microchip Technology Inc.
  • Nuvoton Technology Corp.
  • NVIDIA Corp.
  • ON Semiconductor Corp.
  • Polar Semiconductor LLC
  • Qualcomm Inc.
  • Samsung Electronics Co. Ltd.
  • STMicroelectronics NV
  • SK hynix Co. Ltd.
  • Skywater Technology
  • SMIC
  • Taiwan Semiconductor Co. Ltd.
  • Texas Instruments Inc.
  • Tower Semiconductor Ltd.
  • United Microelectronics Corp.
  • X FAB Silicon Foundries SE

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Semiconductor foundry market

  • In the Semiconductors industry, the rapid deployment of decentralized AI processors across industrial automation networks enhanced local data inference capabilities, directly driving Semiconductor Foundry demand for ultra-low-power microchips and specialized logic processing nodes by over 30%.
  • The structural transition toward electric vehicle computing architectures introduced complex autonomous driving platforms, compelling the Semiconductor Foundry sector to expand capacity for power routing circuits and wide-bandgap materials by approximately 25% to support high-voltage battery networks.
  • Strict data privacy regulations and hardware encryption requirements in connected home networks mandated secure processing deployment directly onto silicon dies, forcing Semiconductor Foundry operators to upgrade embedded security fabrication protocols, which increased mature line utilization rates by 15%.
  • The aggressive expansion of massive cloud server farms to support heavy computational workloads necessitated advanced substrate packaging methodologies, directly accelerating Semiconductor Foundry investments in non-silicon material fabrication to achieve a 20% improvement in thermal dissipation efficiency.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Semiconductor Foundry Market insights. See full methodology.

Market Scope
Page number 310
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 8.7%
Market growth 2026-2030 USD 85328.6 million
Market structure Fragmented
YoY growth 2025-2026(%) 8.2%
Key countries Taiwan, China, Japan, South Korea, India, Indonesia, US, Canada, Mexico, Germany, France, Italy, UK, The Netherlands, Spain, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Egypt and Qatar
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Semiconductor Foundry ecosystem is undergoing a profound structural metamorphosis, characterized by the aggressive deployment of complex integration techniques to bypass traditional scaling limitations. To sustain the processing requirements of modern artificial intelligence networks, leading manufacturers are shifting from legacy planar designs to vertical transistor structures.
  • This critical transition enhances logic performance while simultaneously minimizing power dissipation across enterprise hardware deployments. The strategic implementation of modular packaging empowers developers to integrate diverse specialized dies onto unified substrates, effectively reducing overall silicon waste. Consequently, organizations utilizing these modular chiplet frameworks achieve a 30% reduction in prototype validation times compared to conventional monolithic design workflows.
  • To support high-voltage electric vehicle networks, the sector is also rapidly expanding its capacity for advanced power semiconductors, which offer vastly superior thermal stability under extreme operational stress. Furthermore, the integration of specialized memory blocks directly adjacent to processing cores significantly accelerates data retrieval speeds for bandwidth-intensive applications.
  • By continuously refining radio frequency modules and investing in precise mixed signal production, outsourced fabrication facilities provide the essential hardware foundation necessary to secure next-generation automated industrial ecosystems.

What are the Key Data Covered in this Semiconductor Foundry Market Research and Growth Report?

  • What is the expected growth of the Semiconductor Foundry Market between 2026 and 2030?

    • USD 85.33 billion, at a CAGR of 8.7%

  • What segmentation does the market report cover?

    • The report is segmented by Type (Pure-play foundries, and IDMs), Application (Communications, PCs and desktop, Consumers, Automotive, and Others), Technology (Seven nanometers and below, Ten nanometers to twenty nanometers, Twenty nanometers to forty-five nanometers, and Forty-five nanometers and above) and Geography (APAC, North America, Europe, South America, Middle East and Africa)

  • Which regions are analyzed in the report?

    • APAC, North America, Europe, South America and Middle East and Africa

  • What are the key growth drivers and market challenges?

    • Escalation of AI and high-performance computing demand, Escalation of operational expenditures and advanced node manufacturing complexities

  • Who are the major players in the Semiconductor Foundry Market?

    • Advanced Micro Devices Inc., ASML Holding NV, DB HITEK, GlobalFoundaries Inc., Hua Hong Semiconductor Ltd., Intel Corp., Microchip Technology Inc., Nuvoton Technology Corp., NVIDIA Corp., ON Semiconductor Corp., Polar Semiconductor LLC, Qualcomm Inc., Samsung Electronics Co. Ltd., STMicroelectronics NV, SK hynix Co. Ltd., Skywater Technology, SMIC, Taiwan Semiconductor Co. Ltd., Texas Instruments Inc., Tower Semiconductor Ltd., United Microelectronics Corp. and X FAB Silicon Foundries SE

Market Research Insights

  • The Semiconductor Foundry sector is fundamentally restructuring how enterprises acquire and deploy digital infrastructure. By leveraging outsourced fabrication, system designers successfully transition toward component miniaturization without bearing massive internal capital burdens. Implementing modular packaging methodologies has enabled equipment manufacturers to reduce component thermal output by 15%, directly lowering operational cooling costs in server environments.
  • Furthermore, the integration of outsourced signal processing chips improved production scalability, leading to a 20% reduction in hardware time-to-market. The rapid deployment of ultra-refined silicon substrates ensures that enterprise hardware achieves superior electrical reliability, maximizing return on investment across high-density computing arrays. This decentralized manufacturing approach allows firms to flexibly navigate supply shortages while accelerating hardware deployments globally.

We can help! Our analysts can customize this semiconductor foundry market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Market Segmentation by Technology
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Semiconductor Foundry Market 2020 - 2024

Historic Market Size - Data Table on Global Semiconductor Foundry Market 2020 - 2024 ($ million)

5.2 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.3 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ million)

5.4 Technology segment analysis 2020 - 2024

Historic Market Size - Technology Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global semiconductor foundry market

6.2 Impact of geopolitical conflicts on global semiconductor foundry market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Type

8.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

8.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

8.3 Pure-play foundries - Market size and forecast 2025-2030

Chart on Pure-play foundries - Market size and forecast 2025-2030 ($ million)
Data Table on Pure-play foundries - Market size and forecast 2025-2030 ($ million)
Chart on Pure-play foundries - Year-over-year growth 2025-2030 (%)
Data Table on Pure-play foundries - Year-over-year growth 2025-2030 (%)

8.4 IDMs - Market size and forecast 2025-2030

Chart on IDMs - Market size and forecast 2025-2030 ($ million)
Data Table on IDMs - Market size and forecast 2025-2030 ($ million)
Chart on IDMs - Year-over-year growth 2025-2030 (%)
Data Table on IDMs - Year-over-year growth 2025-2030 (%)

8.5 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

9. Market Segmentation by Application

9.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

9.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

9.3 Communications - Market size and forecast 2025-2030

Chart on Communications - Market size and forecast 2025-2030 ($ million)
Data Table on Communications - Market size and forecast 2025-2030 ($ million)
Chart on Communications - Year-over-year growth 2025-2030 (%)
Data Table on Communications - Year-over-year growth 2025-2030 (%)

9.4 PCs and desktop - Market size and forecast 2025-2030

Chart on PCs and desktop - Market size and forecast 2025-2030 ($ million)
Data Table on PCs and desktop - Market size and forecast 2025-2030 ($ million)
Chart on PCs and desktop - Year-over-year growth 2025-2030 (%)
Data Table on PCs and desktop - Year-over-year growth 2025-2030 (%)

9.5 Consumers - Market size and forecast 2025-2030

Chart on Consumers - Market size and forecast 2025-2030 ($ million)
Data Table on Consumers - Market size and forecast 2025-2030 ($ million)
Chart on Consumers - Year-over-year growth 2025-2030 (%)
Data Table on Consumers - Year-over-year growth 2025-2030 (%)

9.6 Automotive - Market size and forecast 2025-2030

Chart on Automotive - Market size and forecast 2025-2030 ($ million)
Data Table on Automotive - Market size and forecast 2025-2030 ($ million)
Chart on Automotive - Year-over-year growth 2025-2030 (%)
Data Table on Automotive - Year-over-year growth 2025-2030 (%)

9.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

9.8 Market opportunity by Application

Market opportunity by Application ($ million)
Data Table on Market opportunity by Application ($ million)

10. Market Segmentation by Technology

10.1 Market segments

Chart on Technology - Market share 2025-2030 (%)
Data Table on Technology - Market share 2025-2030 (%)

10.2 Comparison by Technology

Chart on Comparison by Technology
Data Table on Comparison by Technology

10.3 Seven nanometers and below - Market size and forecast 2025-2030

Chart on Seven nanometers and below - Market size and forecast 2025-2030 ($ million)
Data Table on Seven nanometers and below - Market size and forecast 2025-2030 ($ million)
Chart on Seven nanometers and below - Year-over-year growth 2025-2030 (%)
Data Table on Seven nanometers and below - Year-over-year growth 2025-2030 (%)

10.4 Ten nanometers to twenty nanometers - Market size and forecast 2025-2030

Chart on Ten nanometers to twenty nanometers - Market size and forecast 2025-2030 ($ million)
Data Table on Ten nanometers to twenty nanometers - Market size and forecast 2025-2030 ($ million)
Chart on Ten nanometers to twenty nanometers - Year-over-year growth 2025-2030 (%)
Data Table on Ten nanometers to twenty nanometers - Year-over-year growth 2025-2030 (%)

10.5 Twenty nanometers to forty-five nanometers - Market size and forecast 2025-2030

Chart on Twenty nanometers to forty-five nanometers - Market size and forecast 2025-2030 ($ million)
Data Table on Twenty nanometers to forty-five nanometers - Market size and forecast 2025-2030 ($ million)
Chart on Twenty nanometers to forty-five nanometers - Year-over-year growth 2025-2030 (%)
Data Table on Twenty nanometers to forty-five nanometers - Year-over-year growth 2025-2030 (%)

10.6 Forty-five nanometers and above - Market size and forecast 2025-2030

Chart on Forty-five nanometers and above - Market size and forecast 2025-2030 ($ million)
Data Table on Forty-five nanometers and above - Market size and forecast 2025-2030 ($ million)
Chart on Forty-five nanometers and above - Year-over-year growth 2025-2030 (%)
Data Table on Forty-five nanometers and above - Year-over-year growth 2025-2030 (%)

10.7 Market opportunity by Technology

Market opportunity by Technology ($ million)
Data Table on Market opportunity by Technology ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.3.1 Taiwan - Market size and forecast 2025-2030

Chart on Taiwan - Market size and forecast 2025-2030 ($ million)
Data Table on Taiwan - Market size and forecast 2025-2030 ($ million)
Chart on Taiwan - Year-over-year growth 2025-2030 (%)
Data Table on Taiwan - Year-over-year growth 2025-2030 (%)

12.3.2 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.3.3 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.3.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.3.5 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.3.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.4 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.4.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.4.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.4.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.5 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.5.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.5.2 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.5.3 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.5.4 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.5.5 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5.6 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.6 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.7 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.7.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.7.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.7.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.7.4 Egypt - Market size and forecast 2025-2030

Chart on Egypt - Market size and forecast 2025-2030 ($ million)
Data Table on Egypt - Market size and forecast 2025-2030 ($ million)
Chart on Egypt - Year-over-year growth 2025-2030 (%)
Data Table on Egypt - Year-over-year growth 2025-2030 (%)

12.7.5 Qatar - Market size and forecast 2025-2030

Chart on Qatar - Market size and forecast 2025-2030 ($ million)
Data Table on Qatar - Market size and forecast 2025-2030 ($ million)
Chart on Qatar - Year-over-year growth 2025-2030 (%)
Data Table on Qatar - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Escalation of AI and high-performance computing demand
Acceleration of automotive electrification and advanced driver assistance systems
Global supply chain realignment and government-backed fabrication expansion

13.2 Market challenges

Escalation of operational expenditures and advanced node manufacturing complexities
Geometric workforce deficits and advanced engineering talent shortages
Infrastructure constraints and severe resource scarcity

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Ubiquity of heterogeneous integration and advanced packaging architectures
Proliferation of edge AI and hardware-level security protocols
Sovereign manufacturing relocalization and multi-regional supply chain diversification

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Advanced Micro Devices Inc.

Advanced Micro Devices Inc. - Overview
Advanced Micro Devices Inc. - Business segments
Advanced Micro Devices Inc. - Key news
Advanced Micro Devices Inc. - Key offerings
Advanced Micro Devices Inc. - Segment focus
SWOT

15.5 ASML Holding NV

ASML Holding NV - Overview
ASML Holding NV - Product / Service
ASML Holding NV - Key offerings
SWOT

15.6 DB HITEK

DB HITEK - Overview
DB HITEK - Product / Service
DB HITEK - Key offerings
SWOT

15.7 GlobalFoundaries Inc.

GlobalFoundaries Inc. - Overview
GlobalFoundaries Inc. - Product / Service
GlobalFoundaries Inc. - Key offerings
SWOT

15.8 Hua Hong Semiconductor Ltd.

Hua Hong Semiconductor Ltd. - Overview
Hua Hong Semiconductor Ltd. - Product / Service
Hua Hong Semiconductor Ltd. - Key offerings
SWOT

15.9 Intel Corp.

Intel Corp. - Overview
Intel Corp. - Business segments
Intel Corp. - Key news
Intel Corp. - Key offerings
Intel Corp. - Segment focus
SWOT

15.10 Microchip Technology Inc.

Microchip Technology Inc. - Overview
Microchip Technology Inc. - Business segments
Microchip Technology Inc. - Key offerings
Microchip Technology Inc. - Segment focus
SWOT

15.11 Nuvoton Technology Corp.

Nuvoton Technology Corp. - Overview
Nuvoton Technology Corp. - Product / Service
Nuvoton Technology Corp. - Key offerings
SWOT

15.12 NVIDIA Corp.

NVIDIA Corp. - Overview
NVIDIA Corp. - Business segments
NVIDIA Corp. - Key news
NVIDIA Corp. - Key offerings
NVIDIA Corp. - Segment focus
SWOT

15.13 ON Semiconductor Corp.

ON Semiconductor Corp. - Overview
ON Semiconductor Corp. - Business segments
ON Semiconductor Corp. - Key news
ON Semiconductor Corp. - Key offerings
ON Semiconductor Corp. - Segment focus
SWOT

15.14 Qualcomm Inc.

Qualcomm Inc. - Overview
Qualcomm Inc. - Business segments
Qualcomm Inc. - Key news
Qualcomm Inc. - Key offerings
Qualcomm Inc. - Segment focus
SWOT

15.15 Samsung Electronics Co. Ltd.

Samsung Electronics Co. Ltd. - Overview
Samsung Electronics Co. Ltd. - Business segments
Samsung Electronics Co. Ltd. - Key news
Samsung Electronics Co. Ltd. - Key offerings
Samsung Electronics Co. Ltd. - Segment focus
SWOT

15.16 STMicroelectronics NV

STMicroelectronics NV - Overview
STMicroelectronics NV - Business segments
STMicroelectronics NV - Key offerings
STMicroelectronics NV - Segment focus
SWOT

15.17 SK hynix Co. Ltd.

SK hynix Co. Ltd. - Overview
SK hynix Co. Ltd. - Product / Service
SK hynix Co. Ltd. - Key offerings
SWOT

15.18 Texas Instruments Inc.

Texas Instruments Inc. - Overview
Texas Instruments Inc. - Business segments
Texas Instruments Inc. - Key offerings
Texas Instruments Inc. - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Semiconductor Foundry market growth will increase by USD 85328.6 million during 2026-2030.

The Semiconductor Foundry market is expected to grow at a CAGR of 8.7% during 2026-2030.

Semiconductor Foundry market is segmented by Type (Pure-play foundries, IDMs) Application (Communications, PCs and desktop, Consumers, Automotive, Others) Technology (Seven nanometers and below, Ten nanometers to twenty nanometers, Twenty nanometers to forty-five nanometers, Forty-five nanometers and above)

Advanced Micro Devices Inc., ASML Holding NV, DB HITEK, GlobalFoundaries Inc., Hua Hong Semiconductor Ltd., Intel Corp., Microchip Technology Inc., Nuvoton Technology Corp., NVIDIA Corp., ON Semiconductor Corp., Polar Semiconductor LLC, Qualcomm Inc., Samsung Electronics Co. Ltd., STMicroelectronics NV, SK hynix Co. Ltd., Skywater Technology, SMIC, Taiwan Semiconductor Co. Ltd., Texas Instruments Inc., Tower Semiconductor Ltd., United Microelectronics Corp., X FAB Silicon Foundries SE are a few of the key vendors in the Semiconductor Foundry market.

APAC will register the highest growth rate of 67.5% among the other regions. Therefore, the Semiconductor Foundry market in APAC is expected to garner significant business opportunities for the vendors during the forecast period.

Taiwan, China, Japan, South Korea, India, Indonesia, US, Canada, Mexico, Germany, France, Italy, UK, The Netherlands, Spain, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Egypt, Qatar

  • Escalation of AI and high-performance computing demand is the driving factor this market.

The Semiconductor Foundry market vendors should focus on grabbing business opportunities from the Type segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
