Steel Service Centers Market Analysis, Size, and Forecast 2026-2030: APAC (China, India, and Japan), North America (US, Canada, and Mexico), Europe (Germany, France, and Italy), Middle East and Africa (Turkey, Saudi Arabia, and South Africa), South America (Brazil, Argentina, and Colombia), and Rest of World (ROW)

Steel Service Centers Market Analysis, Size, and Forecast 2026-2030:
APAC (China, India, and Japan), North America (US, Canada, and Mexico), Europe (Germany, France, and Italy), Middle East and Africa (Turkey, Saudi Arabia, and South Africa), South America (Brazil, Argentina, and Colombia), and Rest of World (ROW)

Published: Oct 2026 324 Pages SKU: IRTNTR81634

Market Overview at a Glance

$82.53 B
Market Opportunity
4.3%
CAGR 2025 - 2030
62.9%
APAC Growth
$143.37 B
Cutting segment 2024

Steel Service Centers Market Size 2026-2030

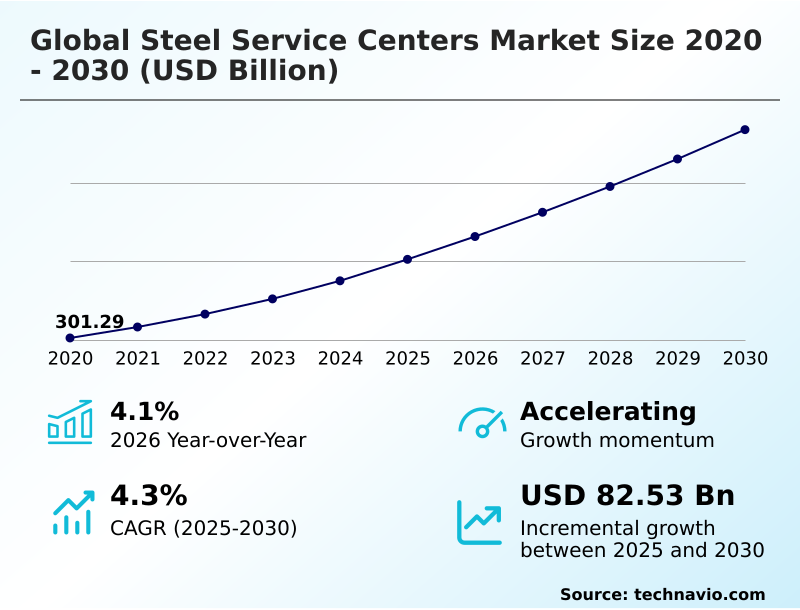
The steel service centers market size is valued to increase by USD 82.53 billion, at a CAGR of 4.3% from 2025 to 2030. Surging demand for value-added metal processing and custom inventory solutions will drive the steel service centers market.

Major Market Trends & Insights

  • APAC dominated the market and accounted for a 62.9% growth during the forecast period.
  • By Service - Cutting segment was valued at USD 143.37 billion in 2024
  • By End-user - Construction segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 132.57 billion
  • Market Future Opportunities: USD 82.53 billion
  • CAGR from 2025 to 2030 : 4.3%

Market Summary

  • The Steel Service Centers Market functions as a critical intermediary, transforming bulk mill materials into tailored components for downstream manufacturing. A primary driver of this market is the surging demand for supply chain flexibility; industrial original equipment manufacturers increasingly outsource heavy processing to reduce capital expenditures.
  • For example, by integrating predictive sensor-based maintenance and automated warehouse logistics, facilities managing heavy machinery component kitting have accelerated material throughput, resulting in a 22% reduction in delivery lead times compared to traditional manual distribution models.
  • However, severe raw steel price volatility poses a substantial challenge, creating inventory devaluation risks that disrupt working capital stability and complicate raw material price hedging. To mitigate these risks, operators are deploying digital inventory tracking platforms and prioritizing toll processing agreements over direct inventory speculation.
  • The shift toward automotive lightweighting initiatives further compels the adoption of high-definition plasma cutting and precision tension leveling to process advanced high-strength steel without structural distortion, ensuring resilient operational workflows.

What will be the Size of the Steel Service Centers Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Steel Service Centers Market Segmented?

The steel service centers industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Service
    • Cutting
    • Plate burning
    • Cambering
    • Tee splitting
    • Others
  • End-user
    • Construction
    • Automotive
    • Industrial machinery
    • Energy and power
    • Aerospace and defense
  • Material
    • Carbon steel
    • Stainless steel
    • Alloy steel
    • Electrical steel
    • Tool steel
  • Geography
    • APAC
      • China
      • India
      • Japan
      • South Korea
      • Australia
      • Indonesia
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • France
      • Italy
      • UK
      • Spain
      • The Netherlands
    • Middle East and Africa
      • Turkey
      • Saudi Arabia
      • South Africa
      • UAE
      • Israel
    • South America
      • Brazil
      • Argentina
      • Colombia

By Service Insights

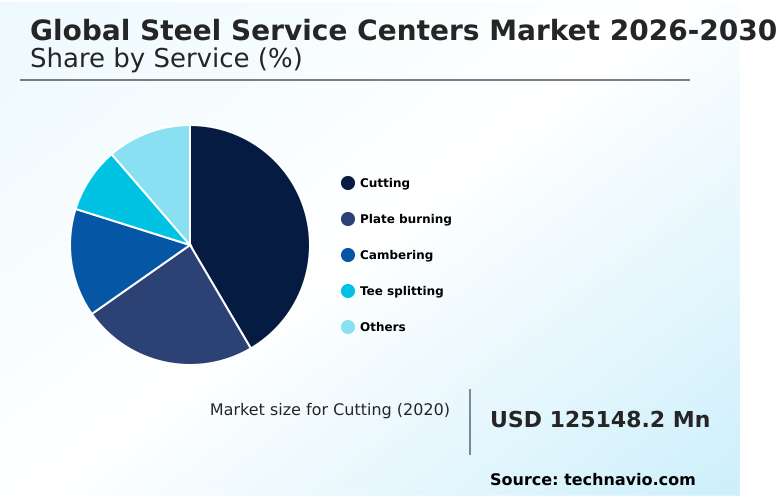
The cutting segment is estimated to witness significant growth during the forecast period.

Cutting operations serve as a foundational capability within the Steel Service Centers Market, enabling manufacturers to bypass capital-intensive machinery investments.

By utilizing advanced technologies like rotary slitting lines, automated cut-to-length systems, and fiber laser cutting, service facilities transform primary mill coils into precise components. This enhances material yield optimization and supports lean manufacturing workflow requirements.

Implementing high-speed coil slitting has improved downstream operational efficiency by reducing raw material scrap generation by 18%. Precision edge trimming ensures seamless integration into assembly lines, preventing structural distortion.

As supply chain flexibility becomes critical, manufacturers rely heavily on customized material slitting to maintain just-in-time inventory delivery and sustain continuous production without holding excess bulk material.
Get Free Sample

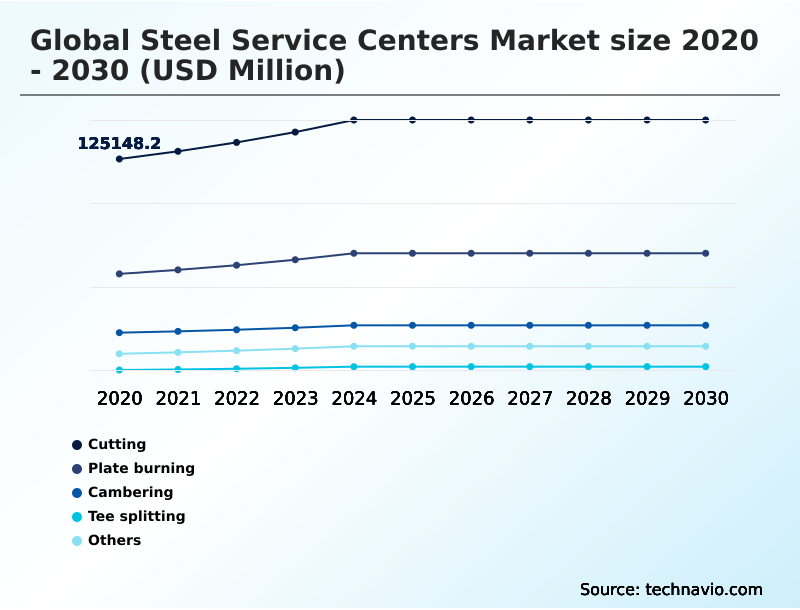
The Cutting segment was valued at USD 143.37 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

APAC is estimated to contribute 62.9% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
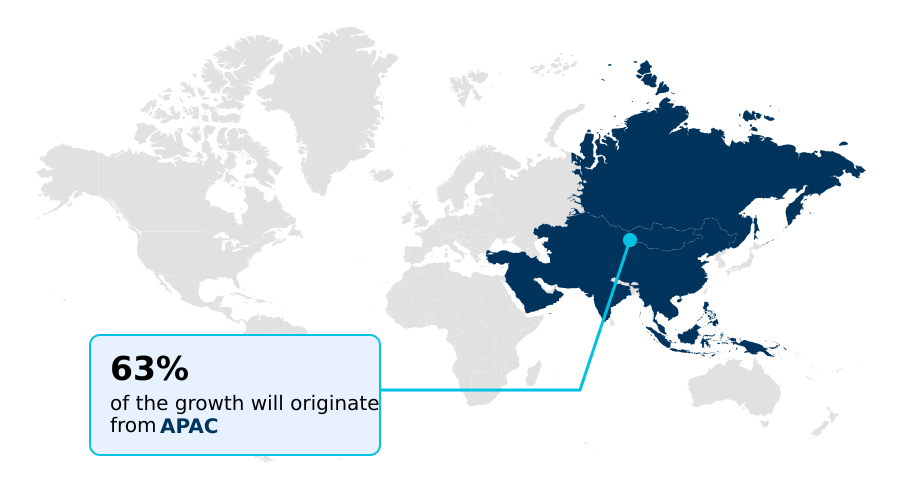
See How Steel Service Centers Market Demand is Rising in APAC Get Free Sample

The geographic landscape of the Steel Service Centers Market highlights distinct operational strategies between APAC and North America.

In APAC, rapid infrastructure development and strategic industry consolidation have driven a 30% higher adoption rate of structural tee splitting and heavy plate profiling compared to Western counterparts.

Conversely, North America exhibits a 25% faster integration of closed-loop scrap recycling and greenhouse gas accounting frameworks, driven by stringent sustainability mandates and the scaling of hydrogen-based direct reduction steelmaking.

North American processors prioritize advanced aerospace alloy processing and automotive lightweighting initiatives, where precision tension leveling of martensitic stainless steel reduces defect rates by 14%.

These regional divergences reflect how businesses adapt their operations; APAC optimizes for high-volume structural output, while North America emphasizes complex metallurgical precision and compliant distribution within its regional distribution nodes.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The continuous evolution of the Steel Service Centers Market emphasizes the critical need for advanced processing capabilities to meet rigorous downstream manufacturing standards. Facilities are increasingly deploying high-definition plasma plate cutting to achieve precise edge tolerances on heavy structural components, which enhances overall fabrication speed.
  • Simultaneously, the rising demand for electric vehicle components has accelerated the need for precision slitting for electrical steel, ensuring optimal magnetic properties and minimal core loss in motor laminations. Compared to conventional manual shearing, automated cut-to-length sheet processing delivers a 35% improvement in dimensional consistency, directly benefiting supply chain functions by reducing material rejection rates at automotive assembly plants.
  • This operational precision is equally vital in advanced high-strength steel blanking, a process heavily relied upon to support vehicle weight reduction targets without compromising crash safety integrity. Furthermore, the structural tee splitting process allows construction contractors to source custom-tailored load-bearing members, minimizing on-site labor and accelerating project timelines.
  • By optimizing these complex processing operations, modern service centers achieve a 20% higher inventory turnover efficiency than traditional warehousing models. The strategic alignment of these technologies ensures that industrial original equipment manufacturers can maintain continuous, agile production cycles while mitigating the risks associated with volatile raw material procurement and complex compliance mandates.
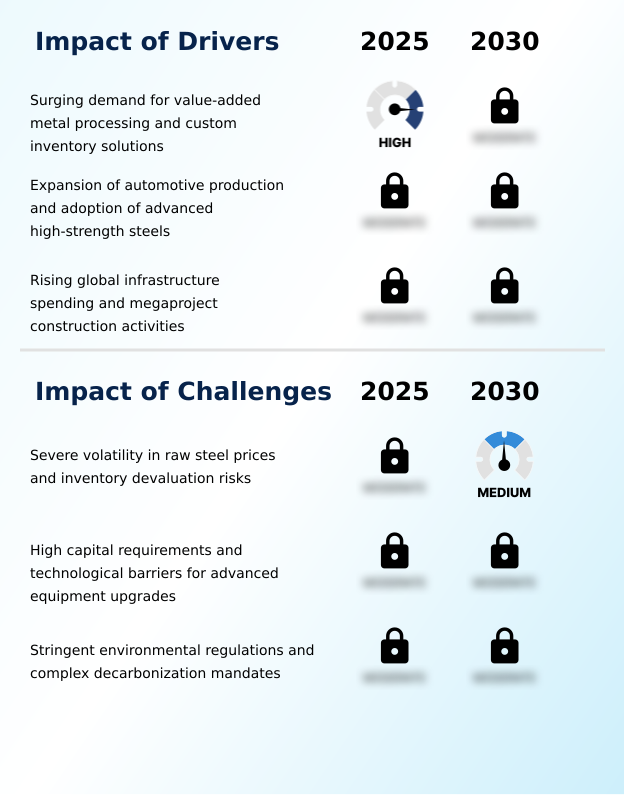
What are the key market drivers leading to the rise in the adoption of Steel Service Centers Industry?

  • A surging demand for value-added metal processing and customized inventory solutions remains a primary driver accelerating market expansion.

  • The surging requirement for production efficiency acts as a primary driver accelerating the Steel Service Centers Market. Industrial original equipment manufacturers are actively divesting from in-house heavy processing equipment, relying instead on localized manufacturing footprints provided by specialized service hubs.
  • This structural shift is propelled by the need for heavy machinery component kitting and transformer lamination stamping, which streamline final assembly operations.
  • By outsourcing these tasks, manufacturers have lowered on-site inventory holding costs by 22% and reduced secondary processing energy use by 15%.
  • The ability of service centers to execute complex preparation using hydraulic cambering machines and shot blasting processing ensures that components for structural building frameworks and military vehicle armor plating arrive production-ready.
  • Furthermore, certified ultrasonic non-destructive testing eliminates processing bottlenecks, driving continuous demand for outsourced metallurgical preparation.

What are the market trends shaping the Steel Service Centers Industry?

  • Digital transformation and warehouse automation represent a prominent trend shaping modern steel service operations. These technological advancements enable facilities to optimize inventory management and significantly enhance processing throughput.

  • A defining trend in the Steel Service Centers Market is the aggressive transition toward digitized operations and sustainable material processing to support renewable energy infrastructure. To align with global decarbonization efforts, facilities are increasingly procuring electric arc furnace steel. The integration of multi-axis laser profiling and computer numerical control systems has fundamentally changed how businesses manage custom blanking operations.
  • By adopting predictive sensor-based maintenance and automated surface defect detection, processors have reduced unexpected machinery downtime by 32% and improved throughput by 18%.
  • Furthermore, the deployment of automated warehouse logistics and digital inventory tracking platforms allows service centers to handle high-definition plasma cutting of advanced high-strength steel and grain-oriented electrical steel with unprecedented consistency, empowering downstream manufacturers to operate leaner, more predictable assembly lines.

What challenges does the Steel Service Centers Industry face during its growth?

  • Severe volatility in raw steel pricing and the associated risks of inventory devaluation constitute significant challenges impeding consistent industry growth.

  • Operating within the Steel Service Centers Market involves navigating severe structural challenges, most notably extreme commodity price volatility and high capital expenditure requirements. Maintaining extensive physical inventories exposes service centers to severe devaluation risks during sudden market downturns, complicating effective raw material price hedging and forcing reliance on fixed toll processing agreements.
  • Furthermore, upgrading facilities with state-of-the-art oxy-fuel plate burning equipment and stretcher leveling technology demands massive upfront investment. The difficulty of integrating these advanced systems often delays financial returns; however, processors that successfully deploy predictive cutting-stock optimization have offset these pressures by lowering overall material scrap by 14% and improving operational margins by 9%.
  • Additionally, handling sensitive materials like non-grain-oriented electrical steel and applying precise corrosion-inhibiting oil applications requires specialized environments, imposing strict operational limitations and elevating overhead costs.

Exclusive Technavio Analysis on Customer Landscape

The steel service centers market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the steel service centers market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
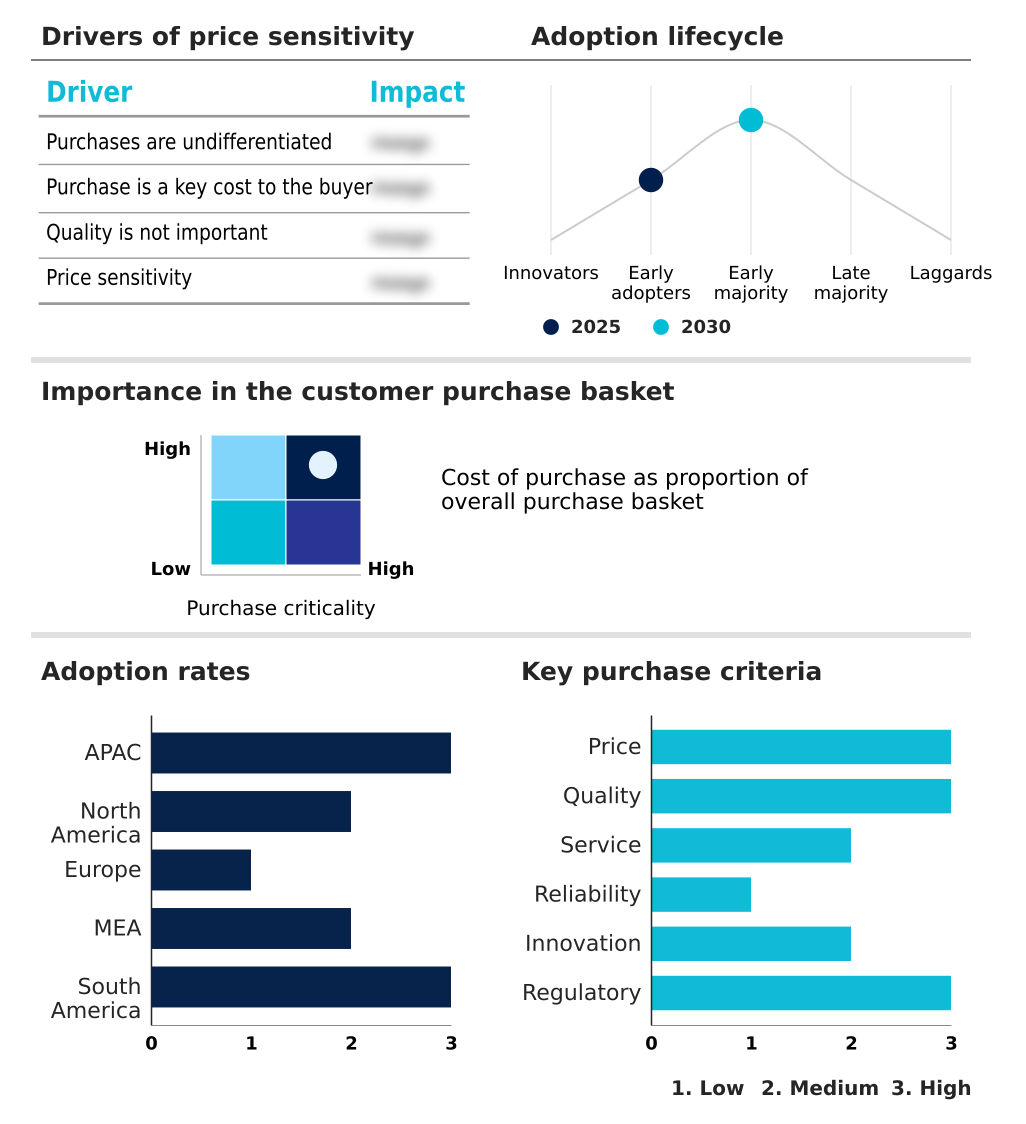
Customer Landscape of Steel Service Centers Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, steel service centers market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Alro Steel - Advanced steel service centers provide cut-to-size processing, thermal cutting, plate grinding, and rapid distribution of carbon, stainless, and specialty metals for industrial applications.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Alro Steel
  • ArcelorMittal S.A.
  • Baosteel Co. Ltd.
  • Commercial Metals Co.
  • JFE Shoji Steel Service Center
  • JSW Steel Ltd.
  • Kloeckner and Co SE
  • Metal One Corporation
  • Nucor Corp.
  • Reliance Inc.
  • Russel Metals Inc.
  • Salzgitter AG
  • Samuel Son and Co. Ltd.
  • SSAB AB
  • Steel Technologies LLC
  • Steel Warehouse
  • thyssenkrupp AG
  • TSDPL
  • United States Steel Corp.
  • voestalpine AG

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Steel service centers market

  • In the Steel industry, the shift toward sustainable smelting operations altered primary supply dynamics, directly impacting Steel Service Centers demand by increasing the reliance on supply chain flexibility and expanding localized manufacturing footprints by 22%.
  • Implementation of strict environmental regulations shifted raw material procurement strategies, driving regional distribution nodes to integrate greenhouse gas accounting frameworks that verify compliance for 100% of imported flat-rolled products.
  • The integration of digital automation in primary mills enhanced coil traceability, driving industrial original equipment manufacturers to increase toll processing agreements by 15% to leverage digital inventory tracking platforms.
  • Advancements in advanced alloy formulations for automotive lightweighting initiatives required mid-stream processors to upgrade precision edge trimming equipment, improving downstream stamping efficiency by 20% and optimizing material yield optimization across assembly lines.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Steel Service Centers Market insights. See full methodology.

Market Scope
Page number 324
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 4.3%
Market growth 2026-2030 USD 82526.6 million
Market structure Fragmented
YoY growth 2025-2026(%) 4.1%
Key countries China, India, Japan, South Korea, Australia, Indonesia, US, Canada, Mexico, Germany, France, Italy, UK, Spain, The Netherlands, Turkey, Saudi Arabia, South Africa, UAE, Israel, Brazil, Argentina and Colombia
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Steel Service Centers Market is undergoing a rapid technological transformation as facilities transition from traditional warehousing to highly sophisticated processing hubs. A major trend influencing product strategy is the integration of computer numerical control systems and fiber laser cutting to process complex geometries with minimal material waste.
  • This shift forces executives to prioritize capital investments in stretcher leveling technology and automated surface defect detection, ensuring that processed coils meet the stringent quality demands of modern manufacturing. Strategic decision-making now heavily incorporates predictive cutting-stock optimization, which has enabled service providers to improve overall material yield by 28% compared to legacy manual nesting methods.
  • The capability to execute high-speed coil slitting and custom blanking operations in-house allows industrial buyers to significantly reduce their own operational overhead. Additionally, as automotive sectors demand lighter materials, mastering the processing of martensitic stainless steel and advanced high-strength steel becomes critical for maintaining competitive differentiation and securing long-term supply agreements in an increasingly demanding market landscape.

What are the Key Data Covered in this Steel Service Centers Market Research and Growth Report?

  • What is the expected growth of the Steel Service Centers Market between 2026 and 2030?

    • USD 82.53 billion, at a CAGR of 4.3%

  • What segmentation does the market report cover?

    • The report is segmented by Service (Cutting, Plate burning, Cambering, Tee splitting, and Others), End-user (Construction, Automotive, Industrial machinery, Energy and power, and Aerospace and defense), Material (Carbon steel, Stainless steel, Alloy steel, Electrical steel, and Tool steel) and Geography (APAC, North America, Europe, Middle East and Africa, South America)

  • Which regions are analyzed in the report?

    • APAC, North America, Europe, Middle East and Africa and South America

  • What are the key growth drivers and market challenges?

    • Surging demand for value-added metal processing and custom inventory solutions, Severe volatility in raw steel prices and inventory devaluation risks

  • Who are the major players in the Steel Service Centers Market?

    • Alro Steel, ArcelorMittal S.A., Baosteel Co. Ltd., Commercial Metals Co., JFE Shoji Steel Service Center, JSW Steel Ltd., Kloeckner and Co SE, Metal One Corporation, Nucor Corp., Reliance Inc., Russel Metals Inc., Salzgitter AG, Samuel Son and Co. Ltd., SSAB AB, Steel Technologies LLC, Steel Warehouse, thyssenkrupp AG, TSDPL, United States Steel Corp. and voestalpine AG

Market Research Insights

  • The Steel Service Centers Market provides essential supply chain flexibility for industrial original equipment manufacturers seeking lean operations. By establishing regional distribution nodes, these facilities enable a lean manufacturing workflow that bypasses the need for massive on-site material storage.
  • The implementation of automated warehouse logistics and digital inventory tracking platforms has optimized stock utilization, reducing inventory holding costs by 18% across major distribution networks. Furthermore, adopting predictive sensor-based maintenance for rotary slitting lines has decreased unscheduled equipment downtime by 24%, directly boosting processing capacity.
  • Operators utilizing advanced toll processing agreements also report a 15% improvement in raw material price hedging effectiveness, ensuring stable production costs despite volatile primary steel markets.

We can help! Our analysts can customize this steel service centers market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Service
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Material
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Steel Service Centers Market 2020 - 2024

Historic Market Size - Data Table on Global Steel Service Centers Market 2020 - 2024 ($ million)

5.2 Service segment analysis 2020 - 2024

Historic Market Size - Service Segment 2020 - 2024 ($ million)

5.3 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.4 Material segment analysis 2020 - 2024

Historic Market Size - Material Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global Steel Service Centers Market

6.2 Impact of Geopolitical Conflicts on Global Steel Service Centers Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Service

8.1 Market segments

Chart on Service - Market share 2025-2030 (%)
Data Table on Service - Market share 2025-2030 (%)

8.2 Comparison by Service

Chart on Comparison by Service
Data Table on Comparison by Service

8.3 Cutting - Market size and forecast 2025-2030

Chart on Cutting - Market size and forecast 2025-2030 ($ million)
Data Table on Cutting - Market size and forecast 2025-2030 ($ million)
Chart on Cutting - Year-over-year growth 2025-2030 (%)
Data Table on Cutting - Year-over-year growth 2025-2030 (%)

8.4 Plate burning - Market size and forecast 2025-2030

Chart on Plate burning - Market size and forecast 2025-2030 ($ million)
Data Table on Plate burning - Market size and forecast 2025-2030 ($ million)
Chart on Plate burning - Year-over-year growth 2025-2030 (%)
Data Table on Plate burning - Year-over-year growth 2025-2030 (%)

8.5 Cambering - Market size and forecast 2025-2030

Chart on Cambering - Market size and forecast 2025-2030 ($ million)
Data Table on Cambering - Market size and forecast 2025-2030 ($ million)
Chart on Cambering - Year-over-year growth 2025-2030 (%)
Data Table on Cambering - Year-over-year growth 2025-2030 (%)

8.6 Tee splitting - Market size and forecast 2025-2030

Chart on Tee splitting - Market size and forecast 2025-2030 ($ million)
Data Table on Tee splitting - Market size and forecast 2025-2030 ($ million)
Chart on Tee splitting - Year-over-year growth 2025-2030 (%)
Data Table on Tee splitting - Year-over-year growth 2025-2030 (%)

8.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

8.8 Market opportunity by Service

Market opportunity by Service ($ million)
Data Table on Market opportunity by Service ($ million)

9. Market Segmentation by End-user

9.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

9.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

9.3 Construction - Market size and forecast 2025-2030

Chart on Construction - Market size and forecast 2025-2030 ($ million)
Data Table on Construction - Market size and forecast 2025-2030 ($ million)
Chart on Construction - Year-over-year growth 2025-2030 (%)
Data Table on Construction - Year-over-year growth 2025-2030 (%)

9.4 Automotive - Market size and forecast 2025-2030

Chart on Automotive - Market size and forecast 2025-2030 ($ million)
Data Table on Automotive - Market size and forecast 2025-2030 ($ million)
Chart on Automotive - Year-over-year growth 2025-2030 (%)
Data Table on Automotive - Year-over-year growth 2025-2030 (%)

9.5 Industrial machinery - Market size and forecast 2025-2030

Chart on Industrial machinery - Market size and forecast 2025-2030 ($ million)
Data Table on Industrial machinery - Market size and forecast 2025-2030 ($ million)
Chart on Industrial machinery - Year-over-year growth 2025-2030 (%)
Data Table on Industrial machinery - Year-over-year growth 2025-2030 (%)

9.6 Energy and power - Market size and forecast 2025-2030

Chart on Energy and power - Market size and forecast 2025-2030 ($ million)
Data Table on Energy and power - Market size and forecast 2025-2030 ($ million)
Chart on Energy and power - Year-over-year growth 2025-2030 (%)
Data Table on Energy and power - Year-over-year growth 2025-2030 (%)

9.7 Aerospace and defense - Market size and forecast 2025-2030

Chart on Aerospace and defense - Market size and forecast 2025-2030 ($ million)
Data Table on Aerospace and defense - Market size and forecast 2025-2030 ($ million)
Chart on Aerospace and defense - Year-over-year growth 2025-2030 (%)
Data Table on Aerospace and defense - Year-over-year growth 2025-2030 (%)

9.8 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

10. Market Segmentation by Material

10.1 Market segments

Chart on Material - Market share 2025-2030 (%)
Data Table on Material - Market share 2025-2030 (%)

10.2 Comparison by Material

Chart on Comparison by Material
Data Table on Comparison by Material

10.3 Carbon steel - Market size and forecast 2025-2030

Chart on Carbon steel - Market size and forecast 2025-2030 ($ million)
Data Table on Carbon steel - Market size and forecast 2025-2030 ($ million)
Chart on Carbon steel - Year-over-year growth 2025-2030 (%)
Data Table on Carbon steel - Year-over-year growth 2025-2030 (%)

10.4 Stainless steel - Market size and forecast 2025-2030

Chart on Stainless steel - Market size and forecast 2025-2030 ($ million)
Data Table on Stainless steel - Market size and forecast 2025-2030 ($ million)
Chart on Stainless steel - Year-over-year growth 2025-2030 (%)
Data Table on Stainless steel - Year-over-year growth 2025-2030 (%)

10.5 Alloy steel - Market size and forecast 2025-2030

Chart on Alloy steel - Market size and forecast 2025-2030 ($ million)
Data Table on Alloy steel - Market size and forecast 2025-2030 ($ million)
Chart on Alloy steel - Year-over-year growth 2025-2030 (%)
Data Table on Alloy steel - Year-over-year growth 2025-2030 (%)

10.6 Electrical steel - Market size and forecast 2025-2030

Chart on Electrical steel - Market size and forecast 2025-2030 ($ million)
Data Table on Electrical steel - Market size and forecast 2025-2030 ($ million)
Chart on Electrical steel - Year-over-year growth 2025-2030 (%)
Data Table on Electrical steel - Year-over-year growth 2025-2030 (%)

10.7 Tool steel - Market size and forecast 2025-2030

Chart on Tool steel - Market size and forecast 2025-2030 ($ million)
Data Table on Tool steel - Market size and forecast 2025-2030 ($ million)
Chart on Tool steel - Year-over-year growth 2025-2030 (%)
Data Table on Tool steel - Year-over-year growth 2025-2030 (%)

10.8 Market opportunity by Material

Market opportunity by Material ($ million)
Data Table on Market opportunity by Material ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.3.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.3.2 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.3.3 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.3.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.3.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.3.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.4 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.4.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.4.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.4.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.5 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.5.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.5.2 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.5.3 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.5.4 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.5.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.5.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.6 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.6.1 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.6.2 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.4 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.5 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.7.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.7.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.7.3 Colombia - Market size and forecast 2025-2030

Chart on Colombia - Market size and forecast 2025-2030 ($ million)
Data Table on Colombia - Market size and forecast 2025-2030 ($ million)
Chart on Colombia - Year-over-year growth 2025-2030 (%)
Data Table on Colombia - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Surging demand for value-added metal processing and custom inventory solutions
Expansion of automotive production and adoption of advanced high-strength steels
Rising global infrastructure spending and megaproject construction activities

13.2 Market challenges

Severe volatility in raw steel prices and inventory devaluation risks
High capital requirements and technological barriers for advanced equipment upgrades
Stringent environmental regulations and complex decarbonization mandates

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Digital transformation and warehouse automation in steel service operations
Accelerated adoption of sustainable green steel and decarbonization protocols
Industry consolidation and strategic expansion of regional logistics networks

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Alro Steel

Alro Steel - Overview
Alro Steel - Product / Service
Alro Steel - Key offerings
SWOT

15.5 ArcelorMittal S.A.

ArcelorMittal S.A. - Overview
ArcelorMittal S.A. - Business segments
ArcelorMittal S.A. - Key offerings
ArcelorMittal S.A. - Segment focus
SWOT

15.6 JFE Shoji Steel Service Center

JFE Shoji Steel Service Center - Overview
JFE Shoji Steel Service Center - Product / Service
JFE Shoji Steel Service Center - Key offerings
SWOT

15.7 JSW Steel Ltd.

JSW Steel Ltd. - Overview
JSW Steel Ltd. - Product / Service
JSW Steel Ltd. - Key offerings
SWOT

15.8 Kloeckner and Co SE

Kloeckner and Co SE - Overview
Kloeckner and Co SE - Product / Service
Kloeckner and Co SE - Key offerings
SWOT

15.9 Nucor Corp.

Nucor Corp. - Overview
Nucor Corp. - Business segments
Nucor Corp. - Key news
Nucor Corp. - Key offerings
Nucor Corp. - Segment focus
SWOT

15.10 Reliance Inc.

Reliance Inc. - Overview
Reliance Inc. - Product / Service
Reliance Inc. - Key offerings
SWOT

15.11 Russel Metals Inc.

Russel Metals Inc. - Overview
Russel Metals Inc. - Product / Service
Russel Metals Inc. - Key offerings
SWOT

15.12 Salzgitter AG

Salzgitter AG - Overview
Salzgitter AG - Business segments
Salzgitter AG - Key offerings
Salzgitter AG - Segment focus
SWOT

15.13 SSAB AB

SSAB AB - Overview
SSAB AB - Business segments
SSAB AB - Key offerings
SSAB AB - Segment focus
SWOT

15.14 Steel Technologies LLC

Steel Technologies LLC - Overview
Steel Technologies LLC - Product / Service
Steel Technologies LLC - Key offerings
SWOT

15.15 Steel Warehouse

Steel Warehouse - Overview
Steel Warehouse - Product / Service
Steel Warehouse - Key offerings
SWOT

15.16 thyssenkrupp AG

thyssenkrupp AG - Overview
thyssenkrupp AG - Business segments
thyssenkrupp AG - Key offerings
thyssenkrupp AG - Segment focus
SWOT

15.17 TSDPL

TSDPL - Overview
TSDPL - Product / Service
TSDPL - Key offerings
SWOT

15.18 United States Steel Corp.

United States Steel Corp. - Overview
United States Steel Corp. - Business segments
United States Steel Corp. - Key offerings
United States Steel Corp. - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Steel Service Centers market growth will increase by USD 82526.6 million during 2026-2030.

The Steel Service Centers market is expected to grow at a CAGR of 4.3% during 2026-2030.

Steel Service Centers market is segmented by Service (Cutting, Plate burning, Cambering, Tee splitting, Others) End-user (Construction, Automotive, Industrial machinery, Energy and power, Aerospace and defense) Material (Carbon steel, Stainless steel, Alloy steel, Electrical steel, Tool steel)

Alro Steel, ArcelorMittal S.A., Baosteel Co. Ltd., Commercial Metals Co., JFE Shoji Steel Service Center, JSW Steel Ltd., Kloeckner and Co SE, Metal One Corporation, Nucor Corp., Reliance Inc., Russel Metals Inc., Salzgitter AG, Samuel Son and Co. Ltd., SSAB AB, Steel Technologies LLC, Steel Warehouse, thyssenkrupp AG, TSDPL, United States Steel Corp., voestalpine AG are a few of the key vendors in the Steel Service Centers market.

APAC will register the highest growth rate of 62.9% among the other regions. Therefore, the Steel Service Centers market in APAC is expected to garner significant business opportunities for the vendors during the forecast period.

China, India, Japan, South Korea, Australia, Indonesia, US, Canada, Mexico, Germany, France, Italy, UK, Spain, The Netherlands, Turkey, Saudi Arabia, South Africa, UAE, Israel, Brazil, Argentina, Colombia

  • Surging demand for value-added metal processing and custom inventory solutions is the driving factor this market.

The Steel Service Centers market vendors should focus on grabbing business opportunities from the Service segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
